4 min read • Published 30 days ago • Updated Oct 19, 2026
Load this article strategy with your numbers before you decide.
You're 65 with $1.5 million saved.
Should you use $300,000 to buy an annuity that pays you every month? Or leave it invested and take money out yourself?
The answer may change if you live to 75, 85, or 95.
An annuity is a contract with an insurance company.
You pay a lump sum. In return, you can receive monthly income for life.
For this example, we'll assume $300,000 buys $1,800 per month.
That amount is hypothetical, not an actual insurance quote.
| Product | What it offers |
|---|---|
| New York Life Guaranteed Lifetime Income Annuity | Predictable lifetime payments, with contract options |
| MassMutual RetireEase | Immediate income with lifetime and beneficiary options |
Both are real insurance products.
We are not comparing actual premiums or claiming either company pays $1,800 monthly.
You would need personalized quotes to compare their payouts.
Let's compare two choices.
Option 1 — Buy an annuity
Use $300,000 to receive $1,800 every month for life.
Option 2 — Keep it invested
Keep $300,000 invested and withdraw $1,800 every month.
For investing, we'll assume a steady 5% annual return.
The monthly withdrawal is $21,600 annually, or 7.2% of the starting investment.
That's higher than the traditional 4% starting-withdrawal guideline.
If you purchase the annuity from your $1.5 million portfolio, the other $1.2 million remains invested.
Our comparison focuses only on the $300,000 used for this decision.
| Age 75 | Age 85 | Age 95 | |
|---|---|---|---|
| Annuity income received | $216,000 | $432,000 | $648,000 |
| Investment withdrawals received | $216,000 | $432,000 | $503,089 |
| Investments remaining | $210,815 | $65,541 | $0 |
At 75, investing leaves about $211,000 in your account.
At 85, about $66,000 remains.
Around age 88, the invested amount runs out under these assumptions.
At 95, the lifetime annuity has paid $648,000 and continues paying while you're alive, subject to the insurer's ability to meet its obligations.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
An annuity offers predictable income.
Even if you live to 95 or beyond, a lifetime annuity continues paying.
But you generally give up access to the original $300,000. With a basic life-only annuity, payments stop when you die.
Investing gives you flexibility.
You control your money and can leave the remaining balance to your family.
But markets can fall, and your money may run out.
Neither example increases monthly income for inflation.
The same $1,800 will likely buy much less in 20 or 30 years.
Investment returns also won't be a steady 5% every year. Actual market performance could make the money last longer or run out sooner.
What happens if you use $300,000 from your retirement portfolio to purchase an annuity?
Try an illustrative annuity that pays $1,800 monthly starting at age 65.
See how purchasing a $300,000 annuity paying an illustrative $1,800 monthly from age 65 affects your retirement plan.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Nestly Lab applies the scenario to your saved retirement plan.
The payment amount is hypothetical, not an insurance quote.
An annuity may offer peace of mind if you live a long life.
Investing may offer more flexibility and long-term growth.
Neither choice is automatically better.
The important question is whether you value guaranteed monthly income more than keeping access to your investments.
Independent Educational Disclosure
Nestly is not affiliated with New York Life or MassMutual. We receive no commissions, referral fees, advertising payments, or other compensation from either company.
We do not endorse, recommend, or sell their annuity products.
This article is for educational purposes only and is not personalized financial, investment, tax, or insurance advice.
All payout amounts and investment returns are hypothetical and are not guaranteed. Actual annuity payments depend on the insurer, age, contract terms, interest rates, and selected benefits.
Annuity guarantees depend on the issuing insurance company's financial strength and claims-paying ability.
Load "Test $300K in Lifetime Income" against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
See how a spouse's retirement savings and income can dramatically improve retirement success, with clear calculations comparing a base plan, pension, rental income, and combined household finances.
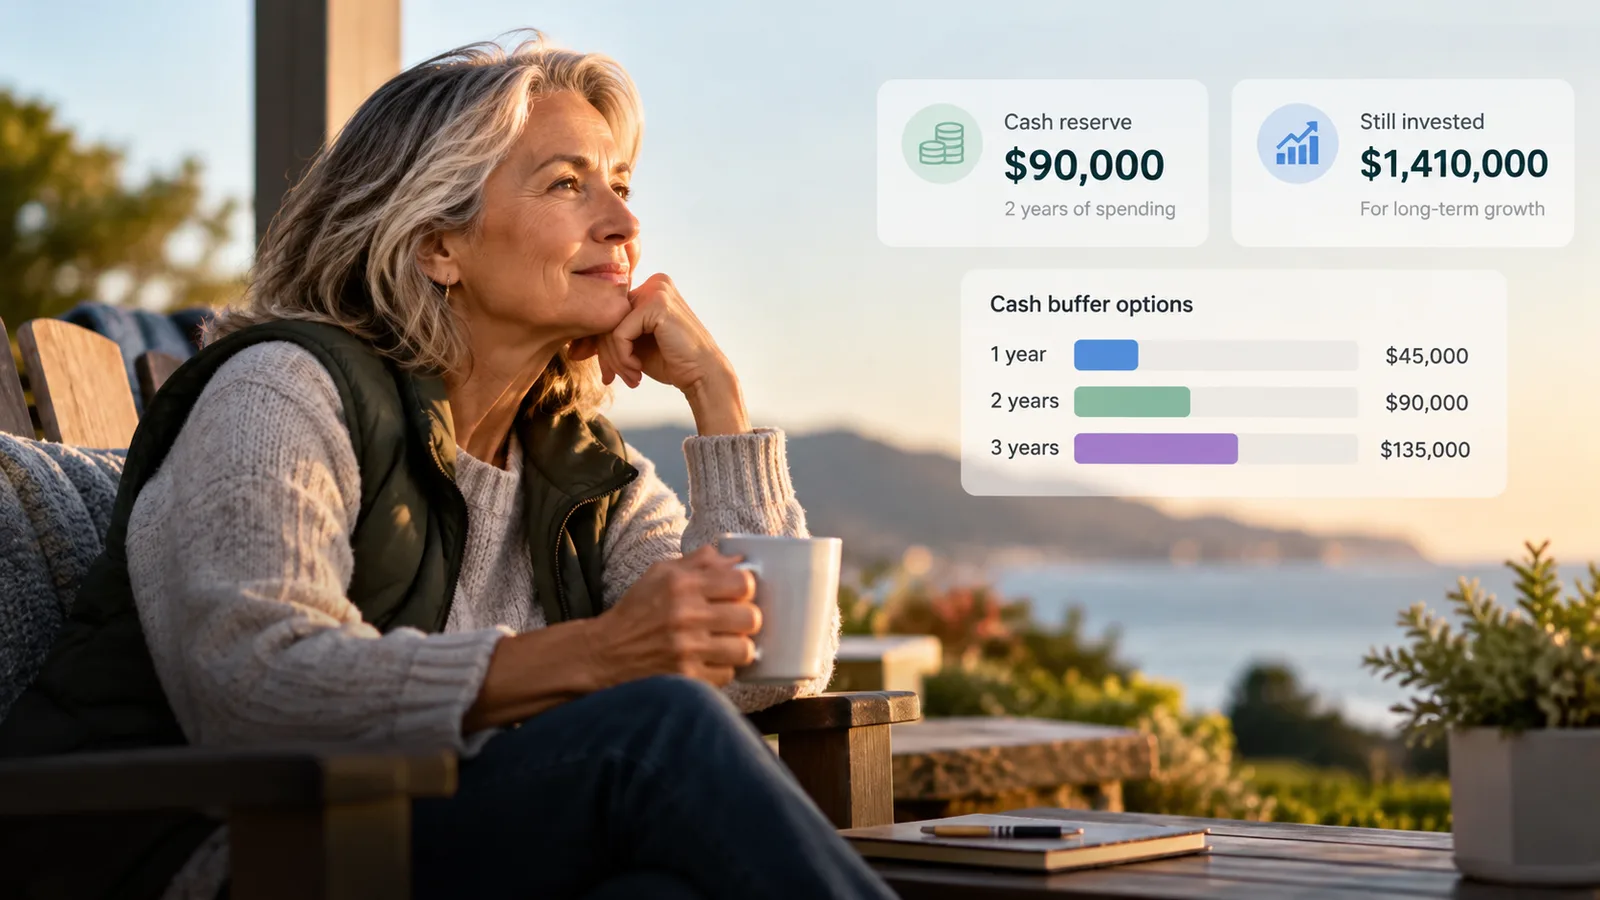
One year, two years, or three? See how keeping cash available can protect retirement spending—and what you give up by investing less.
See how a smaller Social Security benefit could change your retirement withdrawals—and three ways to respond.
