5 min read • Published about 1 month ago
Load all 3 article strategies with your numbers before you decide.
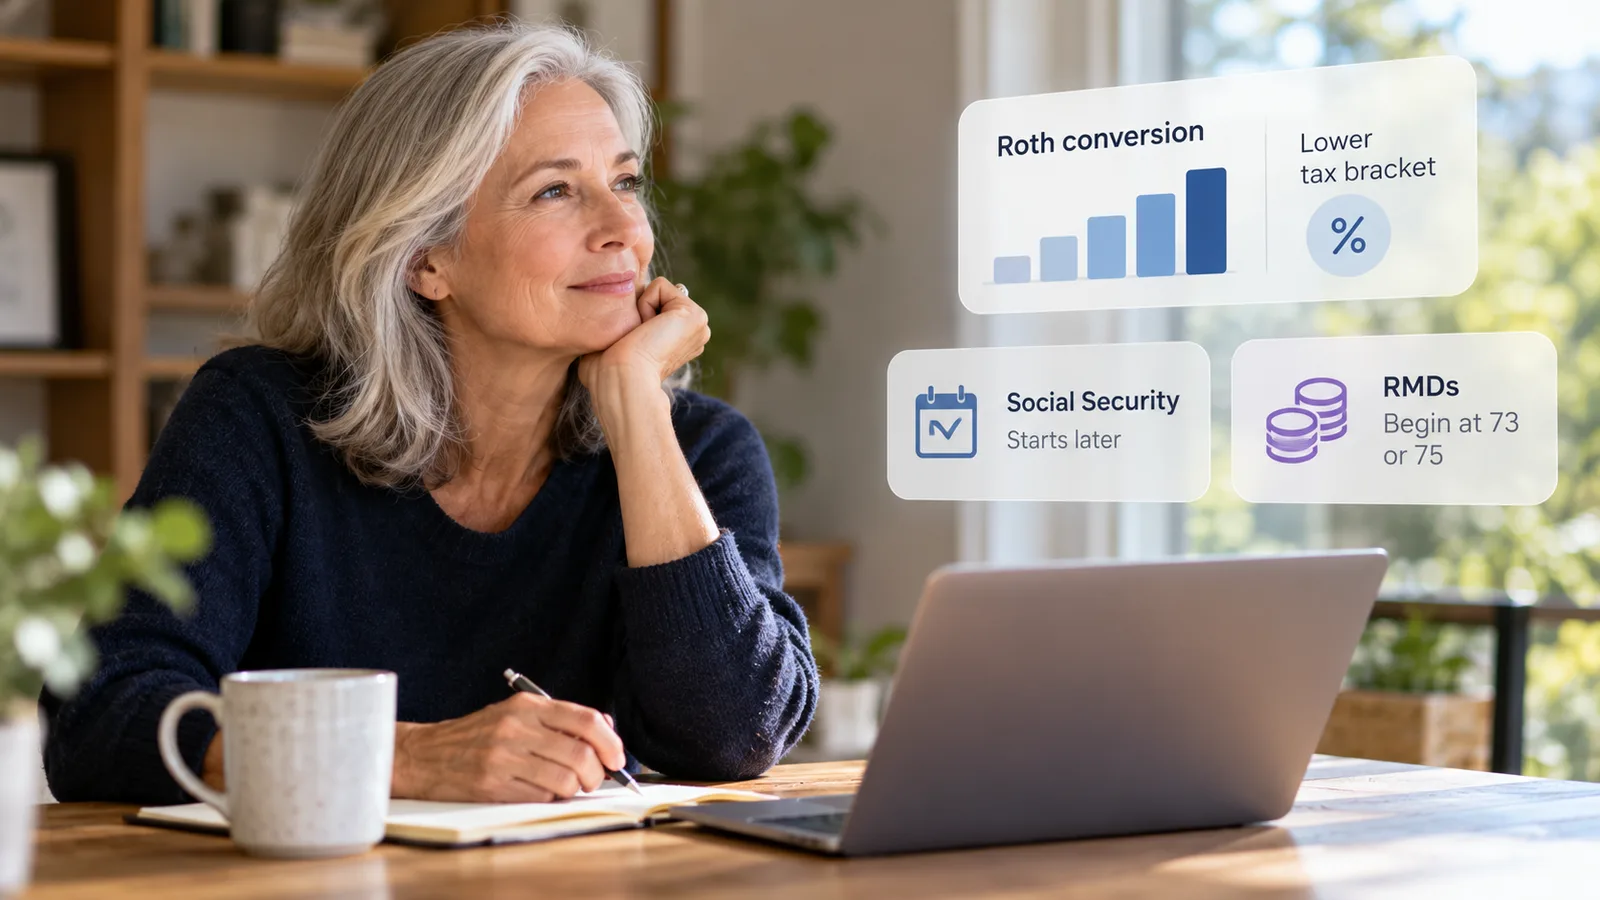
The day you stop working, your paycheck stops. Your tax bill usually doesn't stop right away, but for many people it drops sharply. That gap, before Social Security and required withdrawals pile on, is what planners call the Roth conversion window.
A Roth conversion moves money from a pre-tax account, such as a traditional IRA or 401(k), into a Roth IRA. You pay ordinary income tax on the amount converted this year. In exchange, qualified withdrawals from the Roth later are generally tax-free, and Roth IRAs have no required minimum distributions (RMDs) during the owner's lifetime.
The trade is simple: pay tax now, at a rate you choose, to avoid tax later, at a rate you may not control.
Many people have an unusual stretch between the last paycheck and the first big pile of taxable income. Wages are gone. Social Security may not have started. RMDs have not begun. Taxable income can be unusually low, which means the lower federal brackets may have room to spare.
Federal income tax is marginal. Each dollar of conversion is taxed at the rate of the bracket it lands in, stacked on top of your other income. Under current law the rates are:
Notice the jump from 12% to 22%. Many conversion strategies aim to use up the 10% and 12% brackets, or stop at the top of the 22% or 24% bracket, so a conversion doesn't push income into a much higher rate than you would pay later.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
| Age | Why it matters |
|---|---|
| 59½ | Withdrawals of converted money avoid the early-withdrawal penalty (the five-year rule can still apply before this age). |
| 62 | Earliest Social Security claim, which can end the low-income stretch. |
| 65 | Medicare begins. |
| 73 or 75 | RMDs begin, depending on your birth year. |
The window often runs from retirement to the year you claim Social Security or hit your first RMD, whichever comes first.
A fixed amount each year. You pick a dollar figure, such as $20,000, and convert it every year for a set number of years. It is predictable and easy to budget.
Filling a bracket. You convert as much as fits under a chosen bracket, such as the top of the 22% bracket. The amount changes each year as your other income changes, but your rate stays controlled.
Neither is automatically better. Which one is useful for you depends on your account balances, other income, and the tax rates you expect later. Try each one against your own plan:
Both options convert from age 62 to 72. Your savings and other inputs stay the same.
Convert $20,000 a year from 62 to 72
A steady, predictable conversion. Your tax rate on it can change from year to year as other income changes.
These are examples to compare, not recommendations.
Test with my planConverting is not free money. Before you do it, check three things:
You can see how a conversion plan changes when premium surcharges are modeled:
See how a $20,000 annual Roth conversion from 62 to 72 looks once Medicare IRMAA surcharges are included.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Your 60s may be your cheapest tax years, but only if you use them on purpose. The goal is not to avoid tax; it is to pick the year and the rate, instead of leaving both to the schedule of future required withdrawals. Run the numbers against your own plan before you convert, and consider checking the details with a tax professional.
This article is for education only and is not tax or investment advice.
Load all 3 tests from this article against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
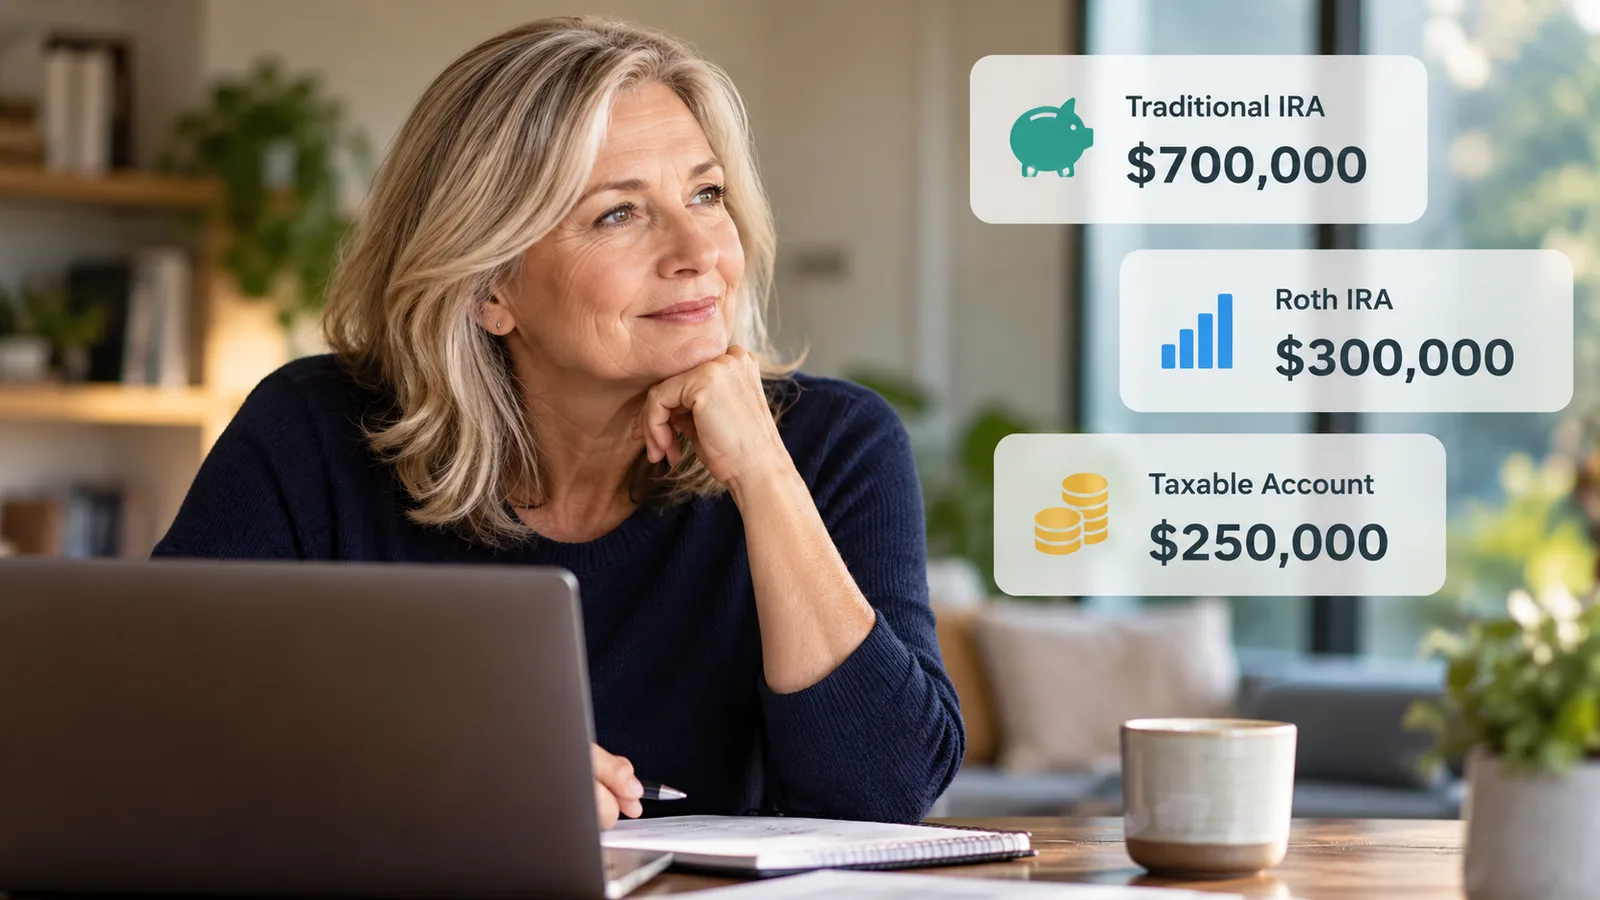
Roth money can be one of your most flexible retirement accounts. The question is not just whether you can spend it, but when using it may actually help.
Waiting to touch your traditional retirement accounts can feel logical. But the years before RMDs begin may be an opportunity to choose when you pay taxes.
Should you use $300,000 to buy lifetime income or keep it invested? Compare what happens at ages 75, 85, and 95.
