5 min read • Published 5 months ago • Updated Jun 20, 2026
Load this article strategy with your numbers before you decide.
Many retirement calculators assume both spouses retire at the same time.
Real life often looks different.
One spouse may be ready to leave work at 60 while the other plans to continue until 65, 67, or even 70.
This creates an important question:
Can one spouse retire early without putting the entire retirement plan at risk?
In many cases, the answer is yes.
In fact, having one spouse continue working can create advantages that many couples overlook.
Retirement is rarely a perfectly synchronized event.
Common reasons include:
For many households, retirement happens gradually rather than all at once.
This approach is often called:
Phased Retirement
And it can be surprisingly effective.
Many people assume working longer simply means earning more money.
But the benefits can extend far beyond salary.
This may be the most valuable benefit.
Consider:
Retire at 60

Medicare begins at 65

Five years of healthcare costs remain
If the working spouse provides employer-sponsored health insurance, the retired spouse may be able to remain covered.
For some households, this can save tens of thousands of dollars before Medicare eligibility begins.
If one spouse continues earning income:
Salary:
$80,000 per year
Portfolio withdrawals may be significantly reduced during the first years of retirement.
That creates two powerful benefits:
This can have a lasting impact on retirement success.
The working spouse may still contribute to:
While one spouse is enjoying retirement, the household may still be building retirement assets.
Many couples automatically claim Social Security at the same age.
That isn't always optimal.
Spouse A Claims: 67

Spouse B Claims: 67
Retired Spouse Claims: 65

Working Spouse Claims: 70
Retired Spouse Claims: 62

Working Spouse Claims: 70
In some cases, staggering claim ages can:
The best strategy depends on income, age differences, health, and retirement goals.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Pros:
Cons:
Example:
Income Coverage: 78%

Success Rate: 84%

Monthly Income: $7,800
Pros:
Cons:
Example:
Income Coverage: 95%

Success Rate: 93%

Monthly Income: $9,200
Pros:
Cons:
Example:
Income Coverage: 108%

Success Rate: 97%

Monthly Income: $10,400
Many retirees discover they don't actually need a full-time salary.
Sometimes a small amount of income can make a huge difference.
Examples:
$1,000/month
or
$2,000/month
from:
Even modest income can reduce withdrawal pressure and improve long-term retirement outcomes.
Before retiring at 60, ask:
Most couples are surprised by how much flexibility these decisions can create.
Retirement isn't about finding one perfect answer.
It's about understanding tradeoffs.
A strategy that maximizes:
Monthly Income
may not maximize:
Lifetime Wealth
A strategy that maximizes:
Lifetime Benefits
may not provide the greatest flexibility today.
The goal is to find the balance that fits your household.
Most retirement tools show only one outcome.
Nestly Lab helps you compare multiple retirement paths side by side.
You can model:
AI then ranks the scenarios based on:
Because for many couples, the question isn't:
Can we retire at 60?
The better question is:
Which retirement path gives us the best combination of freedom, income, and long-term security?
That's exactly what scenario planning is designed to answer.
See how retiring 5 years earlier plays out if your spouse keeps working and covers healthcare.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Load "Retire at 60" against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
Compare part-time retirement with working full-time for a few more years. Learn how even modest income can reduce portfolio withdrawals, preserve healthcare options, and make earlier retirement more realistic.
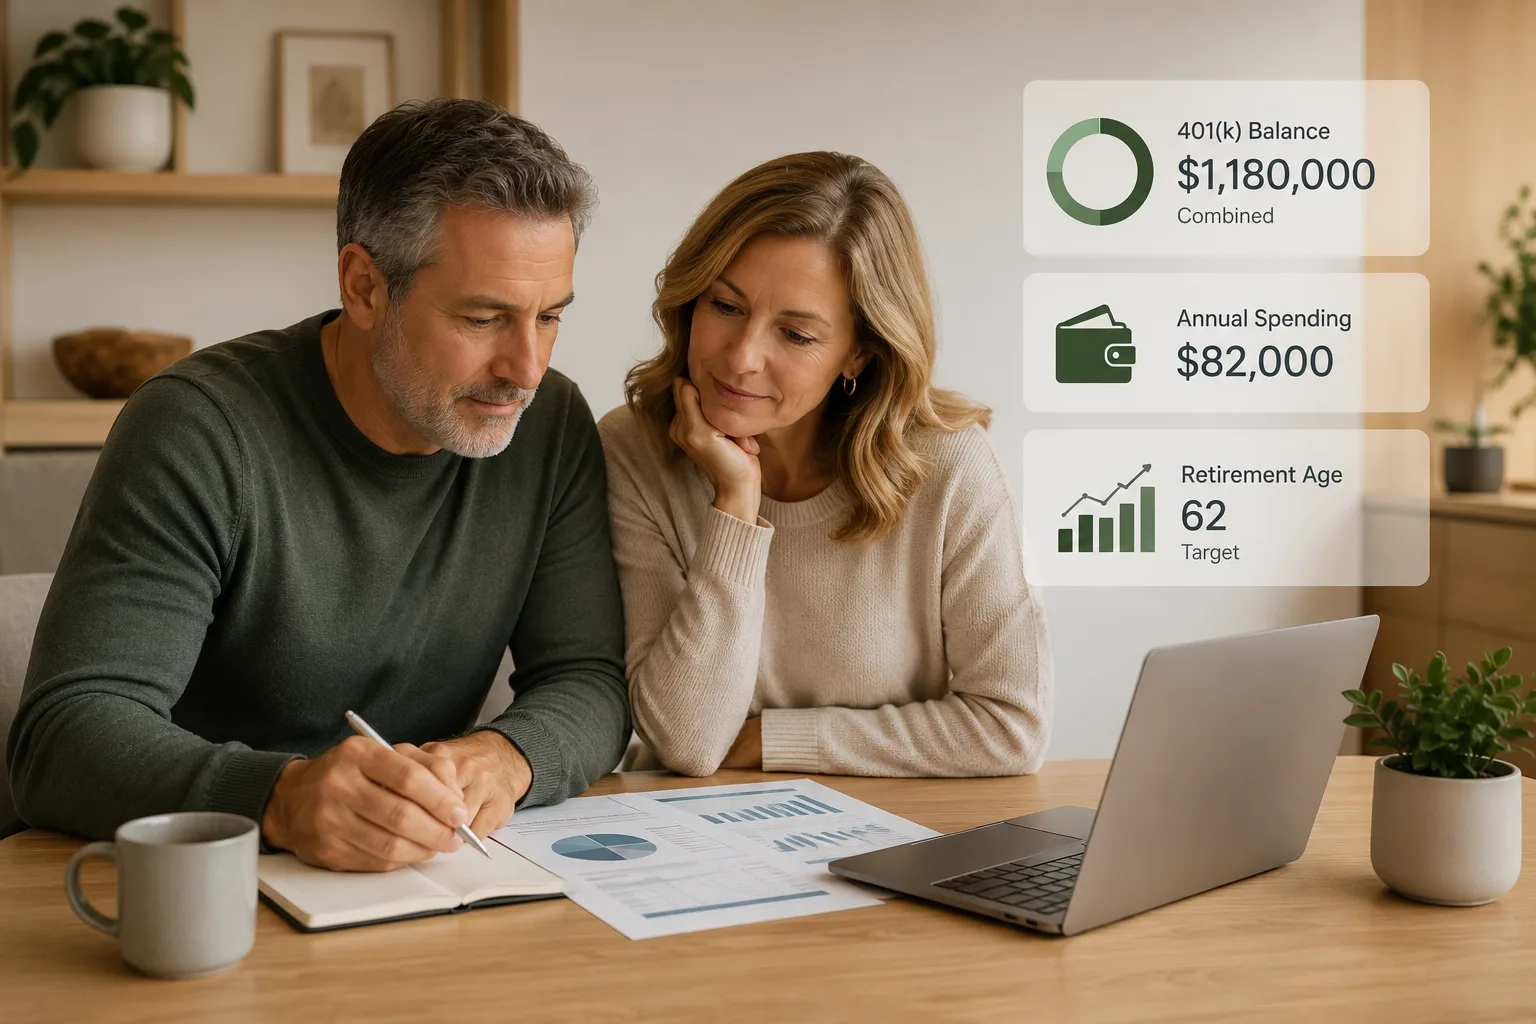
See estimated 401(k) balances by spending level, understand what changes the number, and compare retirement strategies with Nestly Lab.
One million dollars may be enough for retirement—or fall short—depending on your spending, retirement age, Social Security, healthcare, taxes, and market conditions.
