6 min read • Published 5 months ago • Updated Jun 23, 2026
Most people think an emergency fund is only for short-term surprises.
A car repair.
A medical bill.
A job loss.
But an emergency fund can also protect your retirement plan.
Without cash reserves, one unexpected expense can force you to:
That is why an emergency fund is not separate from retirement planning.
It is part of the retirement plan.
An emergency fund is money set aside for unexpected expenses.
It is not money for:
It exists for financial surprises you cannot predict.
Think of it as a buffer between your life and your long-term retirement assets.
Imagine this situation:
Retirement Portfolio:
$750,000

Emergency Fund:
$0
Now imagine a $20,000 emergency happens during a market downturn.
Without cash reserves, you may need to sell investments when prices are down.
That can turn a temporary setback into a permanent retirement problem.
Now compare this:
Retirement Portfolio:
$750,000

Emergency Fund:
$25,000
The emergency fund covers the expense.
The retirement portfolio stays invested.
That is the real value of cash reserves.
The right amount depends on your age, job stability, income sources, and retirement stage.
| Situation | Suggested Emergency Fund |
|---|---|
| Stable job | 3–6 months of expenses |
| Dual-income household | 3–6 months of expenses |
| Single-income household | 6–9 months of expenses |
| Self-employed | 9–12 months of expenses |
| Age 50+ and near retirement | 6–12 months of expenses |
| Retired | 12–24 months of spending needs |
These are starting points, not fixed rules.
A household with stable income, low debt, and strong benefits may need less.
A household with variable income, health concerns, or large fixed expenses may need more.
Use it for real emergencies.
A planned expense is not an emergency.
If you know a cost is coming, it should be part of your budget rather than your emergency fund.
The goal of an emergency fund is not maximum return.
The goal is:
Safety first

Access second

Yield third
| Option | Safety | Access | Best Use |
|---|---|---|---|
| Checking account | High | Immediate | 1 month of expenses |
| High-yield savings account | High | Very high | Core emergency fund |
| Money market fund | High | High | Larger cash reserves |
| Treasury bills | Very high | Medium | Longer reserve bucket |
| Stocks | Low | High | Not ideal for emergencies |
| Crypto | Very low | High | Not appropriate for emergencies |
Emergency funds should generally avoid assets that can fall sharply in value.
If you need the money during a downturn, you do not want your emergency fund to be down too.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
A cash reserve does not need to sit all in one account.
You can structure it in layers.
| Bucket | Purpose | Example Amount |
|---|---|---|
| Checking | Immediate access | 1 month of expenses |
| High-yield savings | Short-term emergencies | 3–6 months of expenses |
| Treasury bills or money market | Longer reserve | Remaining reserve |
This approach gives you:
The key is keeping the money stable and available.
Emergency funds become especially important near or during retirement.
Why?
Because of sequence-of-returns risk.
If markets fall early in retirement and you are forced to sell investments, your portfolio has less time to recover.
An emergency fund can help you avoid selling during bad markets.
| Scenario | Emergency Fund | Result |
|---|---|---|
| No emergency fund | $0 | Forced portfolio withdrawals |
| 3-month fund | Moderate protection | Some flexibility |
| 6-month fund | Strong protection | Less portfolio pressure |
| 12-month fund | High protection | Greater retirement resilience |
Cash may not generate the highest return.
But it can protect the assets that do.
There is also such a thing as too much cash.
If you keep too much money outside investments for many years, inflation can reduce purchasing power.
That is why balance matters.
A strong emergency fund should protect your retirement plan without preventing your long-term assets from growing.
The right amount should feel safe, but not excessive.
Emergency funds are not just about today.
They can change your retirement outcomes.
With Nestly Lab, you can compare different reserve strategies, including:
AI then ranks each path based on retirement income, success probability, portfolio longevity, and resilience.
Because retirement planning is not only about growing wealth.
It is also about protecting your plan when life does not go as expected.
Start from your current plan, change one assumption from the article, and save the version only if it is worth comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
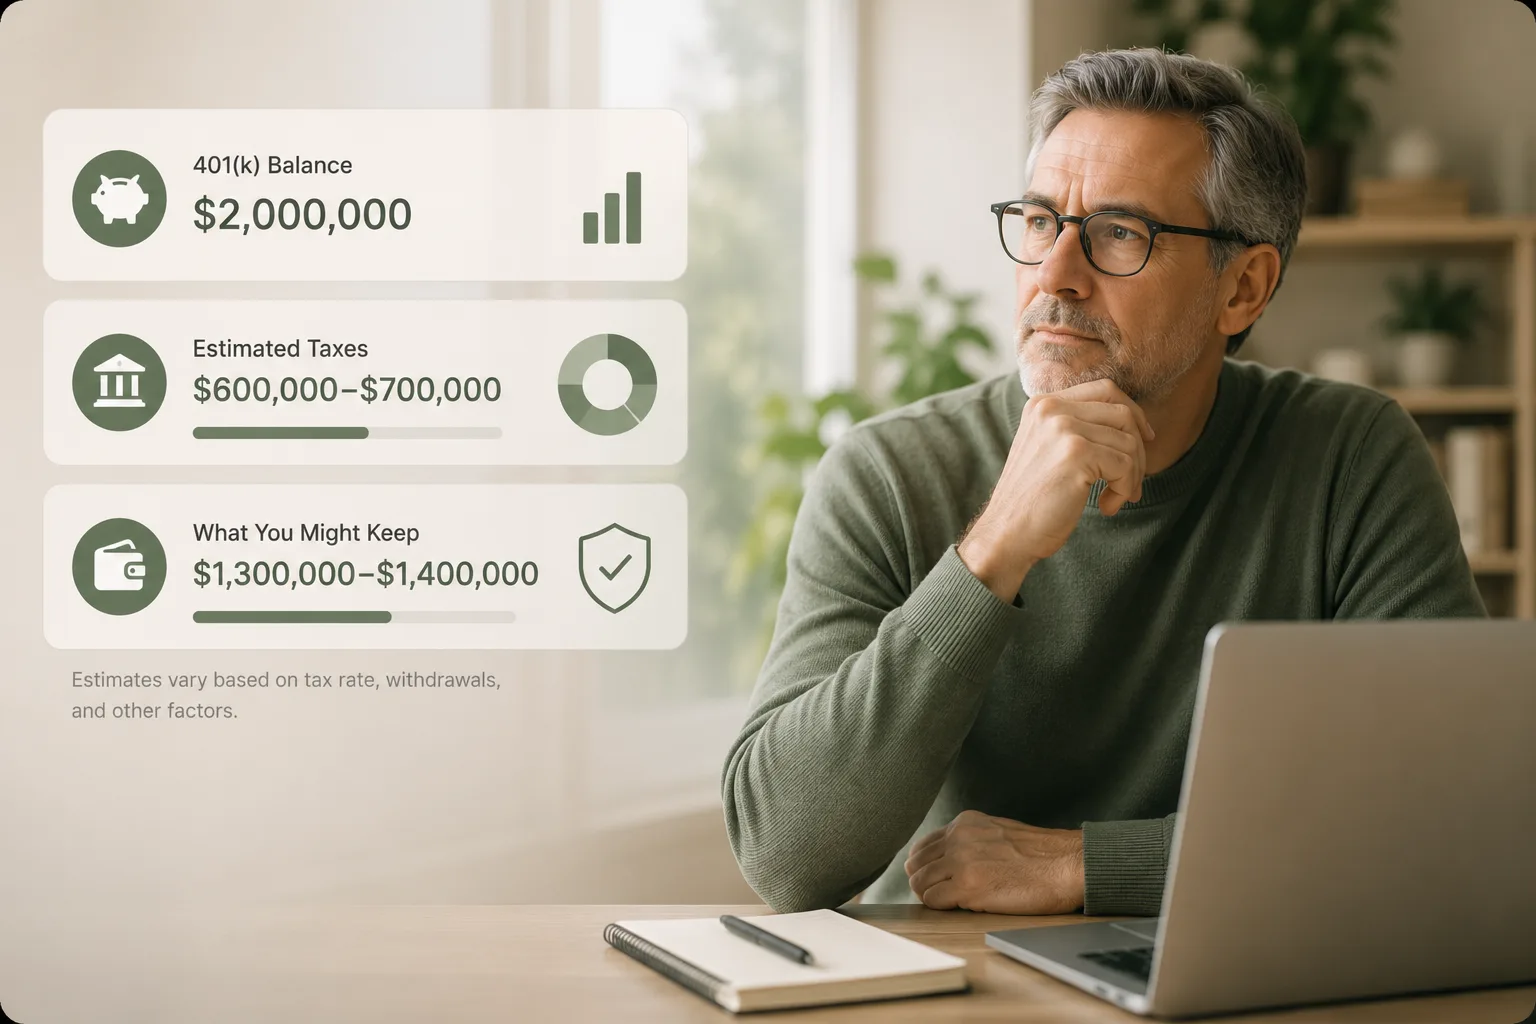
Two retirees can both have $2 million and still have very different amounts available to spend. See why Traditional, Roth, and taxable account balances matter in retirement.
See how working one more year can improve retirement through extra savings, portfolio growth, avoided withdrawals, a shorter retirement, and better timing around Social Security and Medicare.
Estimate how much you may need invested for retirement based on spending, Social Security, retirement age, healthcare, and other income.
