5 min read • Published about 1 month ago
You have $1.5 million saved for retirement. Your plan says you can afford to stop working.
But how much of that money should stay in cash?
Too little, and you might have to sell investments when the market is down. Too much, and money meant to support you for 25 or 30 years may grow too slowly.
The goal isn't to hold as much cash as possible. It's to hold enough to make withdrawals easier without giving up too much long-term growth.
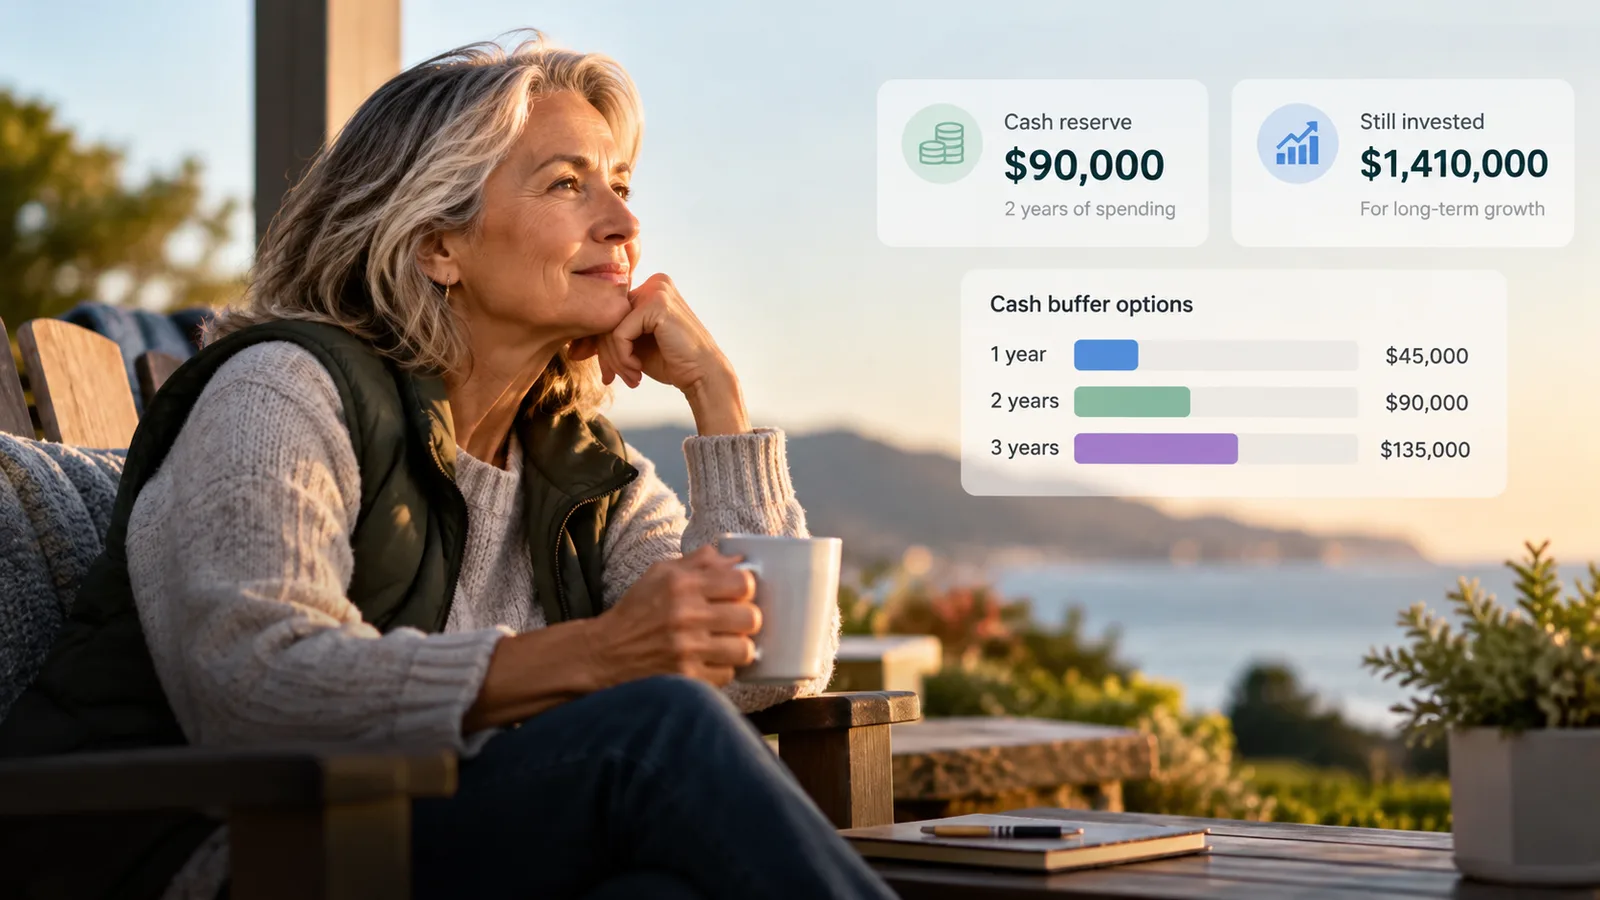
Imagine you retire at 65 with:
Your investments need to cover the remaining $45,000 a year, before accounting for taxes or changes in income and spending.
That $45,000—not necessarily your full $75,000 budget—is a useful starting point for your cash buffer.
| Cash to cover withdrawals | Amount kept in cash | Remaining invested |
|---|---|---|
| 1 year | $45,000 | $1,455,000 |
| 2 years | $90,000 | $1,410,000 |
| 3 years | $135,000 | $1,365,000 |
These are examples, not recommendations. Your actual buffer depends on when your income starts, your withdrawal taxes, and other sources of ready money.
Suppose stocks fall sharply in your first year of retirement.
If you have no money set aside, you may need to sell investments to pay your bills. A withdrawal made after a large loss leaves fewer shares available to recover when markets improve.
A cash buffer gives you another option: pay expenses from cash for a while and give investments time to recover. It does not guarantee a recovery, and it won't prevent investment losses.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Because retirement may last decades.
Cash in an insured savings account or short-term Treasury securities can offer stability and interest. But it often has a lower long-term expected return than a diversified investment portfolio. Inflation also makes future expenses more expensive.
If you keep $135,000 rather than $45,000 in cash, that's $90,000 less invested. You gain more breathing room, but you also give that $90,000 less opportunity for market growth.
The trade-off is straightforward:
| Less cash | More cash |
|---|---|
| More money invested for potential growth | More money ready for near-term spending |
| Greater chance you'll sell investments during a downturn | Less need to sell investments immediately |
| Smaller reserve for surprises | Larger reserve, with a potential growth cost |
Neither side wins automatically. Some retirees value extra stability; others have reliable income, flexible spending, or more accessible assets.
One year can work when you have predictable income, flexible spending, and can tolerate market swings. But you have less time to adjust after a downturn.
Two years offers a middle ground: more room to manage withdrawals while leaving most of the portfolio invested.
Three years provides a larger cushion, which may feel useful if you rely heavily on portfolio withdrawals or find it hard to reduce spending in a bad market. The cost is keeping more money out of long-term investments.
These are starting points for comparison, not universal rules. Cash also needs a refill plan. When markets are healthy—or other income arrives—you can consider replenishing what you spent. You may need to change that approach during a long decline.
Compare these three approaches using your own savings and planned spending. Look at your plan's success estimate, lower-end outcomes, and ending portfolio—not just the comfort of the cash balance.
First, subtract dependable retirement income from your spending needs. Then ask how long you'd be comfortable meeting the remaining withdrawals without selling stocks.
Keep a separate allowance for emergencies or large near-term purchases that aren't already in your retirement budget. Choose where to hold the reserve based on safety, access, and yield—not yield alone. Check the balance at least annually as spending and income change.
Bottom line: You don't need to choose between keeping everything safe and investing everything for growth. A cash reserve is there to help you stay with your retirement plan when markets get uncomfortable. The best size is the one that gives you enough flexibility without unnecessarily limiting long-term growth.
Start from your current plan, change one assumption from the article, and save the version only if it is worth comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
Should you use $300,000 to buy lifetime income or keep it invested? Compare what happens at ages 75, 85, and 95.
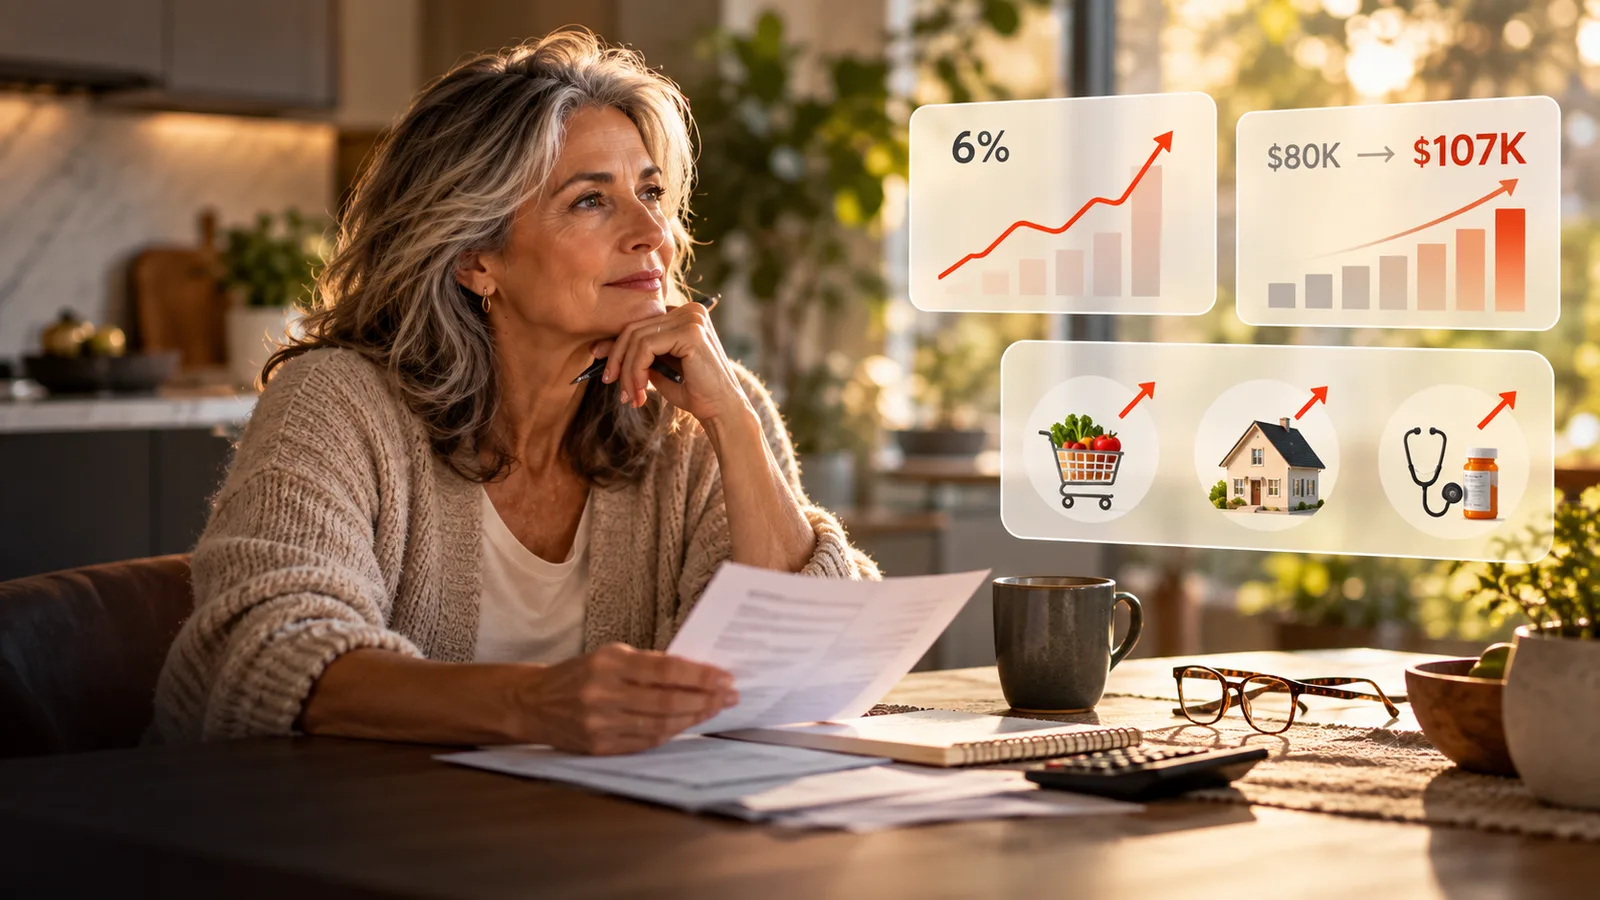
A few years of high inflation right after retirement can raise withdrawals quickly. See how maintaining your lifestyle—or temporarily adjusting it—can change the pressure on your plan.
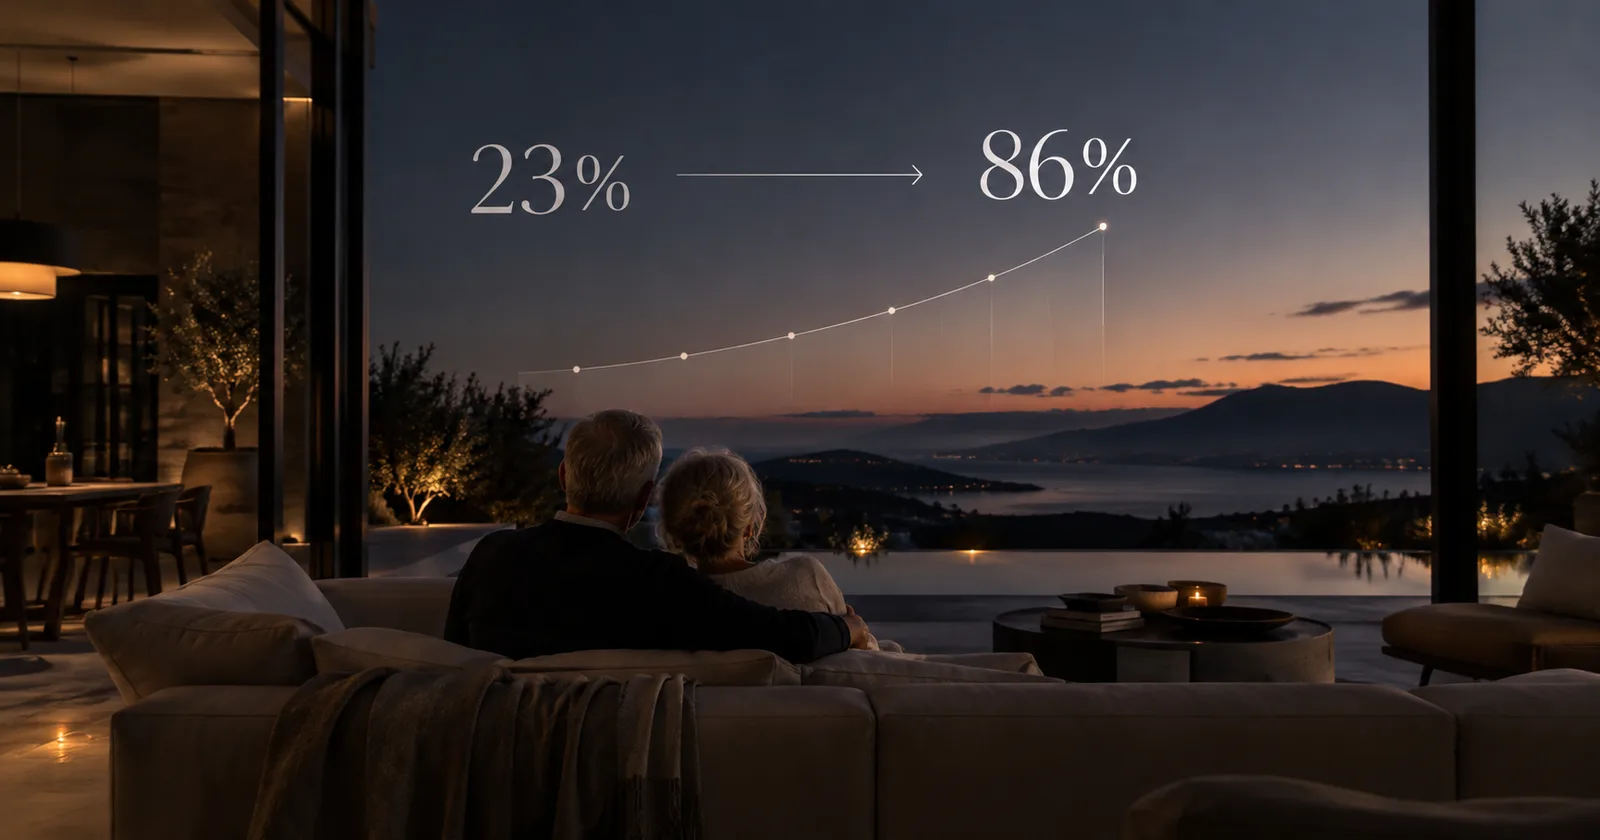
See how a spouse's retirement savings and income can dramatically improve retirement success, with clear calculations comparing a base plan, pension, rental income, and combined household finances.
