6 min read • Published about 2 months ago
You’re 65 with $1.5 million invested.
The home you want costs $500,000.
You can pay cash and have no mortgage. Or you can borrow and keep more money invested.
Paying cash lowers your monthly bills. Taking a mortgage leaves more money available for other needs.
Which choice leaves you with a retirement you can comfortably afford?
Assume a 30-year fixed mortgage at 6.5%. This is an example rate, not a current quote.
Assume you can access the purchase money. The figures below are before closing costs and any taxes from selling investments or withdrawing retirement funds.
| Pay cash | Put 50% down | Put 20% down | |
|---|---|---|---|
| Money paid toward the home | $500,000 | $250,000 | $100,000 |
| Investments left | $1,000,000 | $1,250,000 | $1,400,000 |
| Mortgage debt | $0 | $250,000 | $400,000 |
| Monthly principal and interest | $0 | $1,580 | $2,528 |
Every option still needs a budget for property taxes, insurance, repairs, and any HOA fees.
Borrowing leaves more money invested, but it also adds debt. Before purchase costs and taxes, your starting net worth is unchanged.
You use $500,000 and keep $1 million invested.
You have no mortgage payment. That makes your monthly budget easier to manage.
If markets fall, you have one less bill to fund from your investments.
The tradeoff is access to your money. The $500,000 is now in your home. Using it later may require selling the home or taking out a loan.
Paying cash may fit when the remaining $1 million comfortably covers your retirement needs.
But if the purchase leaves you short on emergency money, having no mortgage may come at the cost of flexibility.
You use $100,000 and keep $1.4 million invested.
That gives you more money available for future expenses and investment growth.
You also take on a $400,000 mortgage, with principal and interest payments of about $30,340 a year.
Suppose your annual budget is $60,000 before mortgage principal and interest, including the other costs of owning the home.
With this mortgage, your total becomes about $90,340 a year.
Social Security or a pension may cover part of that budget. Your investments must cover the rest.
Keeping more invested could help if markets perform well. But investment returns are uncertain, and the mortgage payment stays due even when your investments fall.
This path may fit when your income and reserves can support the mortgage through weaker markets.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
You use $250,000 and keep $1.25 million invested.
Your mortgage principal and interest payments are about $18,960 a year.
Using the same $60,000 budget, your total becomes about $78,960 a year.
You keep more money available than the cash buyer and have a smaller payment than the 20%-down buyer.
This may offer a useful balance. It still needs to work with your actual income and spending.
A mortgage adds a fixed payment to your retirement budget.
When investments fall, covering that payment can become harder.
Paying cash removes that mortgage payment. It also leaves you with a smaller investment portfolio.
Both sides belong in the comparison.
Using cash savings is different from withdrawing money from a traditional IRA.
Traditional IRA withdrawals are generally fully or partly taxable. You may need to withdraw more than $500,000 to have $500,000 available after taxes.
Selling investments in a taxable account can also create taxes on gains.
Compare the money left after the purchase, taxes, and closing costs.
For each option, ask:
A paid-off home can make retirement simpler. Keeping money invested can give you more flexibility.
The better choice is the one that leaves enough money for both the home and the life you want around it.
This example is educational, not a personalized recommendation. Mortgage payments use standard amortization calculations. No investment returns or retirement success results are projected.
Start from your current plan, change one assumption from the article, and save the version only if it is worth comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
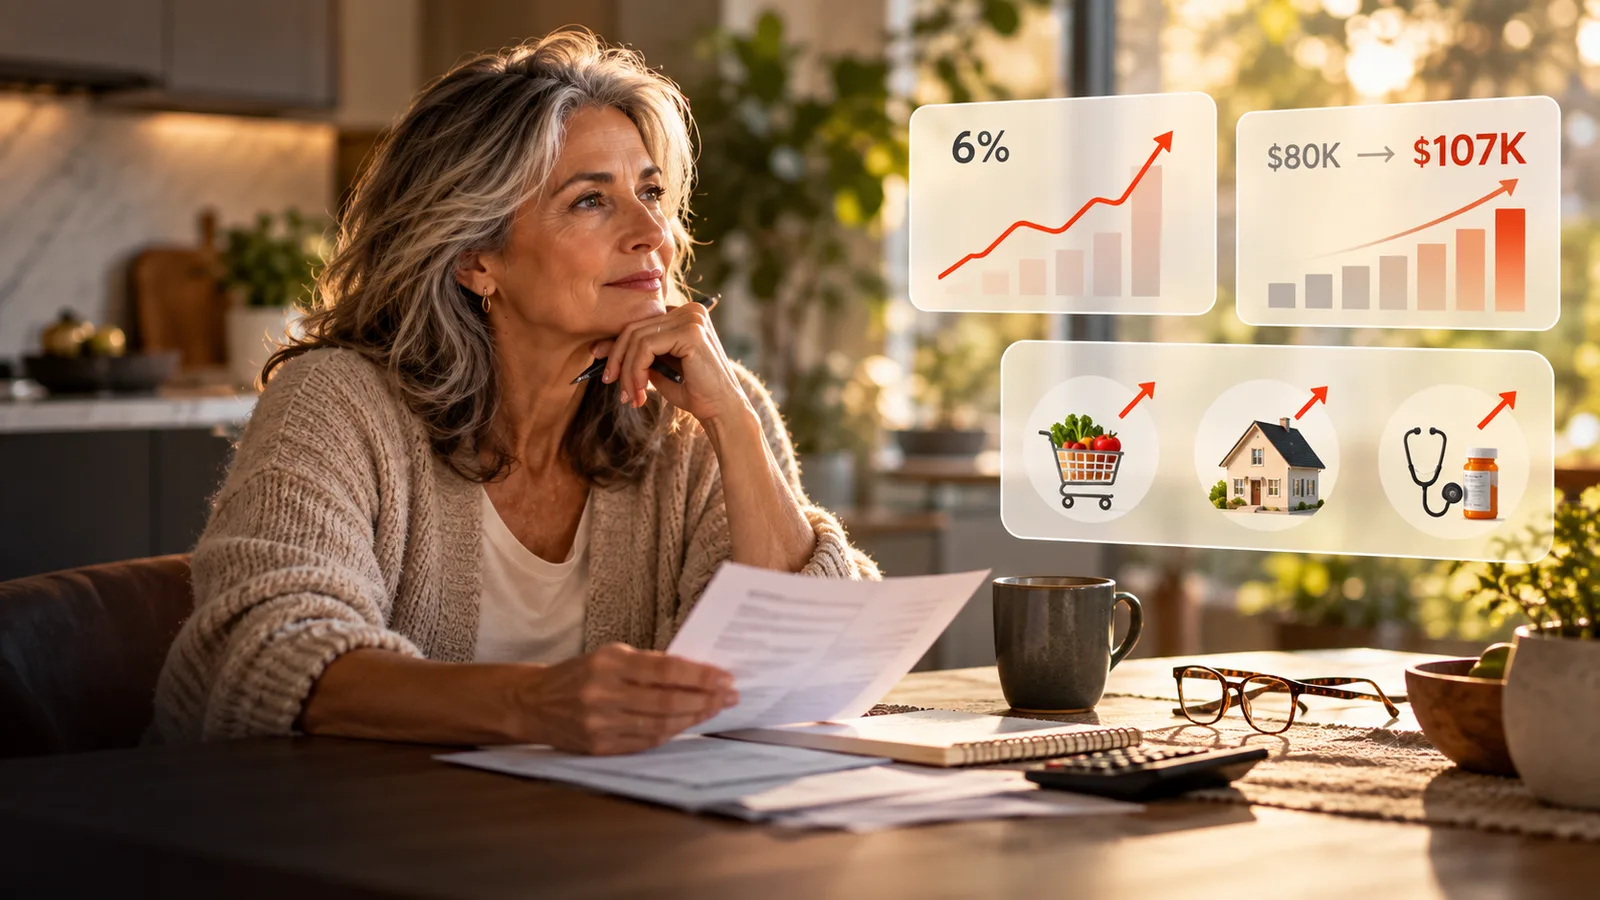
A few years of high inflation right after retirement can raise withdrawals quickly. See how maintaining your lifestyle—or temporarily adjusting it—can change the pressure on your plan.
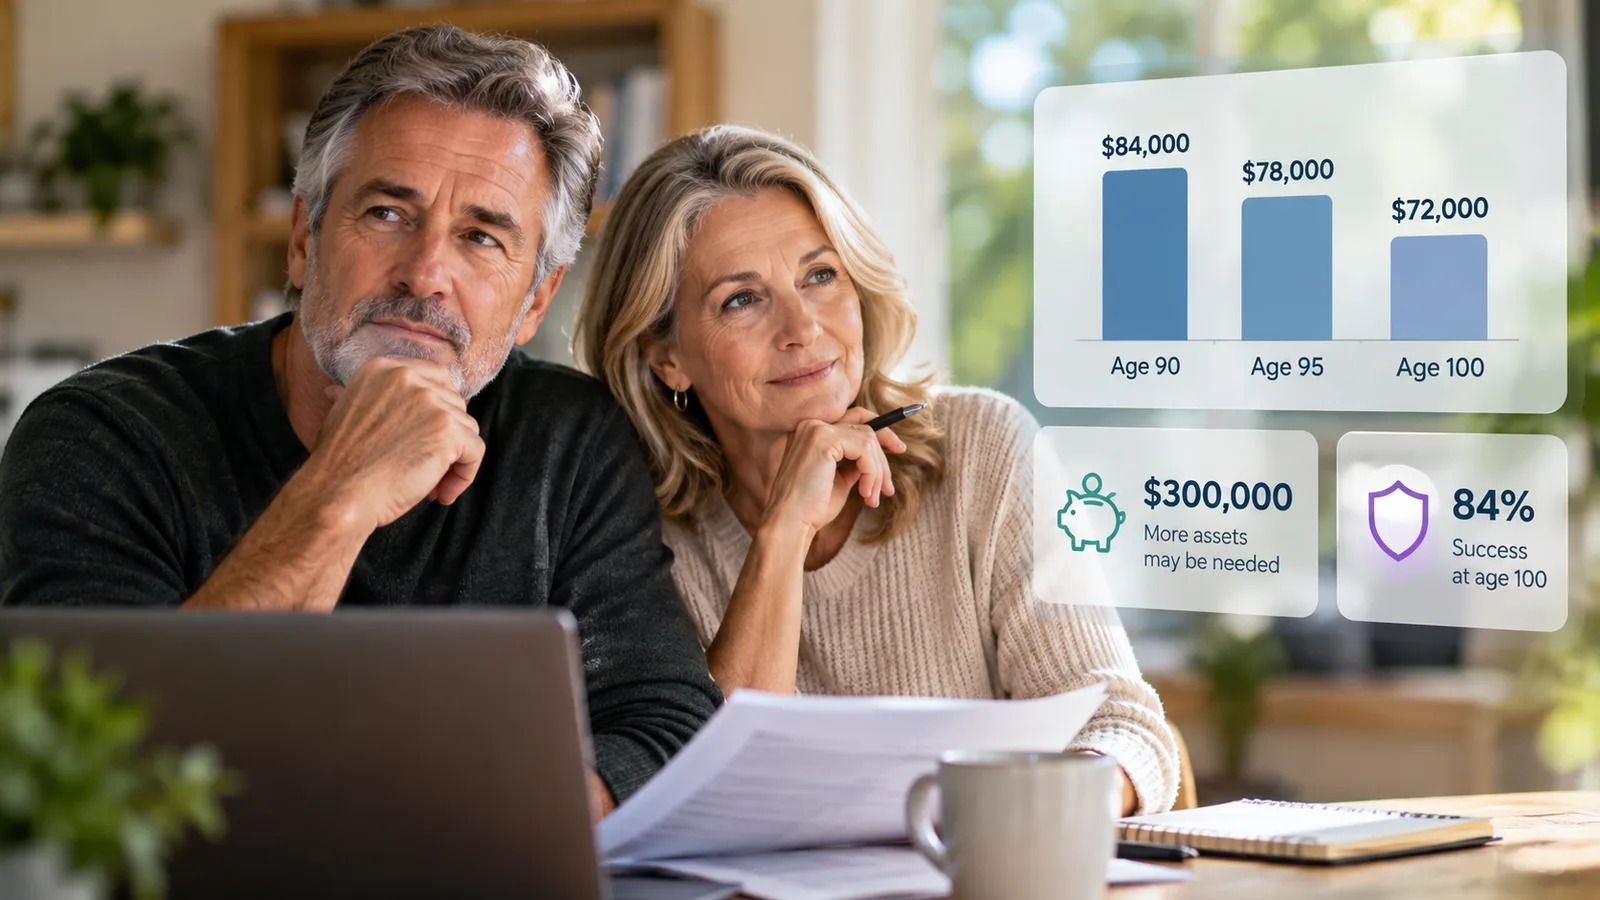
See how planning through age 90, 95, or 100 can change sustainable spending, required savings, retirement success, and the cushion left in your plan.
The market already fell. Should you keep spending, temporarily cut back, or delay one big expense? See how each response changes the tradeoff.
