7 min read • Published 3 months ago • Updated Aug 15, 2026
Load all 3 article strategies with your numbers before you decide.
Two retirees can enter retirement with the same amount saved and still face very different tax situations.
The difference may have nothing to do with investment performance.
It can come down to where the money is held.
A portfolio concentrated in a Traditional 401(k) or IRA can behave differently in retirement from one spread across Traditional, Roth, and taxable accounts. The headline balance may be identical, but the flexibility around withdrawals and taxable income can be very different.
Consider three ways the exact same retirement portfolio could be positioned:
Same savings.
Different tax flexibility.
Suppose your retirement accounts show a combined balance of $2 million.
It's tempting to think:
I have $2 million available for retirement.
But the account balance doesn't tell you how much of that money may ultimately be available to spend.
Traditional retirement accounts generally give you a tax benefit when money goes in, but withdrawals are generally taxable as ordinary income.
Qualified Roth withdrawals are generally tax-free.
Taxable brokerage accounts work differently again: withdrawing cash itself isn't necessarily taxable income. Taxes generally arise from interest, dividends, and realized gains, with the tax treatment depending on the investment and your circumstances.
So before retirement, these accounts may all look like pieces of one portfolio.
After retirement, account location starts to matter much more.
| Traditional | Roth | Taxable | |
|---|---|---|---|
| Typical contribution treatment | Often pre-tax | After-tax | After-tax |
| Retirement withdrawals | Generally taxable | Qualified withdrawals generally tax-free | Tax depends on gains and income generated |
| Required minimum distributions | Generally apply at the applicable age | Generally not for the original Roth IRA owner | No |
| Tax flexibility | Lower | Higher | Higher, but tax consequences vary |
The goal isn't to declare one account type the winner. Each can serve a different purpose.
The bigger question is what happens when your retirement savings are concentrated in one tax bucket.
This is a situation many longtime savers could recognize.
Years of contributing to a Traditional 401(k), receiving employer matches, rolling old plans into Traditional IRAs, and prioritizing tax deductions can gradually create a retirement portfolio dominated by tax-deferred money.
With the 90/5/5 portfolio, most retirement withdrawals would potentially come from accounts where distributions are taxable.
That isn't automatically bad. Traditional accounts may have provided valuable tax deductions during high-earning years.
But the concentration creates a potential constraint: there are fewer places to withdraw money without potentially increasing taxable income.
Later in retirement, required minimum distributions may also force money out of applicable Traditional accounts even when you don't need all of it for spending.
See how your current retirement balance behaves when 90% is held in Traditional accounts.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Now keep the total portfolio exactly the same.
The only change is its location:
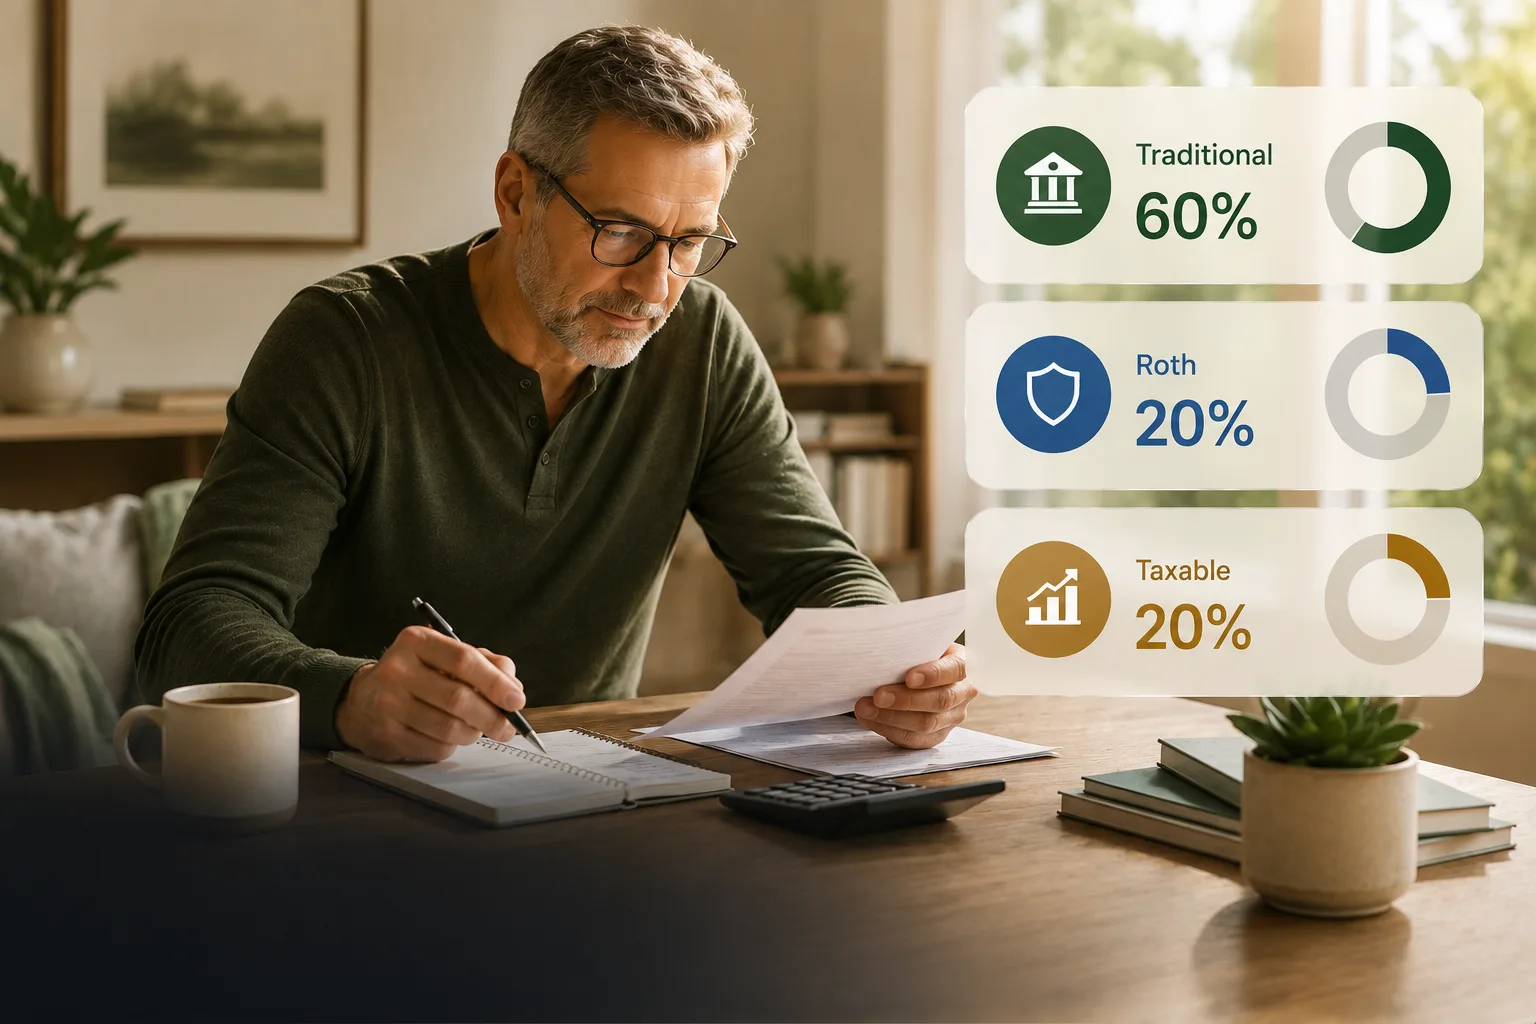
60% Traditional
20% Roth
20% Taxable
There is still substantial tax-deferred money, but now 40% of the portfolio sits outside Traditional accounts.
That creates more choices.
Imagine a year when you need additional money for a large vacation, a new car, home repairs, or another major expense.
If nearly everything is in Traditional accounts, covering that expense may require a larger taxable distribution.
With several tax buckets, you may have more options for deciding where the money comes from.
You might use Traditional withdrawals to fill lower tax brackets, taxable assets when their tax characteristics make sense, and qualified Roth withdrawals when you want additional spending without increasing taxable income from that withdrawal.
The important word is flexibility.
Tax diversification doesn't eliminate taxes. It gives you more levers for managing them.
See how the same retirement balance behaves when it is spread across Traditional, Roth, and taxable accounts.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
The third portfolio shifts even further:
35% Traditional
45% Roth
20% Taxable
Now less than half of the retirement portfolio is held in Traditional accounts.
A larger Roth balance can potentially provide a substantial pool of qualified tax-free withdrawals in retirement.
That may be useful during years when taking additional taxable income would be undesirable.
But this portfolio isn't automatically superior.
Building a large Roth balance can mean paying taxes earlier through Roth contributions or conversions. Someone in a very high tax bracket today may reasonably prefer a Traditional contribution and the current deduction.
That's why the goal shouldn't simply be:
Get as much Roth money as possible.
The better question is:
When should you pay the tax?
See how the same retirement balance behaves when a larger share is held in Roth accounts.
All article tests · No account neededOpens every article test in Lab. No account required until you save.The difference becomes clearer when the same savings are viewed through a tax-diversification lens.
Portfolio Traditional Roth Taxable Potential retirement characteristic
Traditional 90% 5% 5% Most savings Heavy potentially exposed to future taxable distributions
Tax 60% 20% 20% More withdrawal Diversified sources with different tax treatments
None of these portfolios guarantees a better retirement outcome.
Future tax rates matter. Your current tax bracket matters. State taxes matter. Withdrawal timing matters. Social Security, pensions, Medicare premiums, required distributions, and estate goals can matter too.
But the comparison reveals something a single retirement balance cannot:
How much control might you have over where retirement income comes from?
People often diversify investments across stocks, bonds, industries, and countries because the future is uncertain.
Taxes are uncertain too.
You don't know exactly what federal tax brackets will look like 15 or 25 years from now.
You don't know exactly how much taxable income you'll need in a particular retirement year.
And you don't know when a major expense might suddenly require an extra withdrawal.
Holding retirement assets across accounts with different tax treatments can create another kind of diversification:
tax diversification.
Instead of being forced to pull almost every dollar from the same type of account, you may have several sources to choose from.
That optionality can become increasingly valuable once your paycheck disappears and your portfolio becomes one of your primary sources of income.
A $1 million portfolio can be tax-diversified.
A $2 million portfolio can be tax-concentrated.
A $3 million portfolio can be either.
So as retirement gets closer, don't look only at:
How much have I saved?
Also look at:
Where have I saved it?
Your Traditional, Roth, and taxable balances aren't three unrelated numbers.
Together, they determine how much flexibility you may have when it's finally time to turn decades of savings into retirement income.
And sometimes, the mix matters almost as much as the total.
This article is for educational purposes and does not provide individualized tax or investment advice. Tax treatment depends on individual circumstances and applicable law.
Load all 3 tests from this article against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
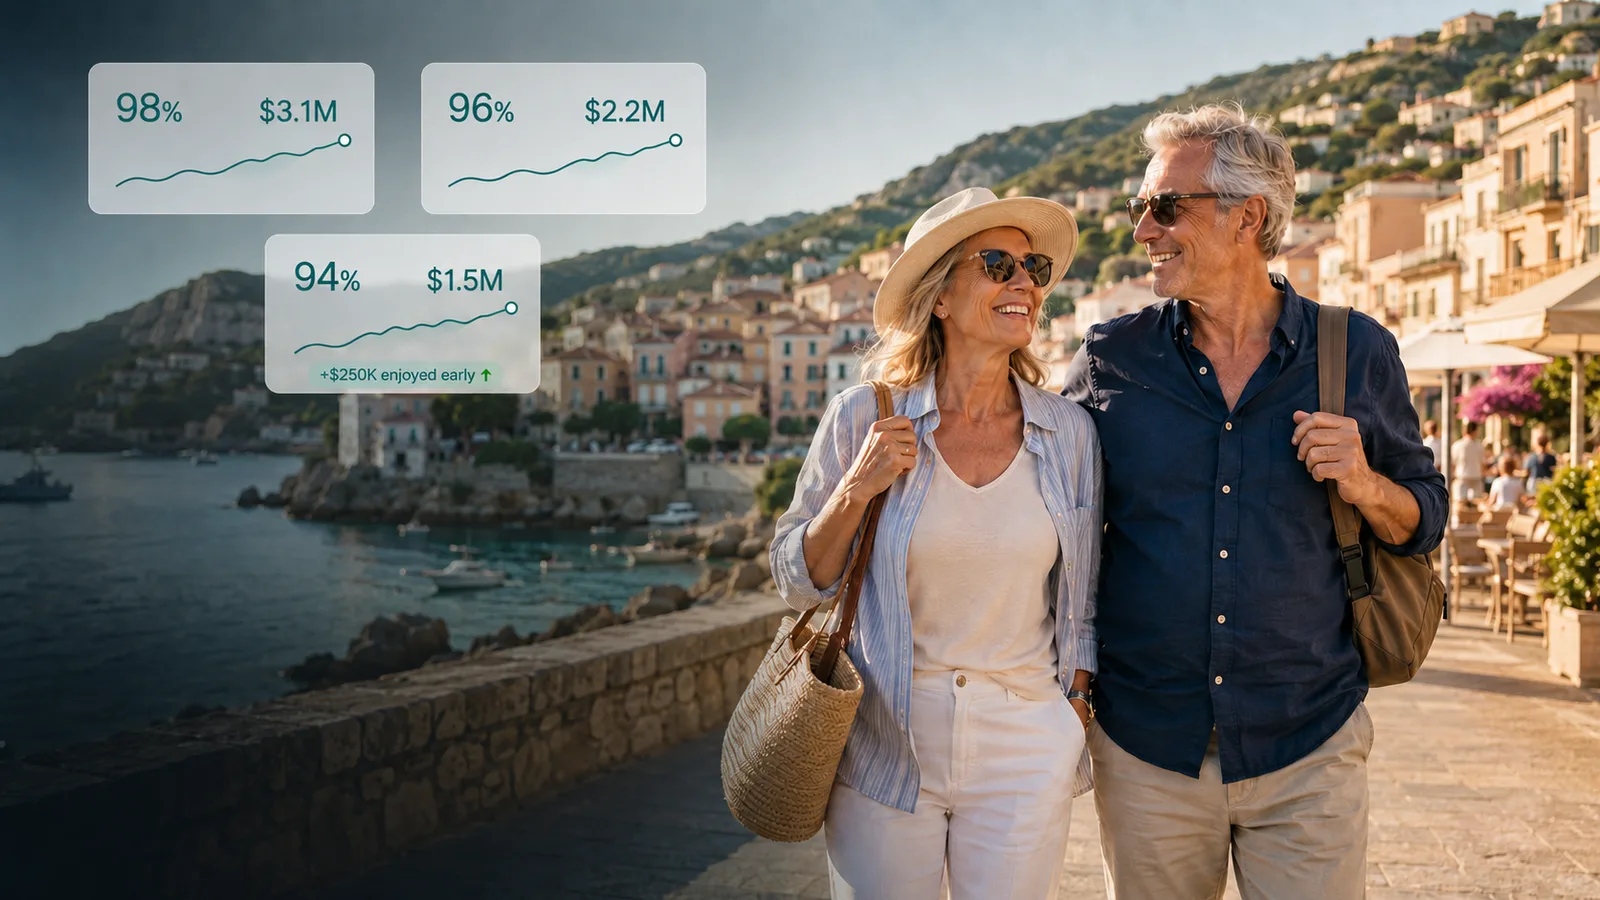
A higher retirement success rate is not automatically a better retirement. Compare preserving more with enjoying more while you are younger.
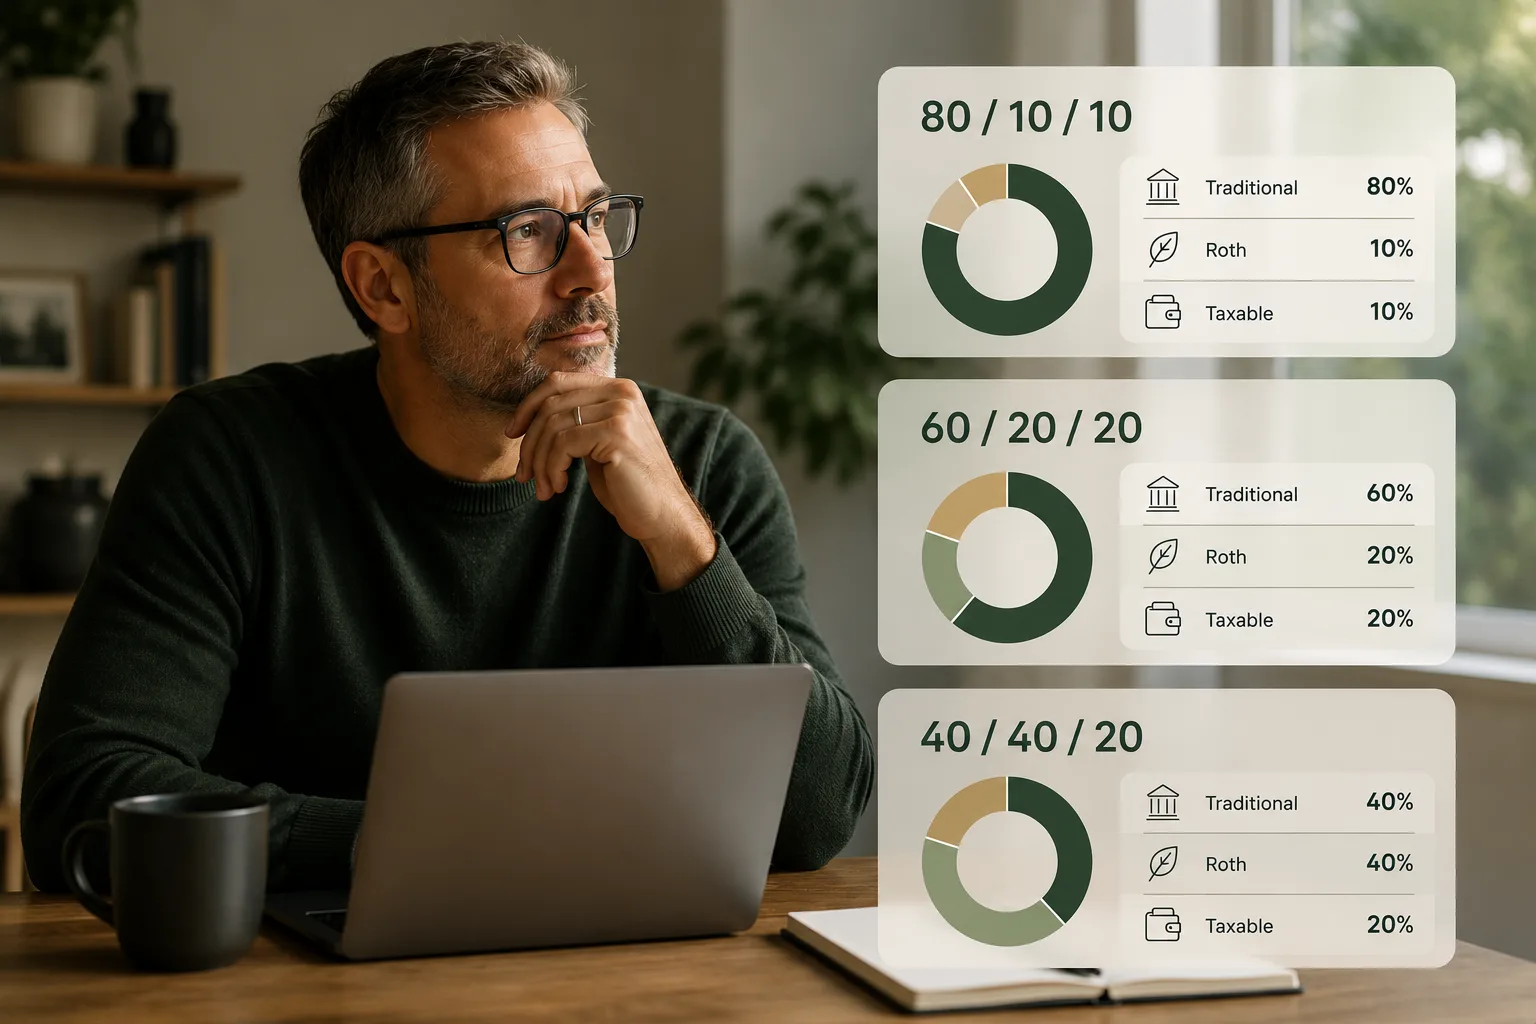
A balanced retirement account mix is not about equal percentages. Compare 80/10/10, 60/20/20, and 40/40/20 across Traditional, Roth, and taxable accounts to see how account location can change retirement flexibility.
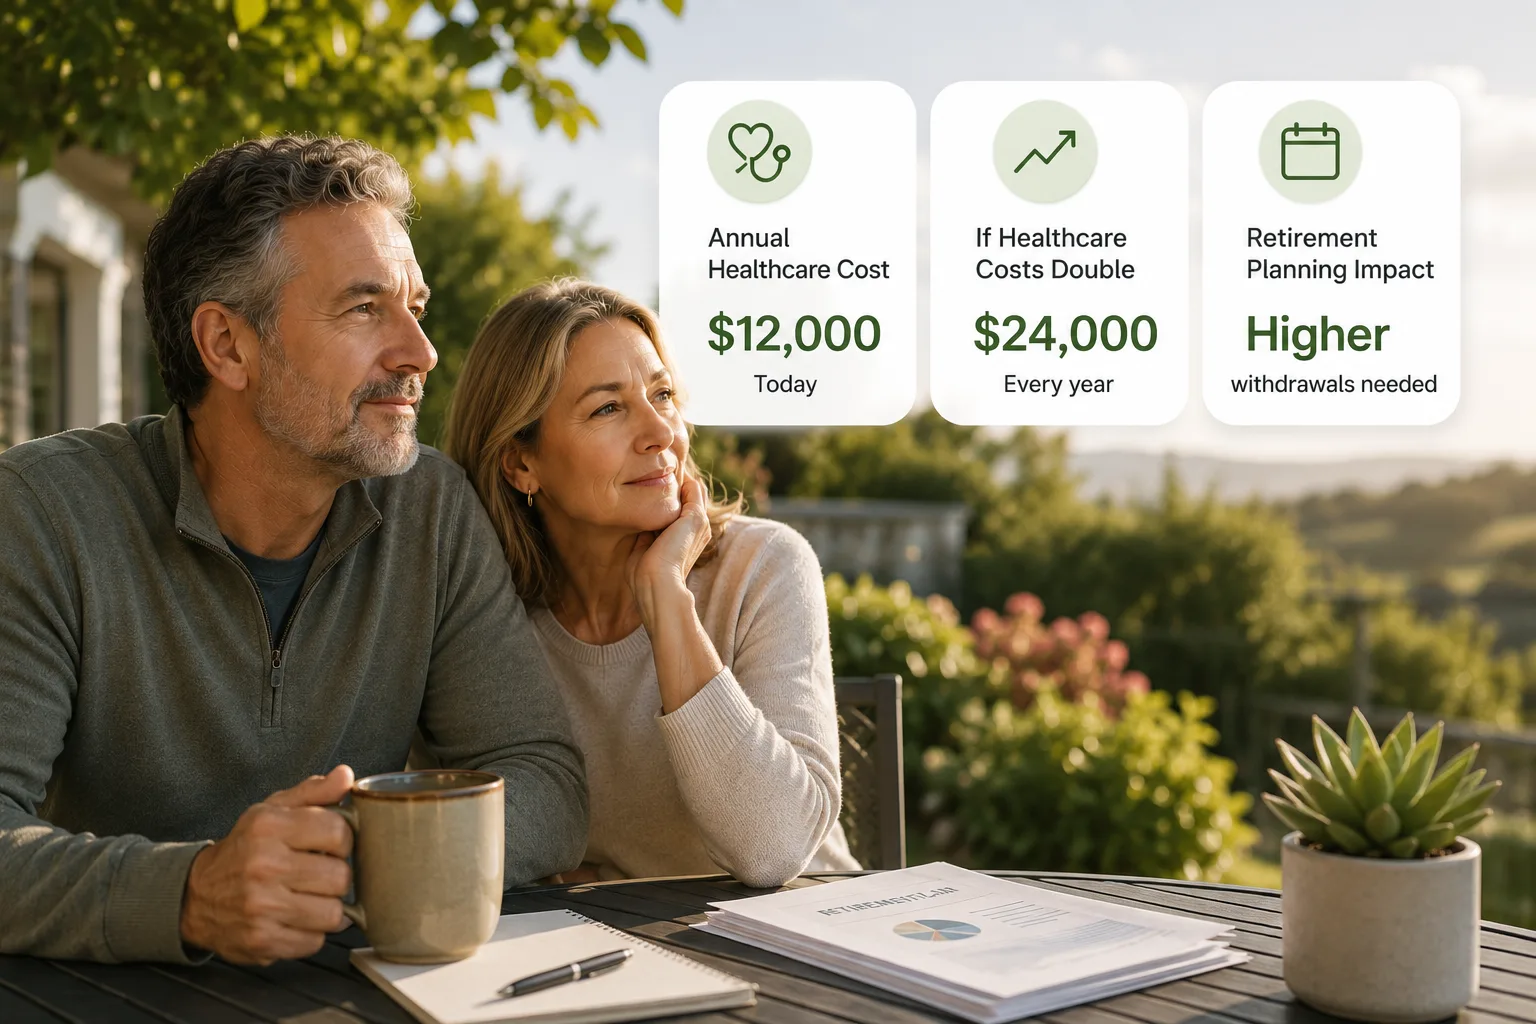
Your retirement plan may work with today's healthcare
