5 min read • Published 2 months ago
Imagine you're 67.
You have $2.4 million invested, your home is paid off, and you're spending about $90,000 a year in retirement. Your plan is strong.
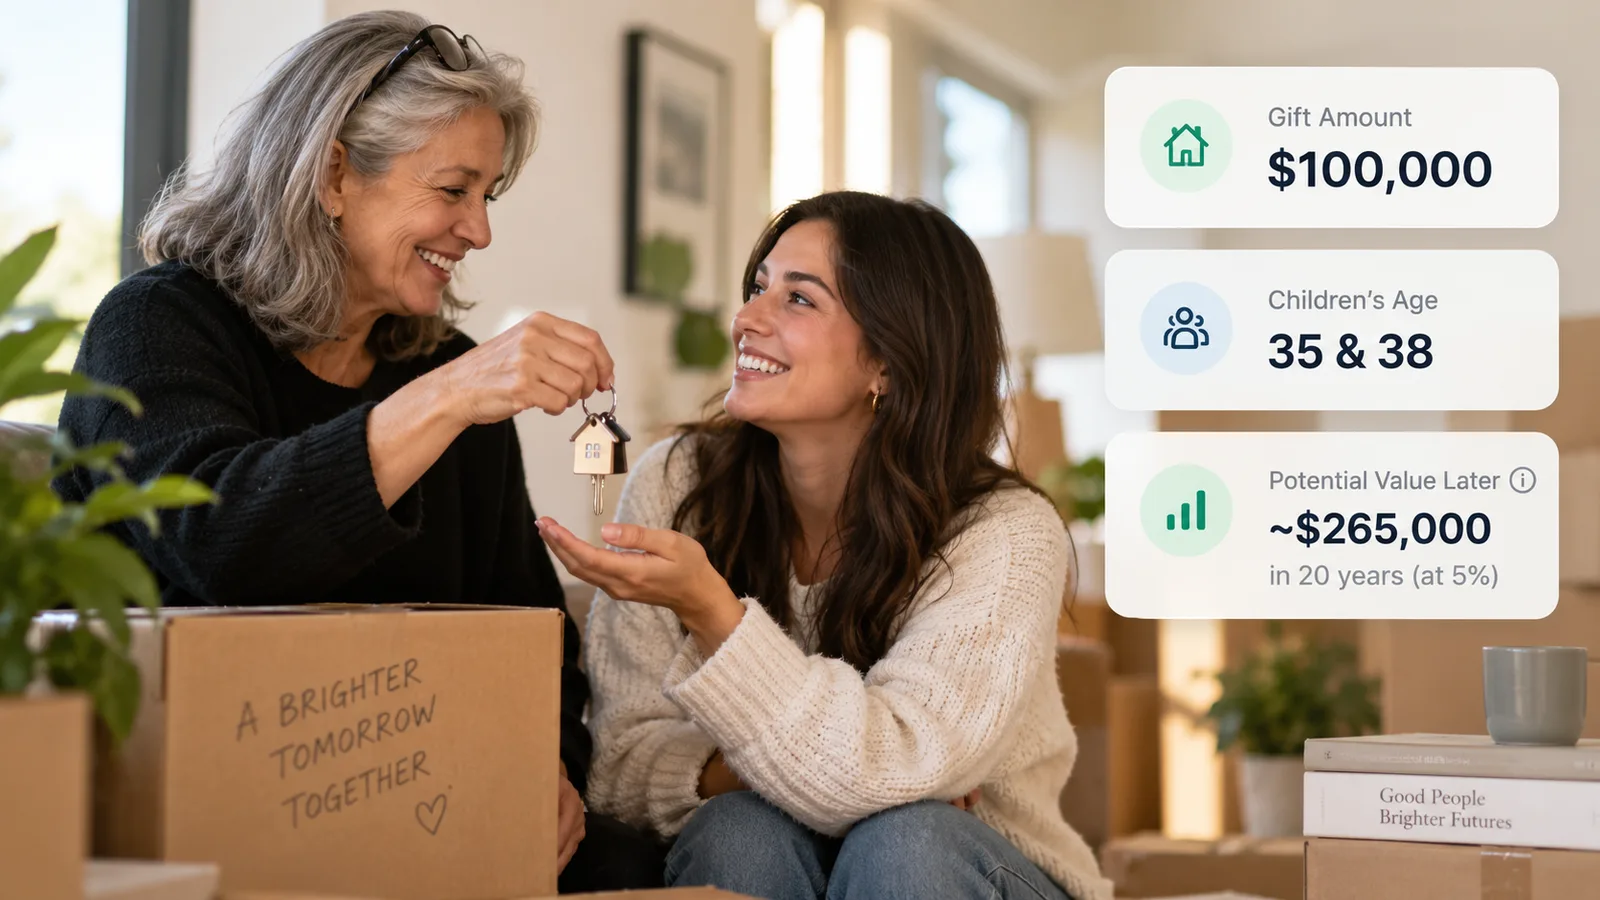
You also know you want at least $100,000 of what you've built to eventually go to your children, who are now 35 and 38.
The question isn't whether you want to help them.
It's when.
You could give them $100,000 now. You could spread it out over several years. Or you could leave the money invested and let them inherit potentially much more later.
Each path can make sense. But they solve very different problems.
You transfer $100,000 today.
Maybe it helps with a down payment on a home. Maybe it covers childcare, reduces student loans, helps fund education, or simply gives your child more room to invest for their own future.
The tradeoff is straightforward: once that $100,000 leaves your portfolio, it is no longer available for your retirement and it no longer compounds for you.
But your children receive the money while they're still in their 30s.
And that may be the biggest argument for giving earlier.
Money received at 35 could influence decisions that affect the next 20 or 30 years of someone's life.
Instead of transferring the entire amount at once, you give $20,000 per year for five years.
Your children still receive meaningful help relatively early, but you keep more of the money under your control in the meantime.
That can matter if markets fall, your spending changes, healthcare becomes more expensive, or you simply decide you aren't comfortable giving away the full amount yet.
It creates a middle path between maximizing flexibility and helping now.
| Give Now | Give Gradually | Leave It Later | |
|---|---|---|---|
| Amount intended for children | $100,000 | $100,000 total | $100,000 stays invested |
| Timing | Today | Over 5 years | Later |
| Parent flexibility | Lower | Moderate | Highest |
| Time invested before transfer | Least | Some | Most |
| Main advantage | Useful sooner | Balance | More growth potential |
There isn't an automatically correct column.
The real tradeoff is between when the money becomes useful and how long you want to keep control of it.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Now suppose you keep the $100,000 invested.
At a hypothetical 5% annual return, the difference over time becomes meaningful.
After 20 years, that original $100,000 could be worth roughly $265,000.
From a pure wealth-building perspective, waiting can look better. You maintain a larger financial cushion, keep full control of the money, and may eventually leave a substantially larger inheritance.
But there's another side to that math.
If your child is 35 today, they'll be around 55 in 20 years.
Their mortgage may already be much smaller. Their children may be grown. Their biggest childcare expenses may be behind them. They may even be approaching retirement themselves.
The inheritance could be larger precisely because it arrives after some of the years when the money may have been most useful.
The amount matters, but so does the timing.
Give it now: The money could help with a home, childcare, debt, education or investing today.
Give it gradually: Your children get help during the next several years while you preserve more flexibility.
Leave it later: The money gets more time to grow, but it may arrive during a completely different stage of their lives.
Legacy planning often starts with:
How much can I leave behind?
But once your own retirement is comfortably funded, there may be a more useful question:
When would this money matter most to the people I'm leaving it to?
For some families, the answer will absolutely be later. Keeping the money may provide important protection against healthcare expenses, long-term care, market downturns, or simply the uncertainty of a long retirement.
For others, maximizing the eventual inheritance may not be the goal.
Maybe $100,000 helps a child buy a home at 35 instead of 45.
Maybe it lets them eliminate debt.
Maybe it reduces the pressure of childcare during the most expensive years of raising a family.
Maybe they invest some of it themselves and get decades of compounding.
And maybe part of the value is something a larger inheritance later can't provide:
You get to see what the money made possible.
Sometimes the most valuable inheritance isn't the largest one.
It's the one that arrives at the right time.
Large financial gifts can have tax, estate-planning and other consequences. Consider reviewing a significant transfer with the appropriate tax, legal or financial professional before acting.
Start from your current plan, change one assumption from the article, and save the version only if it is worth comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
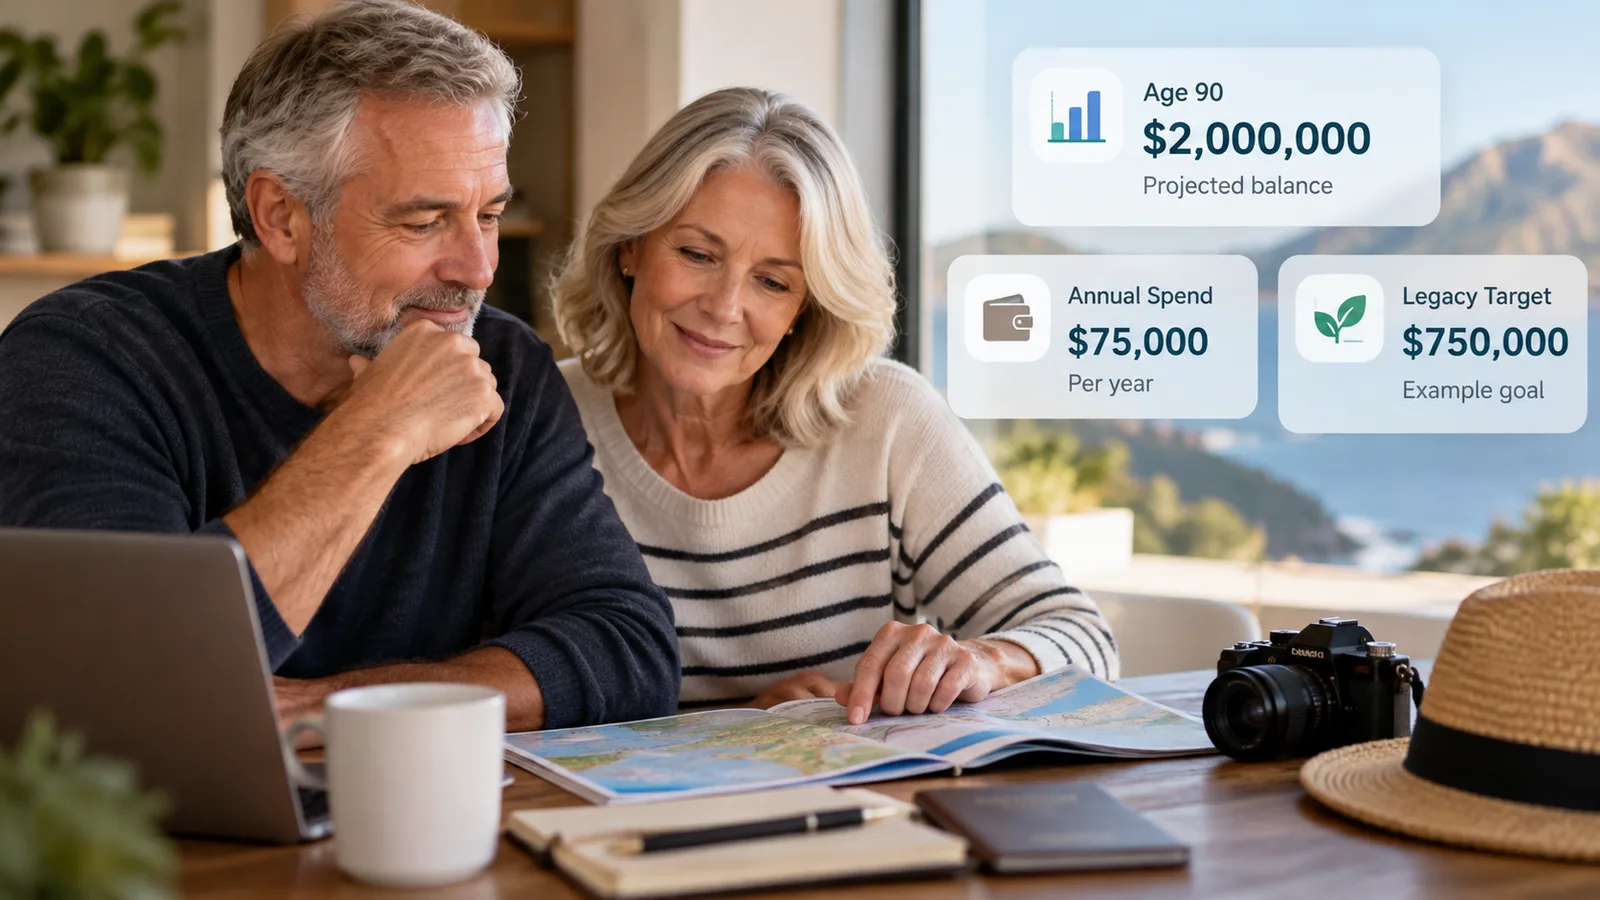
A strong retirement plan can leave you with millions late in life. The next question is how much you actually want to preserve — and how much you want to use.
Twenty-five years after September 11, we remember the 2,977 lives lost, the courage shown that day, and the families and communities forever changed.
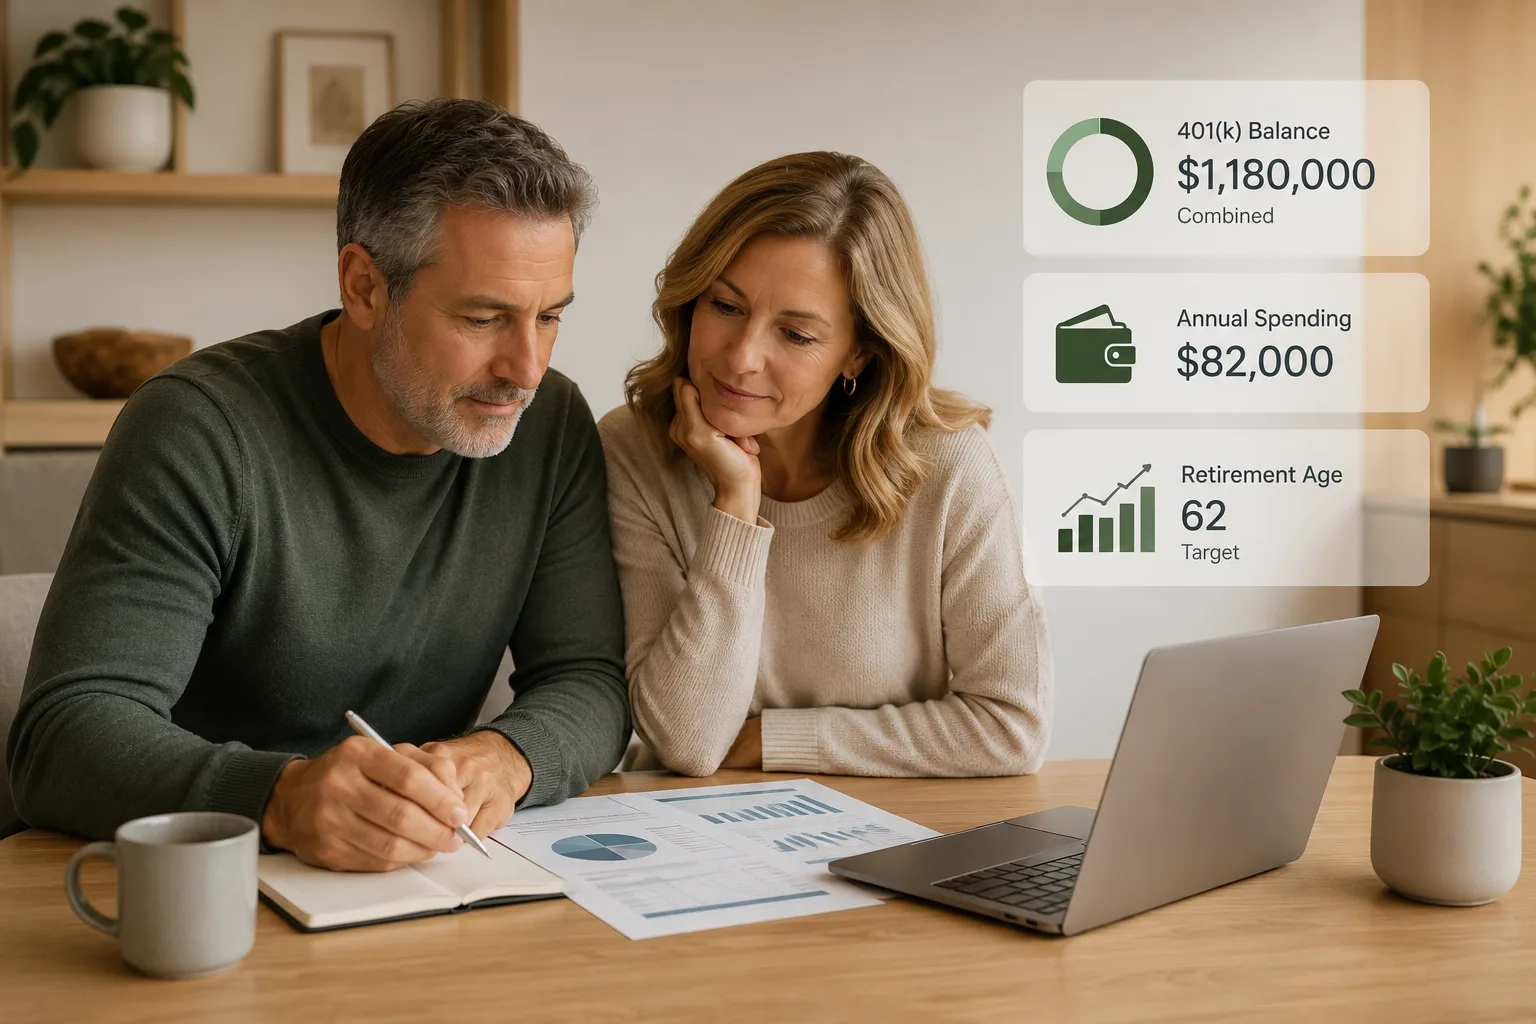
See estimated 401(k) balances by spending level, understand what changes the number, and compare retirement strategies with Nestly Lab.
