5 min read • Published 5 months ago • Updated Jun 24, 2026
Load this article strategy with your numbers before you decide.
Many parents spend decades helping their children.
Then retirement gets closer, and the question changes:
Should you continue helping adult children financially if it affects your retirement?
This is one of the most emotional retirement decisions families face.
The issue is not whether you love your children.
The issue is whether financial support today could create financial stress later.
Common forms of support include:
Helping can be meaningful.
But it should be measured against your own retirement security.
Many parents think:
"It's only a little help."
But recurring support can become a significant retirement tradeoff.
Monthly Support: $500

Duration: 10 Years

Total Support: $60,000
Now add:
Wedding Support: $25,000

Down Payment Help: $50,000
Total:
$135,000
That money may be given with love.
But it still leaves the retirement plan.
Imagine a parent with:
Retirement Savings

$1,000,000
| Scenario | Financial Help Given | Remaining Portfolio |
|---|---|---|
| No Support | $0 | $1,000,000 |
| Limited Support | $25,000 | $975,000 |
| Moderate Support | $75,000 | $925,000 |
| Significant Support | $150,000 | $850,000 |
That difference may affect:
This doesn't mean parents should never help.
It means the tradeoff should be understood.
Examples:
Temporary support often serves an important purpose.
Examples:
One-time support is often easier to plan for than ongoing support.
Helping should not require:
If helping jeopardizes your future, the cost may be too high.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
If support requires:
It may be time to reconsider.
Retirement assets are difficult to rebuild.
If helping means:
Retire at 67

instead of

Retire at 62
That is a meaningful tradeoff.
It may still be worth it—but it should be intentional.
The greatest risk is unlimited support.
Examples:
Support without boundaries can become permanent.
Parents continue covering major expenses.
Pros:
Cons:
Help only during genuine crises.
Pros:
Cons:
Child Saves $1

Parent Contributes $1
Pros:
Provide support with structured repayment.
Pros:
Cons:
Retirement fully funded

Then financial gifts
Pros:
Instead of asking:
Can I afford to help my child?
Ask:
Can I help my child without becoming financially dependent on them later?
That question changes the entire conversation.
One of the greatest gifts parents can give their children is:
Not becoming
a financial burden later.
| Support Level | Retirement Impact |
|---|---|
| No Support | Maximum flexibility |
| $25,000 | Small impact |
| $75,000 | Moderate impact |
| $150,000+ | Significant tradeoff |
With Nestly Lab, you can compare:
AI then ranks the outcomes and highlights the tradeoffs.
Because the goal isn't to automatically say yes or no.
It's to understand the long-term impact before making the decision.
Model what happens to your plan if you reduce contributions to help an adult child financially.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Load "Redirect $500/mo to Support Your Adult Child" against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
Should you save for your child's college or your own retirement first? Learn how to compare the tradeoffs and build a balanced family money plan.
Many adults are helping aging parents and adult children while trying to prepare for retirement. Learn how family support can affect retirement readiness and how to manage the tradeoffs.
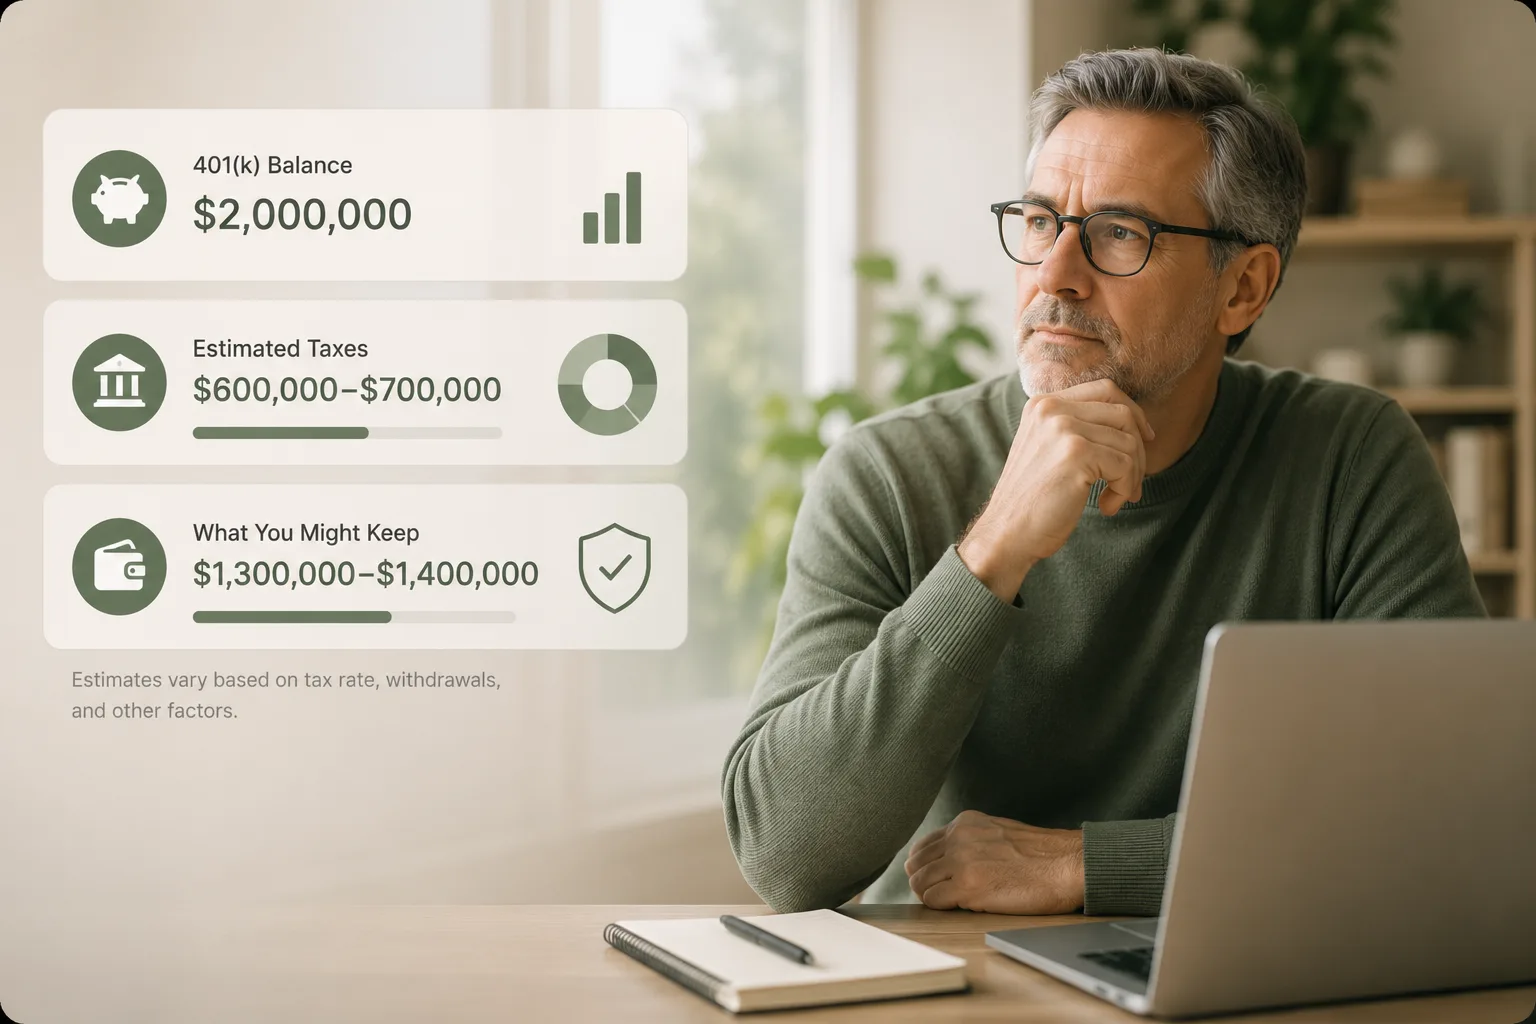
Two retirees can both have $2 million and still have very different amounts available to spend. See why Traditional, Roth, and taxable account balances matter in retirement.
