10 min read • Published about 2 months ago
You retire at 65 with $1.5 million.
Your plan calls for about $75,000 a year of spending.
Then, early in retirement, the market has a bad year.
Your portfolio falls significantly.
Now the question changes.
It is no longer:
What happens if the market crashes?
The market already fell.
The real question is:
Should you change what you do next?
Cutting spending could give the portfolio more room to recover.
But retirement is also something you planned to enjoy.
So instead of simply asking whether spending less helps, there is a more useful question:
How much lifestyle would you actually need to give up — and for how long — to materially improve the plan?
For this comparison, assume the market behaves exactly the same in every path.
The retiree starts with:
The market decline does not change between paths.
Only the retiree's response changes.
| Future Path | What changes |
|---|---|
| Stay the Course | Continue spending $75,000 a year |
| Temporarily Cut Back | Spend $65,000 for two years, then return to $75,000 |
| Delay One Big Expense | Keep normal spending but postpone a roughly $45,000 major purchase |
That distinction matters.
We are not giving one path a better market recovery than another.
We are asking:
When markets are identical, how much difference can a relatively small behavior change make?
The first response is also the simplest:
Change nothing.
Continue spending the planned $75,000 per year.
That may feel uncomfortable after watching the portfolio fall, but retirement plans are built around the reality that markets move up and down.
One bad year does not automatically mean the plan needs to change.
The tradeoff is that withdrawals are now coming from a smaller portfolio.
When money is withdrawn during a downturn, those dollars are no longer invested if markets later recover.
Staying the course protects the lifestyle you planned.
You do not cancel trips, reduce everyday spending, or put major plans on hold simply because the market had a bad year.
But you also give the portfolio no temporary relief.
That is the tradeoff.
Now suppose the retiree makes a small temporary adjustment.
Instead of spending $75,000, they spend $65,000 per year for two years.
Then they return to their normal $75,000 lifestyle.
That means the total spending reduction is:
$20,000 over two years.
This is important because it is not the same as deciding to permanently live on less.
The retiree is not rewriting retirement.
They are giving the portfolio a short period with slightly smaller withdrawals.
That could mean:
The point is not to make retirement feel restrictive.
It is to ask whether a relatively small, temporary adjustment can make a meaningful difference.
The obvious answer is that spending less leaves more money invested.
But that alone is not very useful.
The better question is:
Does giving up $20,000 over two years improve the plan enough to be worth it?
That is where the comparison becomes interesting.
If the change barely affects long-term resilience, the sacrifice may not accomplish very much.
If the temporary cut meaningfully improves the plan, then the retiree knows the adjustment does not need to last forever.
That makes another metric especially valuable:
How many years until normal spending returns?
In this path, the answer is clear:
Two years.
After that, the retiree returns to the original $75,000 spending target.
The third path takes a different approach.
Instead of cutting everyday spending, the retiree keeps the normal $75,000 annual lifestyle.
But suppose there is also a $45,000 one-time expense planned shortly after retirement.
Maybe it is:
The retiree does not cancel it.
They delay it.
Everyday retirement stays mostly unchanged.
Groceries stay the same.
Restaurants stay the same.
Normal travel stays the same.
The retiree simply decides:
This one large expense can wait.
That distinction matters.
For some people, postponing one major purchase may feel much easier than trimming thousands of dollars from everyday life.
It also keeps more money invested during a period when the portfolio has already fallen.
If markets recover before the expense is eventually taken, the withdrawal may come from a stronger portfolio.
Recovery, however, is not guaranteed to happen on a particular schedule.
That is why this path should not be framed as:
Wait two years and everything will be fine.
Instead, the question is:
Can delaying one flexible expense create enough breathing room without changing the rest of retirement?
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
The important thing about these three paths is that the market does not change.
Every path experiences the same decline.
Every path experiences the same assumed recovery.
Only the retiree's behavior changes.
| Future Path | Annual lifestyle | Temporary sacrifice |
|---|---|---|
| Stay the Course | Keep spending $75,000 | None |
| Temporarily Cut Back | Spend $65,000 for two years, then $75,000 | $20,000 total |
| Delay One Big Expense | Keep spending $75,000 | Postpone a $45,000 purchase |
This is what makes the comparison useful.
The question is not:
Who gets the better market?
It is:
What does each response buy you?
If the only metric were ending portfolio value, the answer would be predictable.
Spending less generally leaves more money behind.
But retirement planning is not a competition to finish with the largest possible portfolio.
The better comparison looks at both financial resilience and lifestyle cost.
| Metric | Why it matters |
|---|---|
| Success | Does the response materially strengthen the retirement plan? |
| Portfolio recovery | How does the portfolio rebuild after the decline? |
| Total spending sacrificed | How much lifestyle was actually given up? |
| Ending portfolio | How much remains later in retirement? |
| Years until normal spending returns | How long does the adjustment affect everyday life? |
That last metric is especially important.
Imagine two choices.
One improves the plan slightly but requires spending less for several years.
Another creates a similar improvement by delaying one major purchase.
They may look similar on a financial projection.
They may feel completely different in real life.
That is the part a simple success percentage cannot show.
The better question is not simply:
Which path produces the highest Success?
It is:
How much lifestyle do I actually have to give up — and for how long — to materially improve the plan?
Probably not.
Markets will have bad years during a long retirement.
If every decline leads to immediate lifestyle cuts, retirement can slowly turn into an exercise in watching account balances instead of living the plan.
That is not the goal.
The better approach is to understand whether the decline is large enough — and the plan sensitive enough — that a temporary adjustment could actually matter.
Sometimes the right response may be to change nothing.
Sometimes a short spending reduction may create useful breathing room.
Sometimes delaying one large purchase may accomplish nearly the same thing without changing everyday life.
The point is not to react automatically.
It is to understand the tradeoff before reacting.
One of the biggest differences between these paths is whether the change is permanent.
A permanent spending reduction says:
My retirement lifestyle needs to be smaller from now on.
A flexible adjustment says:
I am temporarily changing when I spend some of this money.
Those are very different decisions.
For many retirees, flexibility may come from expenses that are easier to move:
That creates another way to think about retirement spending.
Not every dollar has to be equally flexible.
Housing, healthcare, groceries, and other essential costs may be difficult to reduce.
A large trip or home project may be much easier to delay.
That distinction can matter when the market has a bad year.
A market decline alone does not automatically mean spending should change.
If the plan remains strong after the decline, cutting spending may simply create a larger ending portfolio without meaningfully improving the retiree's ability to fund retirement.
That is why Success should not be viewed in isolation.
Suppose staying the course still produces a strong plan.
Then the question becomes:
How much additional protection do I actually gain by giving something up today?
If a $20,000 temporary spending reduction creates only a very small improvement, the retiree may decide the lifestyle sacrifice is not especially valuable.
If the same adjustment materially improves resilience, the tradeoff looks different.
The size of the benefit matters.
So does the size of the sacrifice.
The instinct after a large market decline is often:
I should spend less.
But that skips an important step.
The better questions are:
Those questions turn a vague fear about markets into a decision that can actually be compared.
A bad market year does not automatically mean retirement spending needs to permanently change.
The useful question is not:
Should I spend less?
It is:
What is the smallest change that meaningfully improves the plan?
For one retiree, that might mean continuing exactly as planned.
For another, it might mean spending $10,000 less for two years.
For someone else, it might mean keeping everyday life unchanged and delaying one $45,000 purchase.
The market can be identical in every path.
What changes is the response.
And that is the real value of comparing Future Paths:
not just seeing which choice leaves the most money, but understanding what each choice asks you to give up to get there.
Start from your current plan, change one assumption from the article, and save the version only if it is worth comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
A few years of high inflation right after retirement can raise withdrawals quickly. See how maintaining your lifestyle—or temporarily adjusting it—can change the pressure on your plan.
Compare paying cash, putting 50% down, and putting 20% down on a retirement home. See how each choice changes your investments and monthly bills.
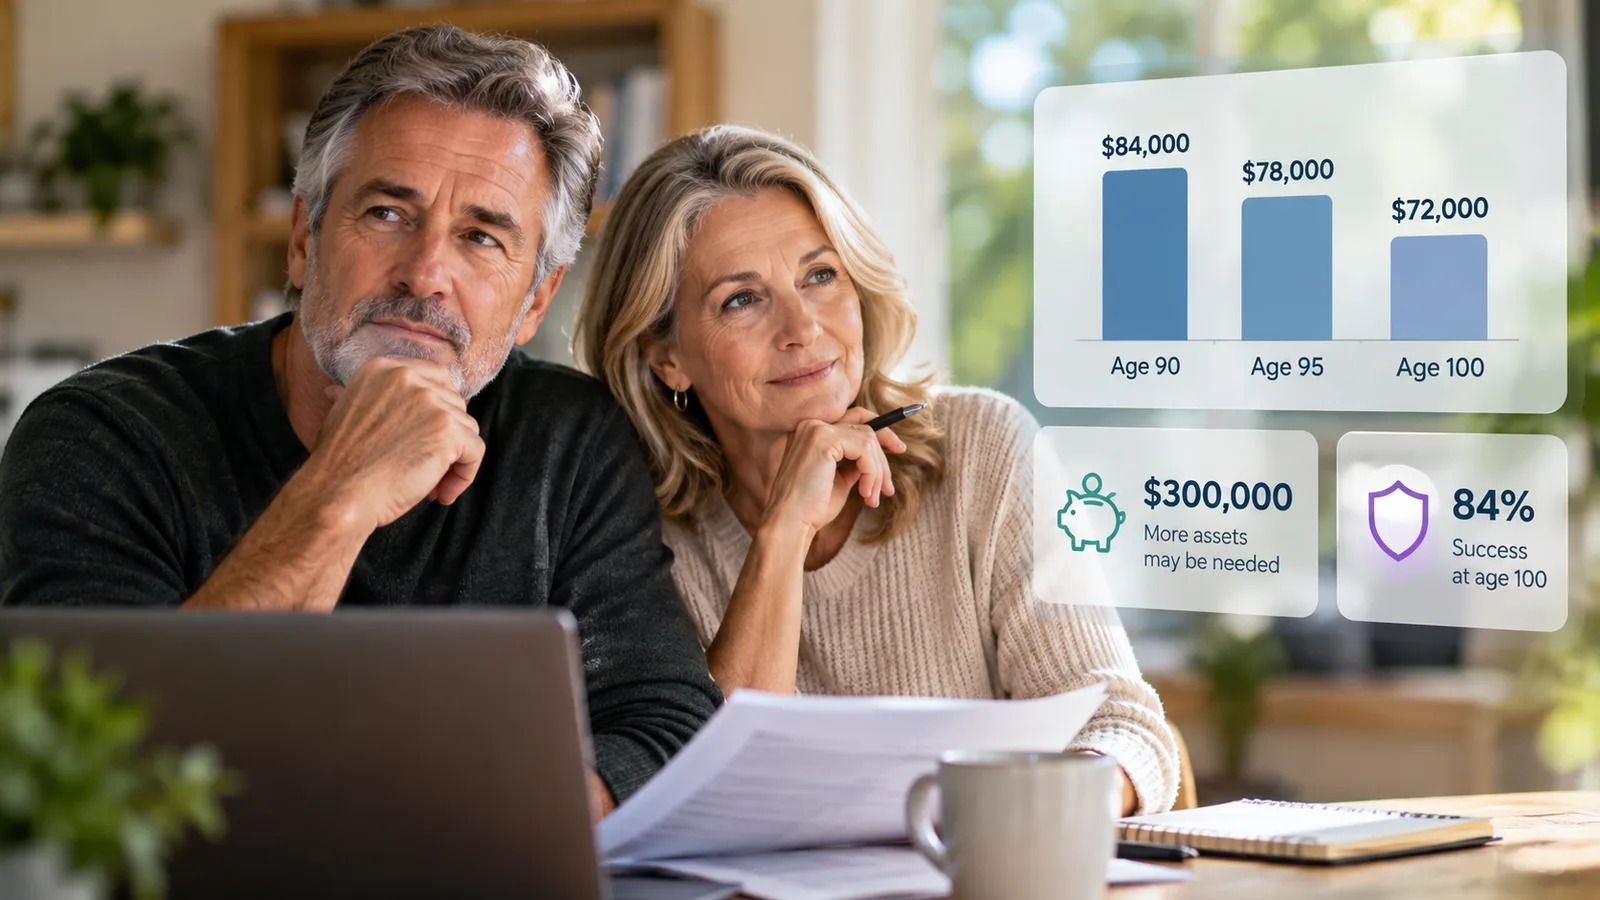
See how planning through age 90, 95, or 100 can change sustainable spending, required savings, retirement success, and the cushion left in your plan.
