7 min read • Published 3 months ago • Updated Sep 1, 2026
Load this article strategy with your numbers before you decide.
Retirement planning often teaches us to optimize for one thing: make the money last.
That matters. But once a plan already has a high probability of success, another question becomes just as important:
Are you actually using enough of the money you spent decades saving?
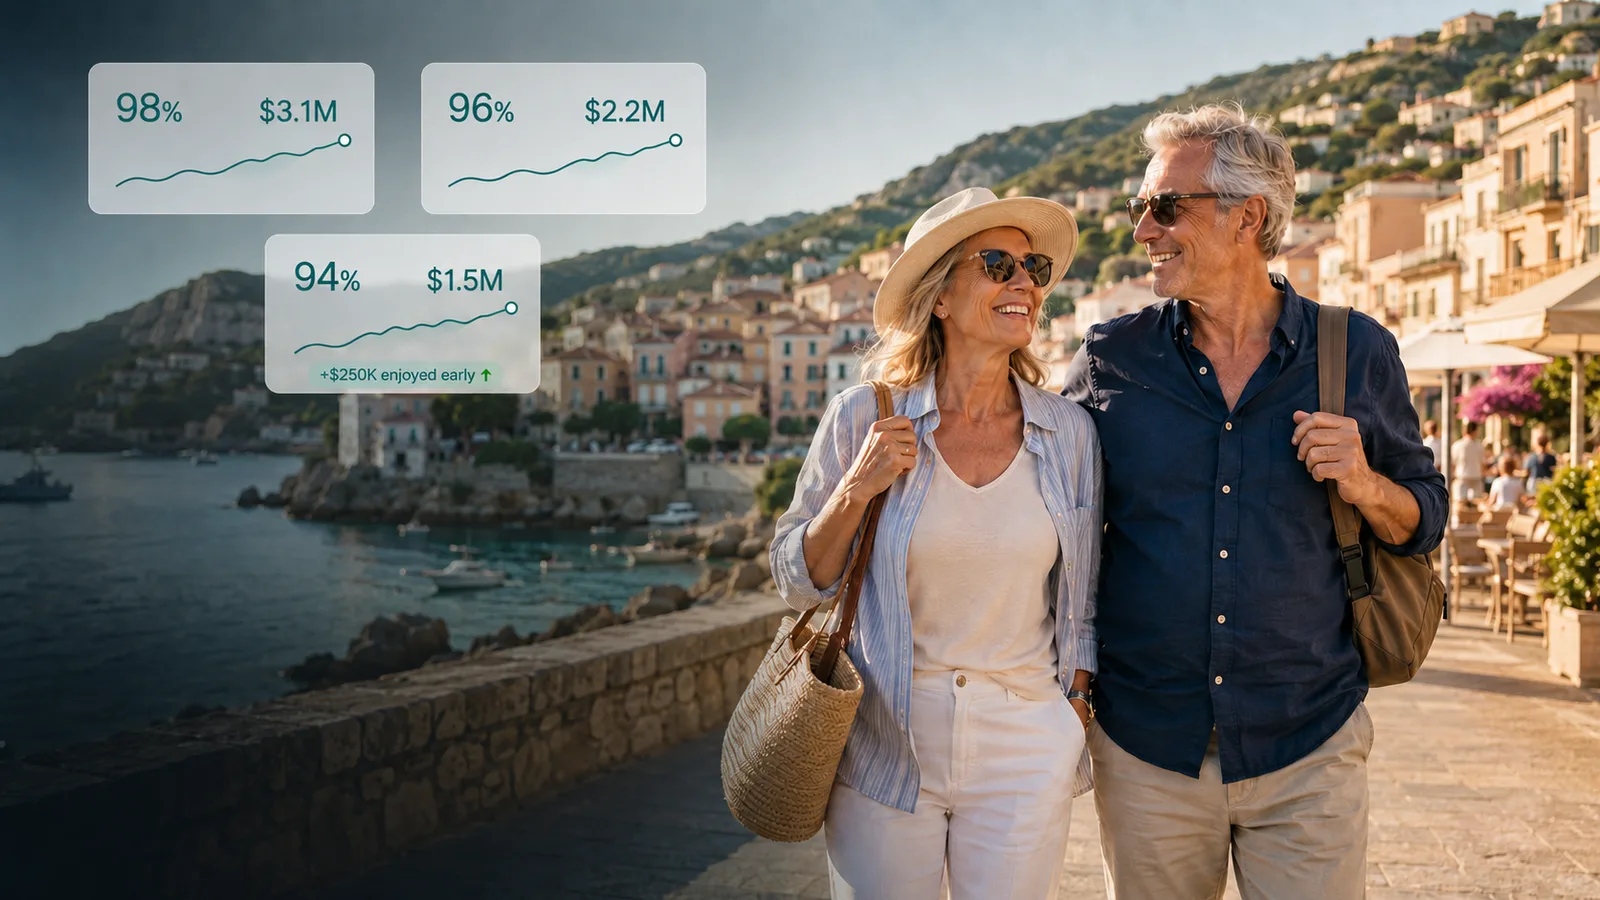
Imagine three retirement paths starting from the same financial position.
| Path | Success | Median ending assets | Spending approach |
|---|---|---|---|
| Conservative | 98% | $3.1M | Preserve more |
| Level | 96% | $2.2M | Keep spending steady |
| Enjoy More Early | 94% | $1.5M | Spend an extra $250K from ages 62–72 |
These figures are illustrative. They are designed to show the decision, not recommend a specific spending amount or predict anyone’s results.
At first glance, the answer might seem obvious: take the 98% plan.
But is it automatically the best retirement?
Not necessarily.
A retirement success percentage answers an important question:
How resilient is this plan across many possible futures?
It does not answer a different question:
Which retirement would you rather live?
The Conservative path has the highest success rate and leaves the largest projected portfolio.
The Enjoy More Early path gives up some of that cushion. In exchange, the retiree spends an additional $250,000 during the first decade of retirement—about $25,000 more per year from ages 62 through 72.
That money could mean more travel, longer trips, hobbies, experiences with family, home improvements, charitable giving, or simply having more freedom to say yes.
The ending balance is smaller partly because the retiree intentionally used more of the money.
That isn’t necessarily a planning failure. It may be the plan working exactly as intended.
Retirement does not necessarily look the same at 65, 75, and 85.
Your first decade may be when you have the strongest combination of:
That does not mean spending always declines with age or that everyone should front-load retirement spending.
It means when you spend money can matter just as much as how much you spend.
Imagine postponing a major trip every year because you want your retirement success rate to remain as close to 100% as possible.
At 68, the money is available.
At 78, the money may still be available—but the opportunity may not be the same.
That is the tradeoff retirement projections can hide.
Each path is optimizing for something different.
98% success
$3.1M median ending assets
This retiree prioritizes maximum financial cushion.
That could be completely reasonable. They may want substantial protection against a long retirement, poor markets, unexpected expenses, or future healthcare needs. Leaving money to children or charities may also be an important goal.
For this person, ending retirement with significant assets is not accidental. It is part of the plan.
96% success
$2.2M median ending assets
This path takes a more balanced approach.
The retiree maintains a relatively consistent lifestyle while preserving substantial flexibility for later. There is less financial cushion than in the Conservative path, but also more room to spend along the way.
For many retirees, this middle ground may feel comfortable.
94% success
$1.5M median ending assets
+$250K spent from ages 62–72
This retiree makes a deliberate choice: use more money while younger.
The projected ending portfolio is smaller, and the success rate drops several percentage points. But the retiree receives something in return: more spending power during the period when they may have the greatest ability to use it.
The important question isn’t whether $1.5 million is worse than $3.1 million.
It is:
What did the retiree receive in exchange for that difference?
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
It is easy to treat retirement success like a test.
98% feels better than 96%. And 96% feels better than 94%.
Mathematically, the higher number does represent greater projected resilience. But retirement planning becomes more useful when success is treated as a guardrail rather than a score you endlessly maximize.
Suppose increasing retirement spending moves a plan from 98% to 94%.
That deserves attention, but it does not automatically tell you not to do it.
Instead, it gives you the information needed to make a decision:
Is the additional lifestyle worth the reduction in financial cushion?
For one household, the answer may be no. For another, it may be yes.
The example above front-loads an extra $250,000 from ages 62–72. The current Lab test is broader: it raises your existing retirement spending target by 20% throughout retirement so you can see how higher spending affects your own plan.
See how spending 20% more than your current retirement target changes your plan.
All article tests · No account neededOpens every article test in Lab. No account required until you save.There isn’t one definition of a successful retirement.
You might care most about:
Those priorities can lead two households with nearly identical finances toward very different plans.
And both plans can be rational.
Retirement planning naturally focuses on running out of money. That is an important risk.
But there is another possibility that receives less attention:
Repeatedly delaying meaningful spending even when your plan could support it.
You might reach your 80s with far more money than expected and realize that you protected against every imaginable future while consistently postponing the life the money was supposed to support.
The goal is not to swing to the opposite extreme and spend recklessly. It is to understand the tradeoff.
A strong retirement plan should tell you not only when spending becomes dangerous, but also when you may have room to enjoy more.
Maybe.
If additional spending materially weakens your plan, maintaining a larger cushion may be worth it.
But if your retirement remains resilient even after increasing spending, the decision becomes more personal.
Would you rather preserve another portion of your portfolio?
Or turn some of that money into experiences while you are younger?
Neither answer is automatically correct.
A retirement plan isn’t successful simply because it produces the largest possible ending balance. It is successful when your money supports the retirement you actually wanted while maintaining a level of risk you can live with.
So instead of asking only:
“Can I afford to spend more?”
Ask one more question:
“If I can afford it, when would that money matter most?”
Load "Spend 20% More in Retirement" against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
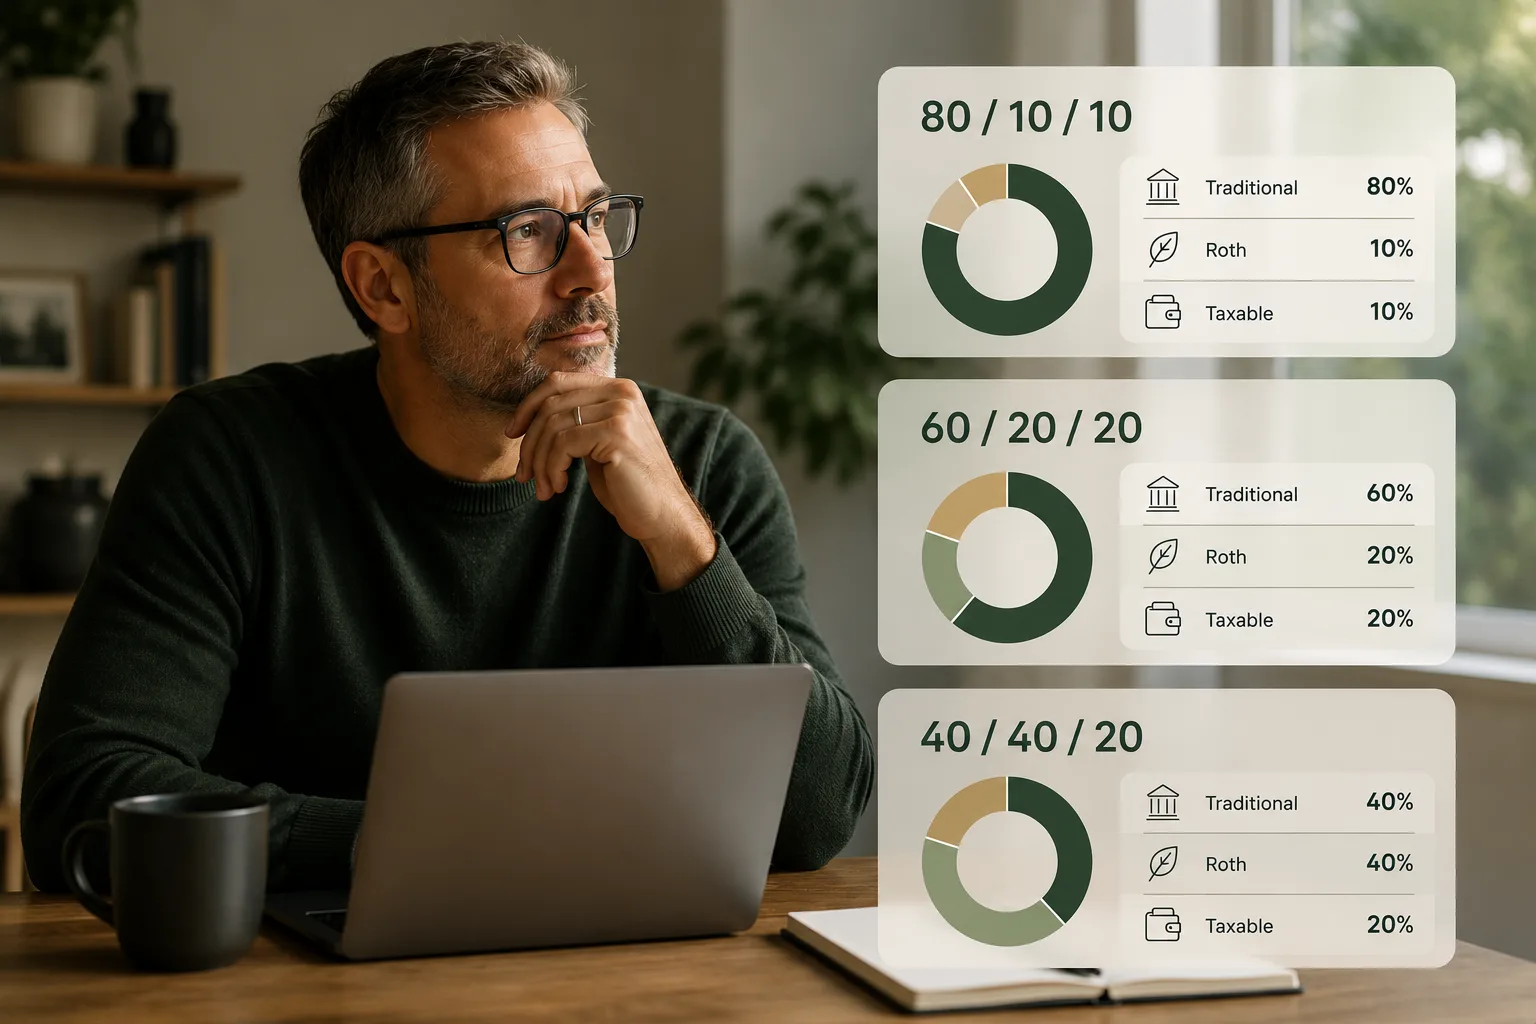
A balanced retirement account mix is not about equal percentages. Compare 80/10/10, 60/20/20, and 40/40/20 across Traditional, Roth, and taxable accounts to see how account location can change retirement flexibility.
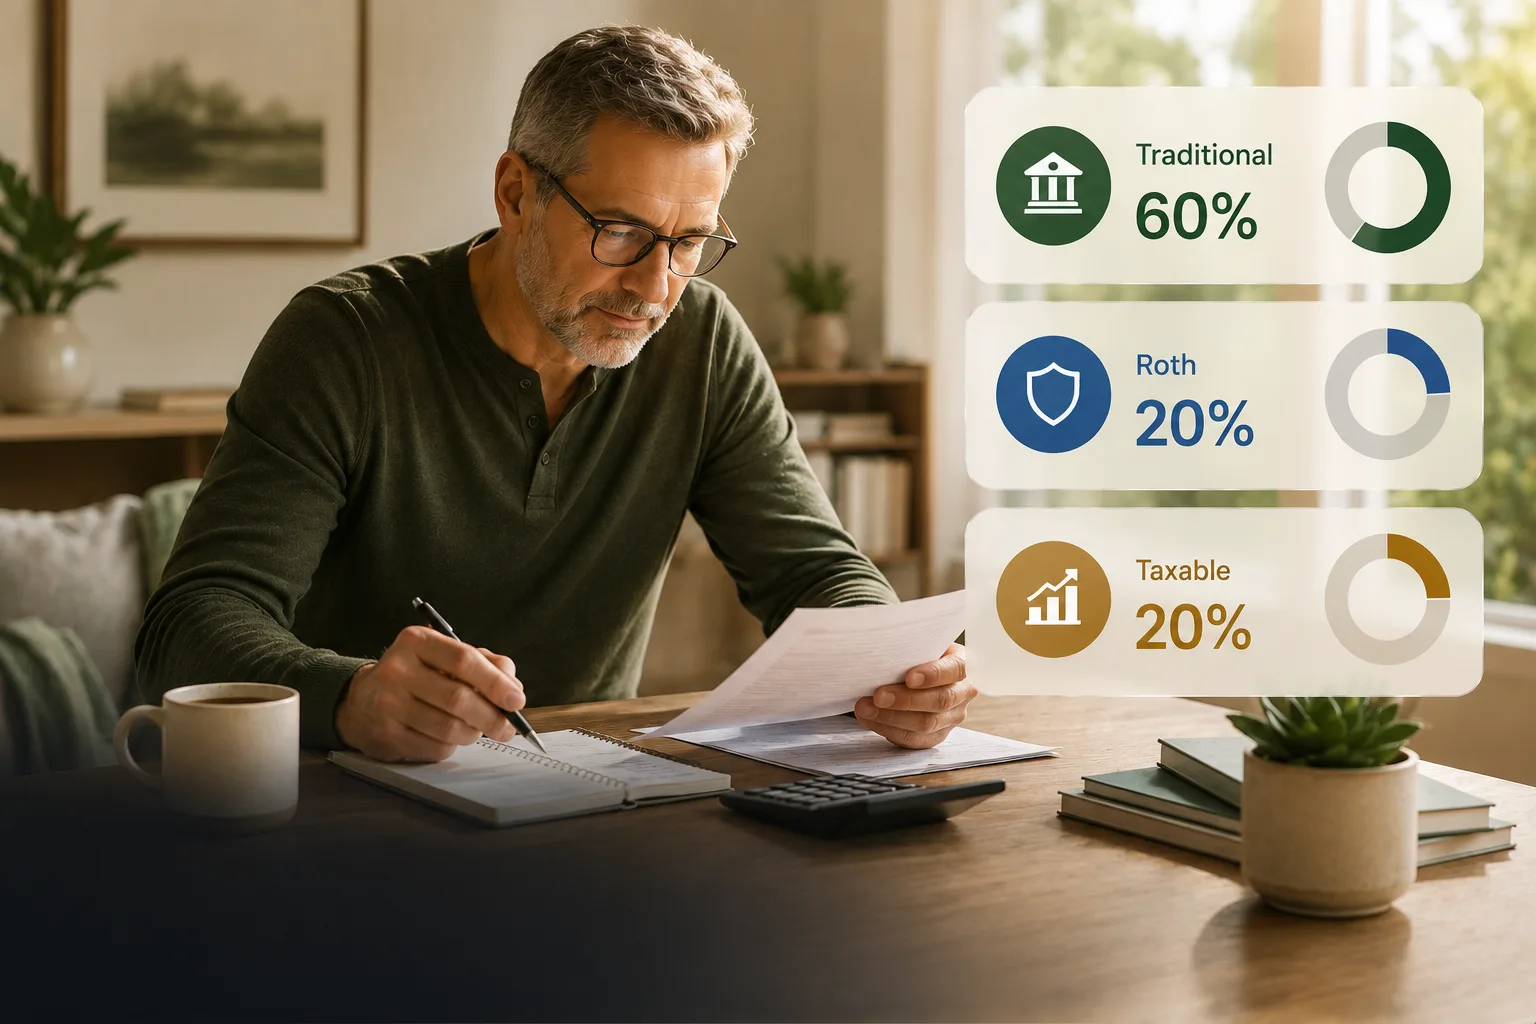
The same retirement savings can create very different tax
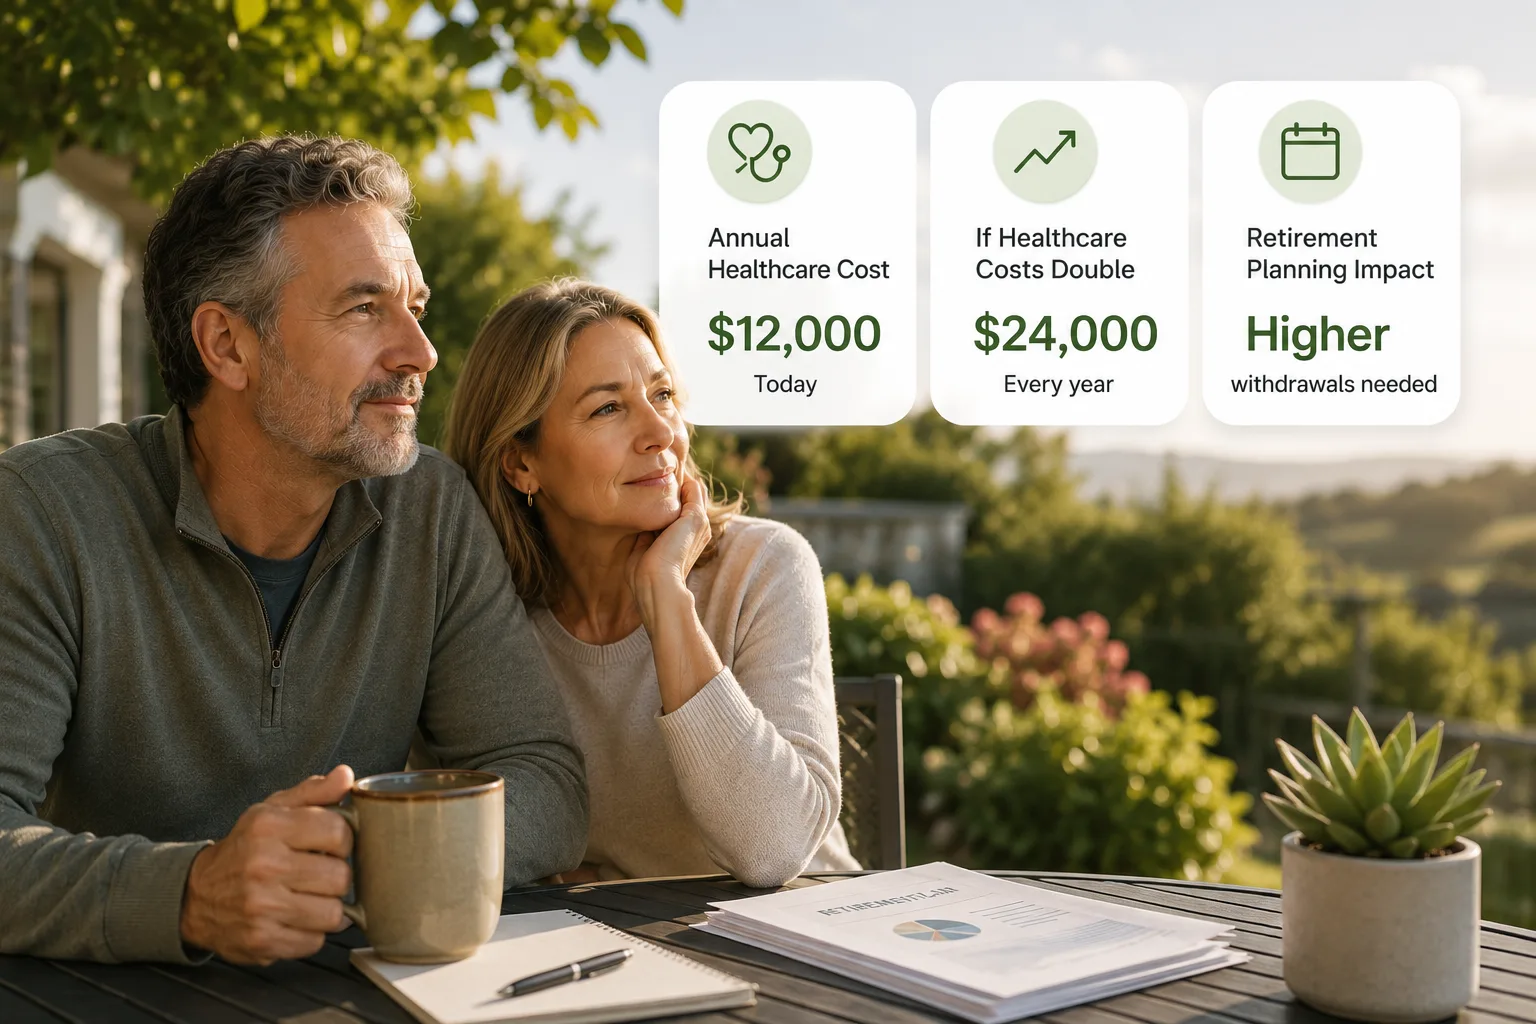
Your retirement plan may work with today's healthcare
