6 min read • Published about 1 month ago
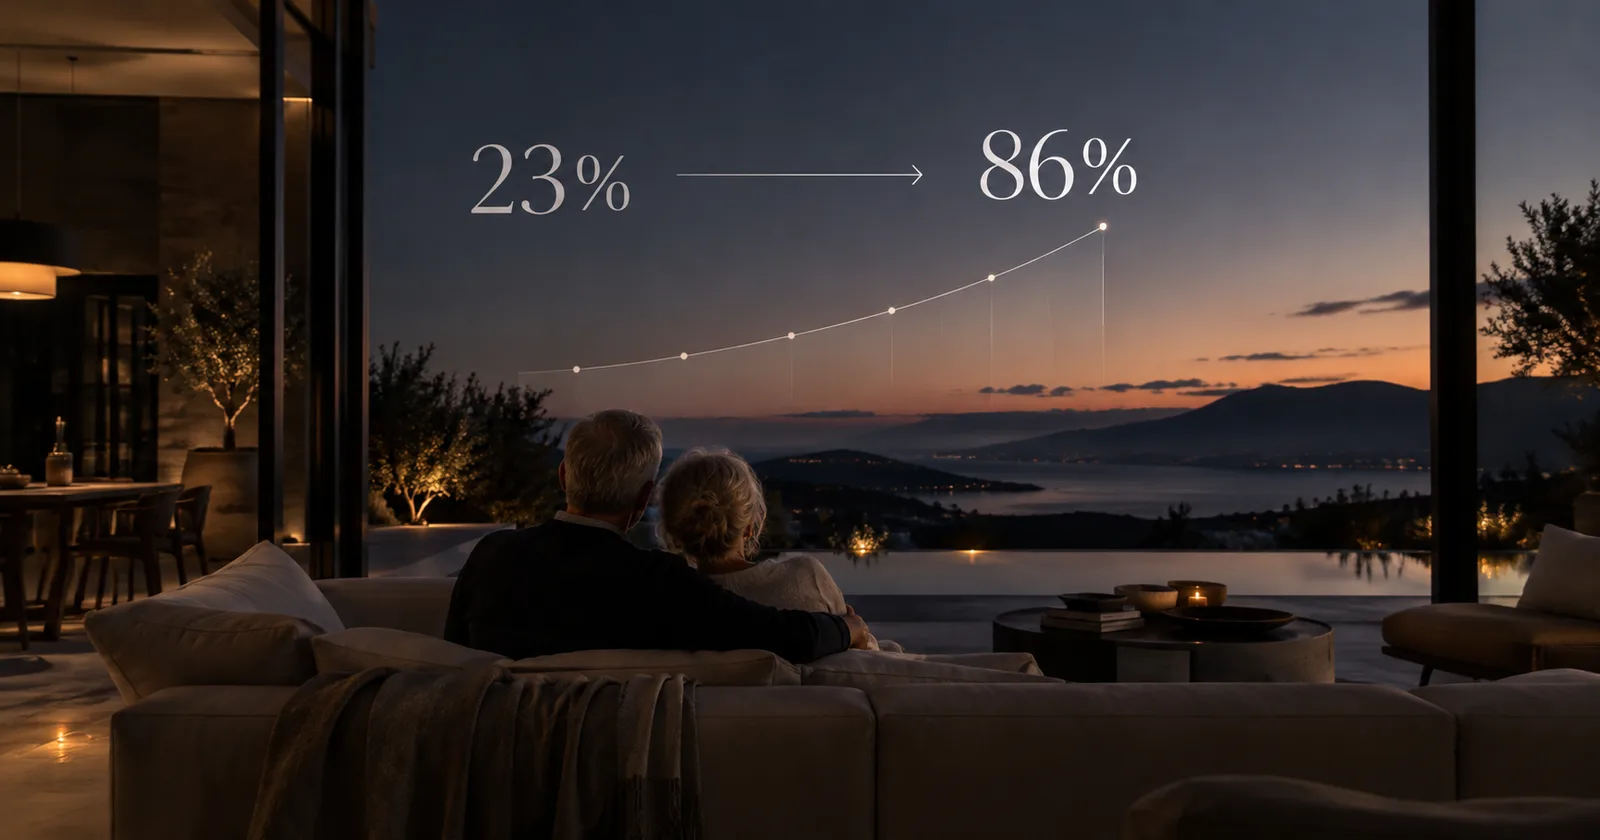
A retirement plan starts with a 23% probability of success. Add a small pension, and it rises to 35%. Add rental income instead, and it reaches 34%.
But include a spouse's savings and retirement income, and the result jumps to 86%.
The difference isn't marital status. It's the additional savings, income, and household expenses. Here's the math behind an illustrative 30-year retirement simulation.
These are modeled examples, not verified results from a specific Nestly customer plan.
Imagine retiring at 65 with:
The amount missing from annual income must come from investments:
$90,000 spending − $27,000 income = $63,000 withdrawn per year
That's $63,000 ÷ $1,000,000 = 6.30% of the starting portfolio in year one.
In our simulation, this plan funded all 30 years of withdrawals in 23.24% of market paths.
This comparison doesn't just tick a "married" box.
The spouse brings $350,000 in additional invested savings and $24,000 a year in spendable retirement income.
Household spending also rises by $8,000 a year.
| What changes | Annual or starting amount |
|---|---|
| Spouse's additional invested savings | +$350,000 |
| Spouse's additional annual income | +$24,000 |
| Additional household spending | +$8,000 |
| Net reduction in portfolio withdrawals | $16,000/year |
Now the couple has:
The new withdrawal calculation is:
$98,000 spending − $51,000 income = $47,000 withdrawn per year
The initial withdrawal rate becomes:
$47,000 ÷ $1,350,000 = 3.48%
Compare that with the original 6.30% withdrawal rate.
The spouse contributes in two important ways:
Together, those changes lift modeled retirement success to 86.31%.
To find out, we tested the spouse's financial contributions separately, keeping the original retirement plan unchanged in every other respect.
| Contribution included | Yearly withdrawal | Starting balance | Simulated success |
|---|---|---|---|
| Neither | $63,000 | $1,000,000 | 23% |
| $350K savings only | $63,000 | $1,350,000 | 59% |
| $16K net annual cash-flow benefit only | $47,000 | $1,000,000 | 58% |
| Both contributions | $47,000 | $1,350,000 | 86% |
The savings give the portfolio more room to absorb difficult markets.
The income helps by reducing the amount withdrawn each year.
The percentages aren't added together. Each row represents a separate simulation of the same starting plan with the specified change.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
They help, too—but we're adding much smaller amounts of annual income and no additional invested savings.
Consider two alternatives:
Here's exactly how each option changes the amount withdrawn from investments.
Original retirement plan
$90,000 annual spending − $27,000 retirement income
= $63,000 withdrawn annually
With pension income
$90,000 annual spending − $27,000 retirement income − $6,500 annual pension
= $56,500 withdrawn annually
With rental income
$90,000 annual spending − $27,000 retirement income − $6,000 annual net rental income
= $57,000 withdrawn annually
With spouse contributions
$98,000 combined household spending − $51,000 combined household income
= $47,000 withdrawn annually
The resulting success probabilities look like this:
| Retirement path | Annual withdrawal | Success |
|---|---|---|
| Original plan | $63,000 | 23% |
| Add pension | $56,500 | 35% |
| Add rental income | $57,000 | 34% |
| Add spouse resources | $47,000 | 86% |
These are four separate alternatives, not benefits stacked on top of one another.
A larger pension or a different rental investment could change the comparison.
The spouse example improves more because it combines additional invested savings with a larger reduction in yearly withdrawals.
We simulated 30,000 market paths across 30 years, using the same simulated returns for all four comparisons.
The simplified model assumes:
A path counts as successful only if the portfolio funds every planned withdrawal.
Here are the actual simulation counts:
| Retirement path | Successful paths | Probability |
|---|---|---|
| Original plan | 6,972 / 30,000 | 23.24% |
| Pension | 10,603 / 30,000 | 35.34% |
| Rental income | 10,293 / 30,000 | 34.31% |
| Spouse contributions | 25,892 / 30,000 | 86.31% |
These calculations demonstrate how different financial resources can affect retirement sustainability.
This simplified simulation doesn't fully model taxes, changing benefits, rental vacancies, survivor benefits, or changing household needs. Different assumptions can produce substantially different results.
Start with your own Nestly retirement plan.
If you're planning with a spouse, make sure your household plan includes:
You can also test a separate example: $500 a month in net rental cash flow from $1,000 monthly gross rent and $500 in modeled monthly operating costs.
A spouse's financial contribution can transform a retirement projection when it adds meaningful savings and reduces the household's need to withdraw from investments.
But marriage alone doesn't create that advantage.
Before deciding whether you're ready to retire, look at the whole household: what each partner has saved, what income each receives, and what it costs to live together.
Your retirement success depends not just on how much you've saved, but also on how much you need to withdraw from those savings.
Illustrative financial planning example. Simulated success rates are model-dependent, are not guarantees, and are not results from Nestly's production engine.
Start from your current plan, change one assumption from the article, and save the version only if it is worth comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
See how a smaller Social Security benefit could change your retirement withdrawals—and three ways to respond.
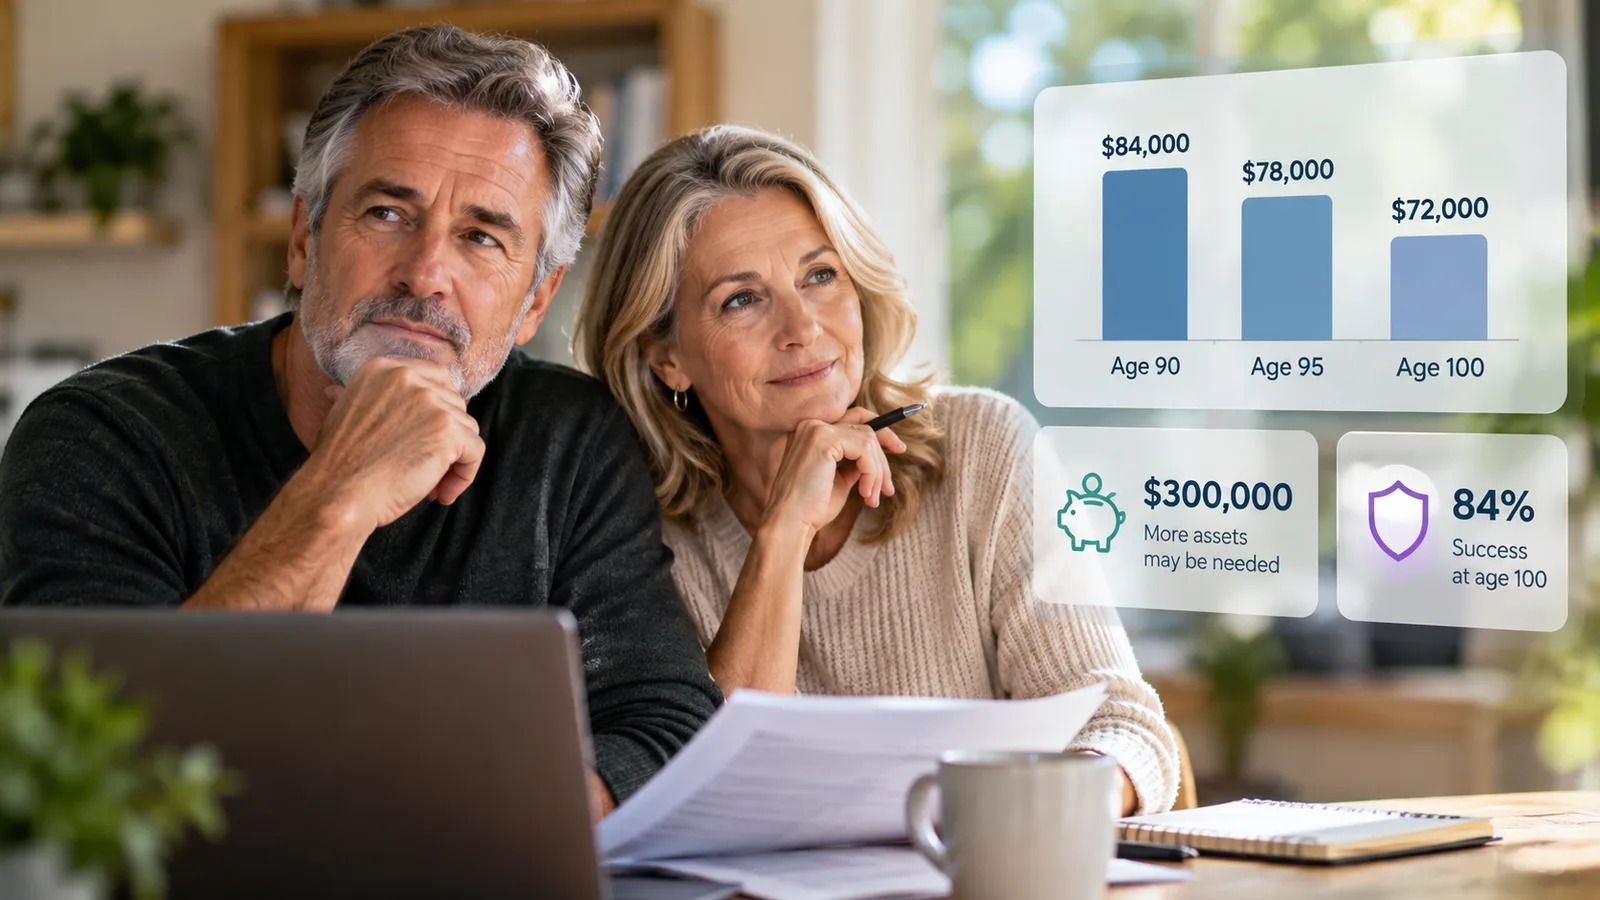
See how planning through age 90, 95, or 100 can change sustainable spending, required savings, retirement success, and the cushion left in your plan.
Should you use $300,000 to buy lifetime income or keep it invested? Compare what happens at ages 75, 85, and 95.
