6 min read • Published 3 months ago • Updated Aug 16, 2026
Load all 3 article strategies with your numbers before you decide.
A retirement portfolio can look diversified on the surface and still be heavily concentrated in one place for tax purposes.
You might own U.S. stocks, international funds, bonds, and cash. But if almost all of those investments sit inside Traditional 401(k)s and IRAs, most of your retirement savings may eventually be withdrawn as taxable income.
That is why retirement diversification is not only about what you own.
It can also be about where you own it.
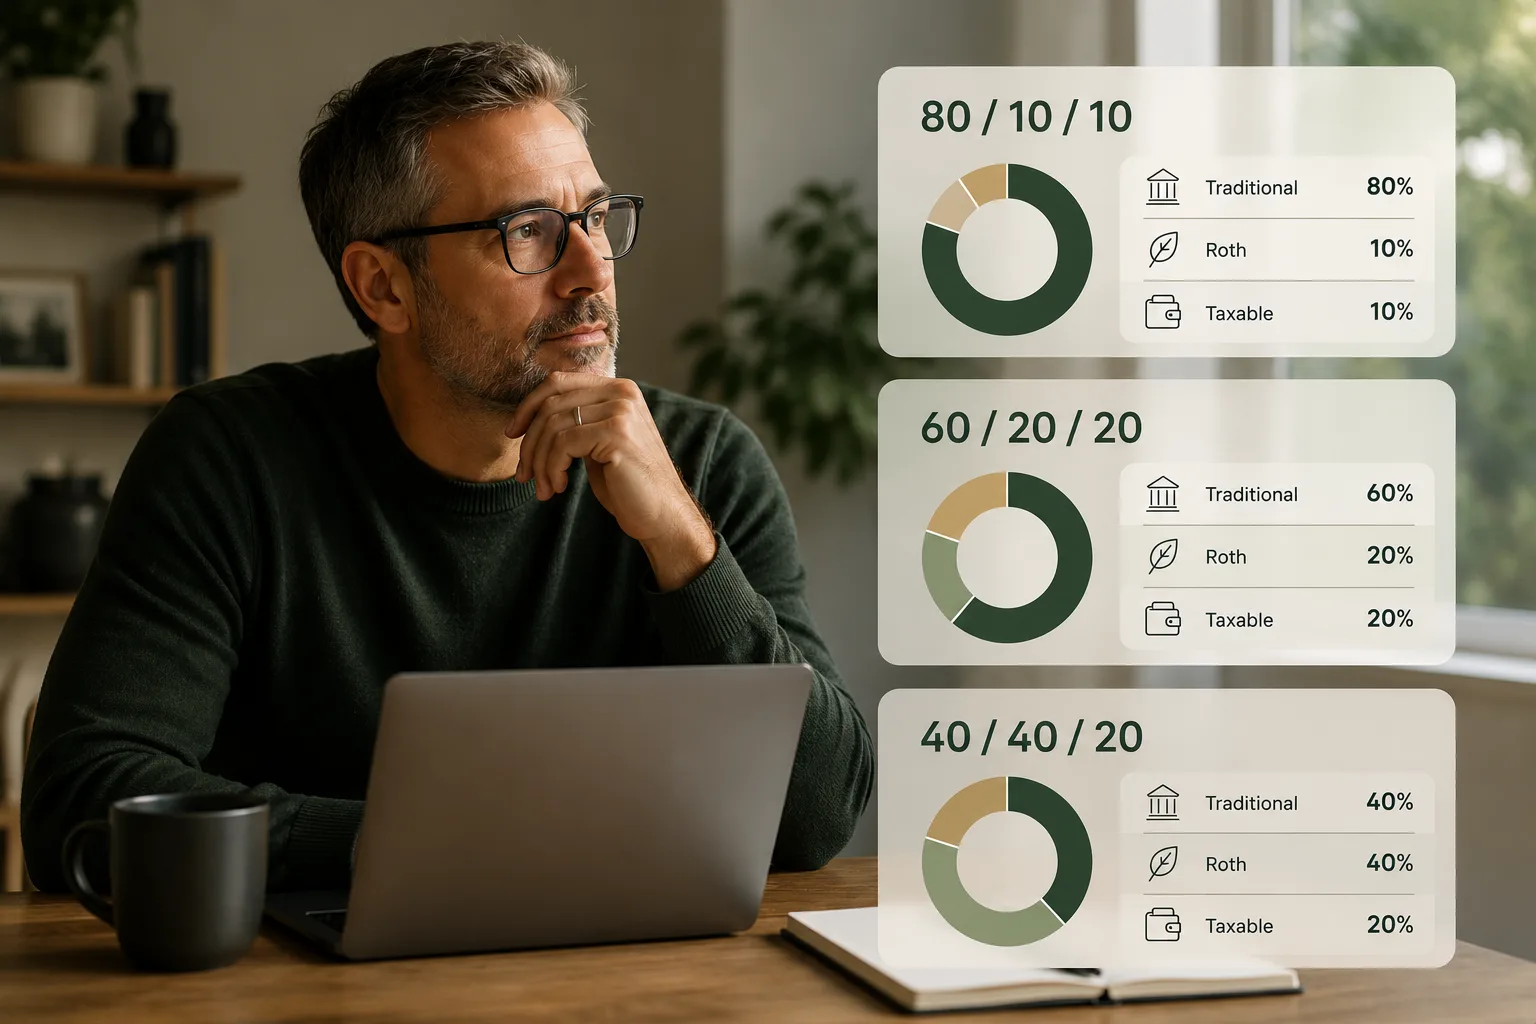
Consider three people with the exact same total retirement savings:
Their total wealth is identical.
But their flexibility in retirement can be very different.
There is no universal retirement account mix that everyone should target.
A 60/20/20 portfolio is not automatically better than an 80/10/10 portfolio. And having more money in Roth accounts does not automatically make a retirement plan stronger.
Instead, think of account diversification as giving yourself different financial tools.
| Account type | General retirement characteristic |
|---|---|
| Traditional | Contributions may receive tax advantages today; withdrawals are generally taxable |
| Roth | Qualified withdrawals are generally tax-free |
| Taxable | Accessible without retirement-account withdrawal rules, but dividends, interest, and realized gains may create taxes |
The value of having multiple account types becomes clearer when you start withdrawing money.
Imagine 80% of your retirement assets are held in Traditional retirement accounts.
This is not unusual.
Someone who spent decades contributing heavily to a Traditional 401(k), receiving employer matches, and rolling old plans into Traditional IRAs could naturally arrive at retirement with this kind of mix.
There are real advantages.
Traditional contributions may have reduced taxable income during working years, and decades of tax-deferred compounding can create a substantial retirement balance.
But retirement introduces another consideration:
Most of the portfolio is tied to future taxable withdrawals.
If you need significant withdrawals in a particular year, you may have relatively little Roth or taxable money available as alternative funding sources.
That can reduce your ability to choose where retirement income comes from.
A large retirement balance and a flexible retirement balance are not always the same thing.
See how your retirement plan changes when 80% is Traditional, 10% is Roth, and 10% is taxable.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Now consider moving toward a more distributed mix:
60% Traditional
20% Roth
20% Taxable
Traditional accounts still represent the largest portion of the portfolio.
But now 40% sits outside Traditional retirement accounts.
That creates more potential choices.
Suppose you have an unusually expensive retirement year.
Maybe you replace a car, take a major trip, renovate your home, or help a child with a large expense.
Rather than automatically taking the entire amount from a Traditional account, you may have the ability to coordinate withdrawals across different account types.
That does not guarantee lower taxes.
But it can give you more control over how taxable income is created.
See how your retirement plan changes when 60% is Traditional, 20% is Roth, and 20% is taxable.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
The third portfolio goes much further toward Roth diversification:
40% Traditional
40% Roth
20% Taxable
Only 40% of the starting portfolio is now in Traditional accounts.
Another 40% sits in Roth accounts, while 20% remains taxable.
For someone entering retirement, this could create substantial withdrawal flexibility.
Qualified Roth withdrawals generally do not increase taxable income. Taxable brokerage assets can provide another funding source, although selling investments can create capital gains.
Traditional accounts remain useful as well.
The point is not to eliminate them.
It is that the retiree now has three substantially different pools of money available when deciding how to fund retirement.
See how your retirement plan changes when 40% is Traditional, 40% is Roth, and 20% is taxable.
All article tests · No account neededOpens every article test in Lab. No account required until you save.During your working years, the question is often:
How much can I save?
In retirement, another question becomes increasingly important:
Which account should I withdraw from?
Imagine needing an extra $50,000 one year.
Taking $50,000 from a Traditional IRA may have a different tax effect than using qualified Roth withdrawals or selling $50,000 of taxable investments.
The taxable account also does not necessarily create $50,000 of taxable income. Tax treatment depends partly on the investment's cost basis and realized gain.
This is where account diversification becomes useful.
It gives a retiree choices.
That is the wrong question.
A better question is:
Which mix gives your retirement plan the flexibility it needs?
Here is the real tradeoff:
| Mix | Traditional | Roth | Taxable | General characteristic |
|---|---|---|---|---|
| 80/10/10 | 80% | 10% | 10% | Heavily tax-deferred |
| 60/20/20 | 60% | 20% | 20% | More distributed |
| 40/40/20 | 40% | 40% | 20% | Greater Roth allocation |
None of these should be treated as a universal target.
Your appropriate mix can depend on your current tax rate, expected retirement income, age, existing balances, withdrawal needs, Social Security strategy, pension income, estate goals, and many other factors.
And importantly, building Roth assets can involve paying taxes earlier rather than later.
You are not making taxes disappear.
You are deciding when and under what circumstances you may pay them.
A balanced retirement portfolio is not necessarily one where every account has the same amount of money.
It is one that gives you enough flexibility to make intelligent decisions as circumstances change.
Markets change.
Tax laws change.
Spending changes.
Your income changes.
Retirement itself can last 20 or 30 years.
Having Traditional, Roth, and taxable assets can give you multiple ways to respond.
So instead of looking only at the number at the top of your retirement statement, look underneath it.
Ask:
Where is my retirement money actually held?
Because two people can retire with the same amount of savings—and still have very different options for turning those savings into retirement income.
This article is for educational purposes only and does not provide individualized tax, investment, or financial advice. Tax treatment and retirement-account rules depend on individual circumstances and applicable law.
Load all 3 tests from this article against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
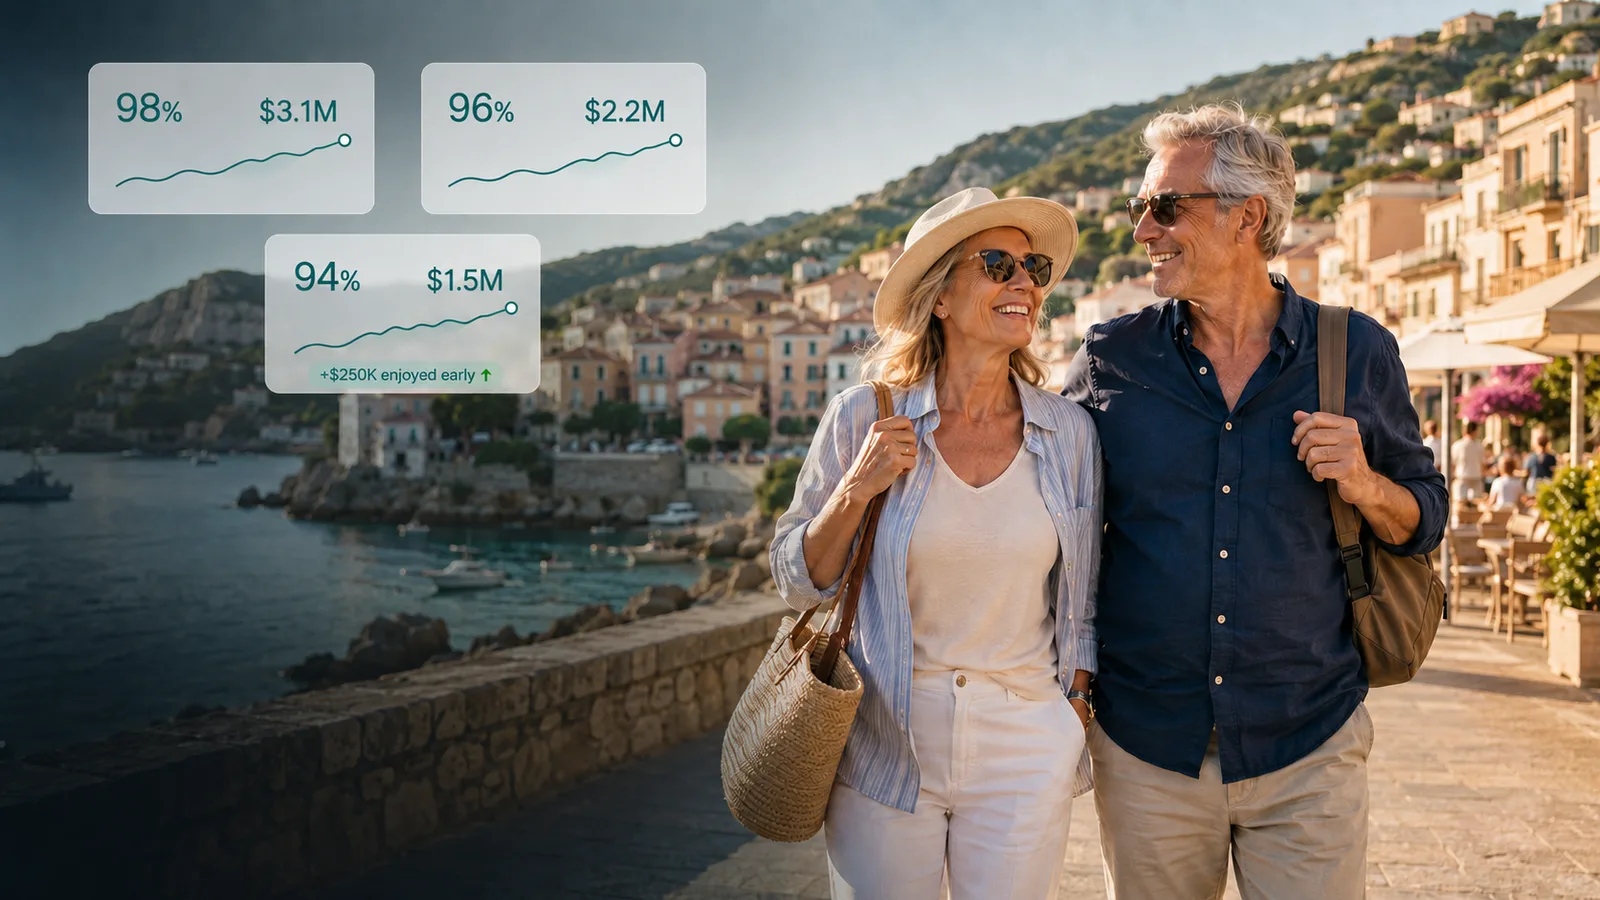
A higher retirement success rate is not automatically a better retirement. Compare preserving more with enjoying more while you are younger.
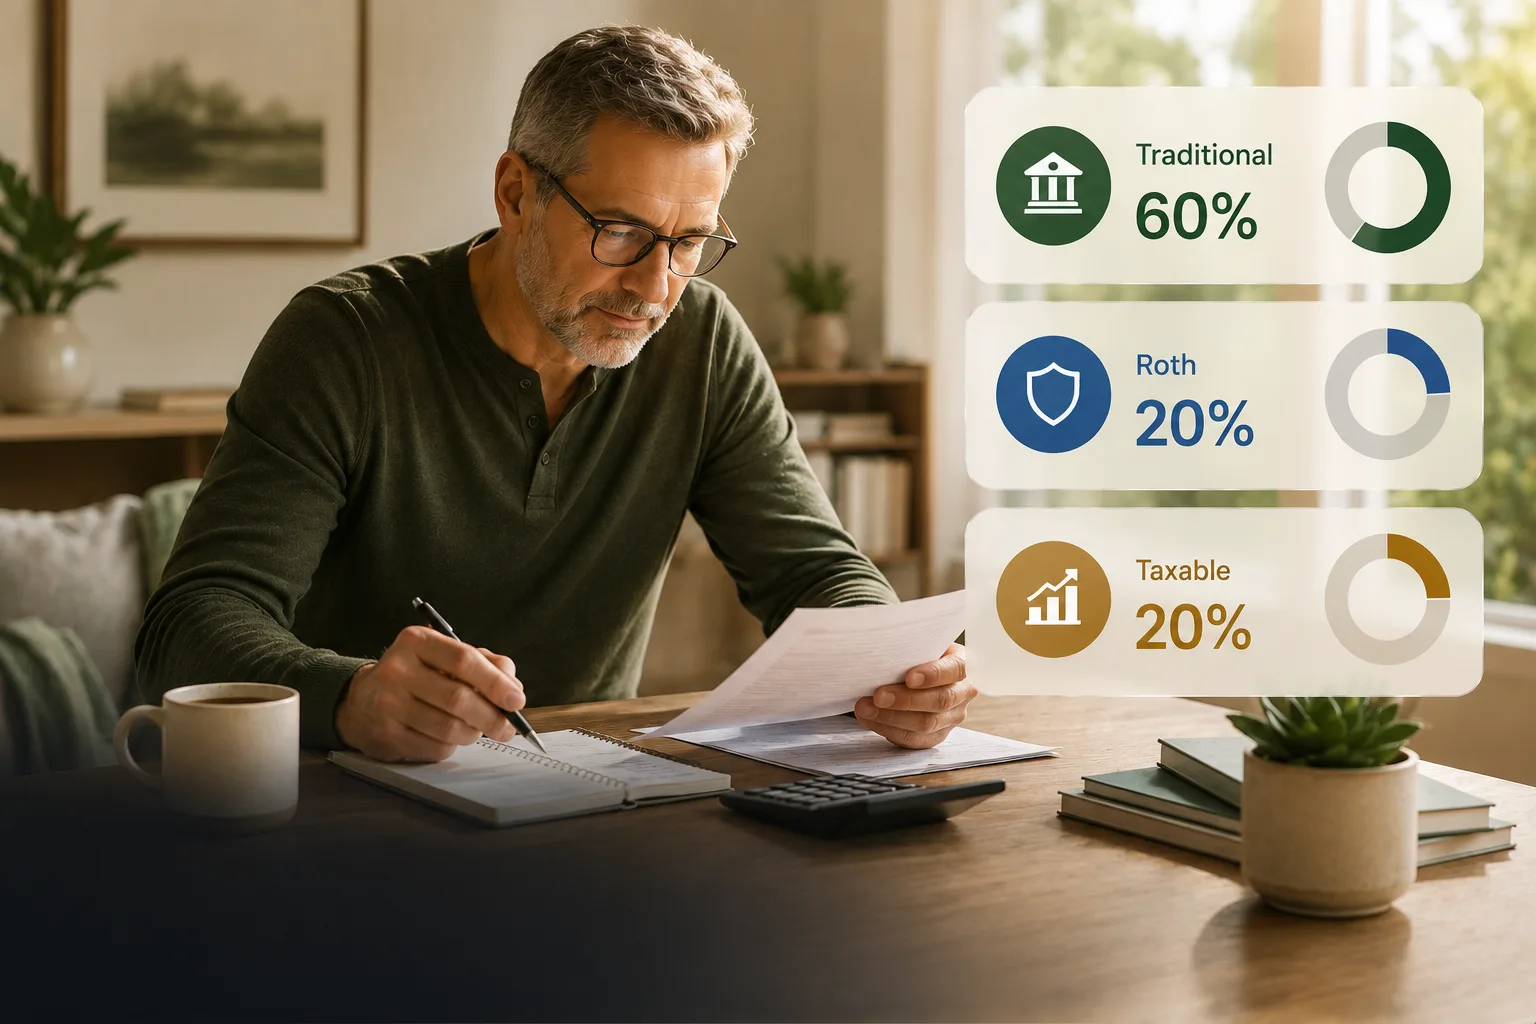
The same retirement savings can create very different tax
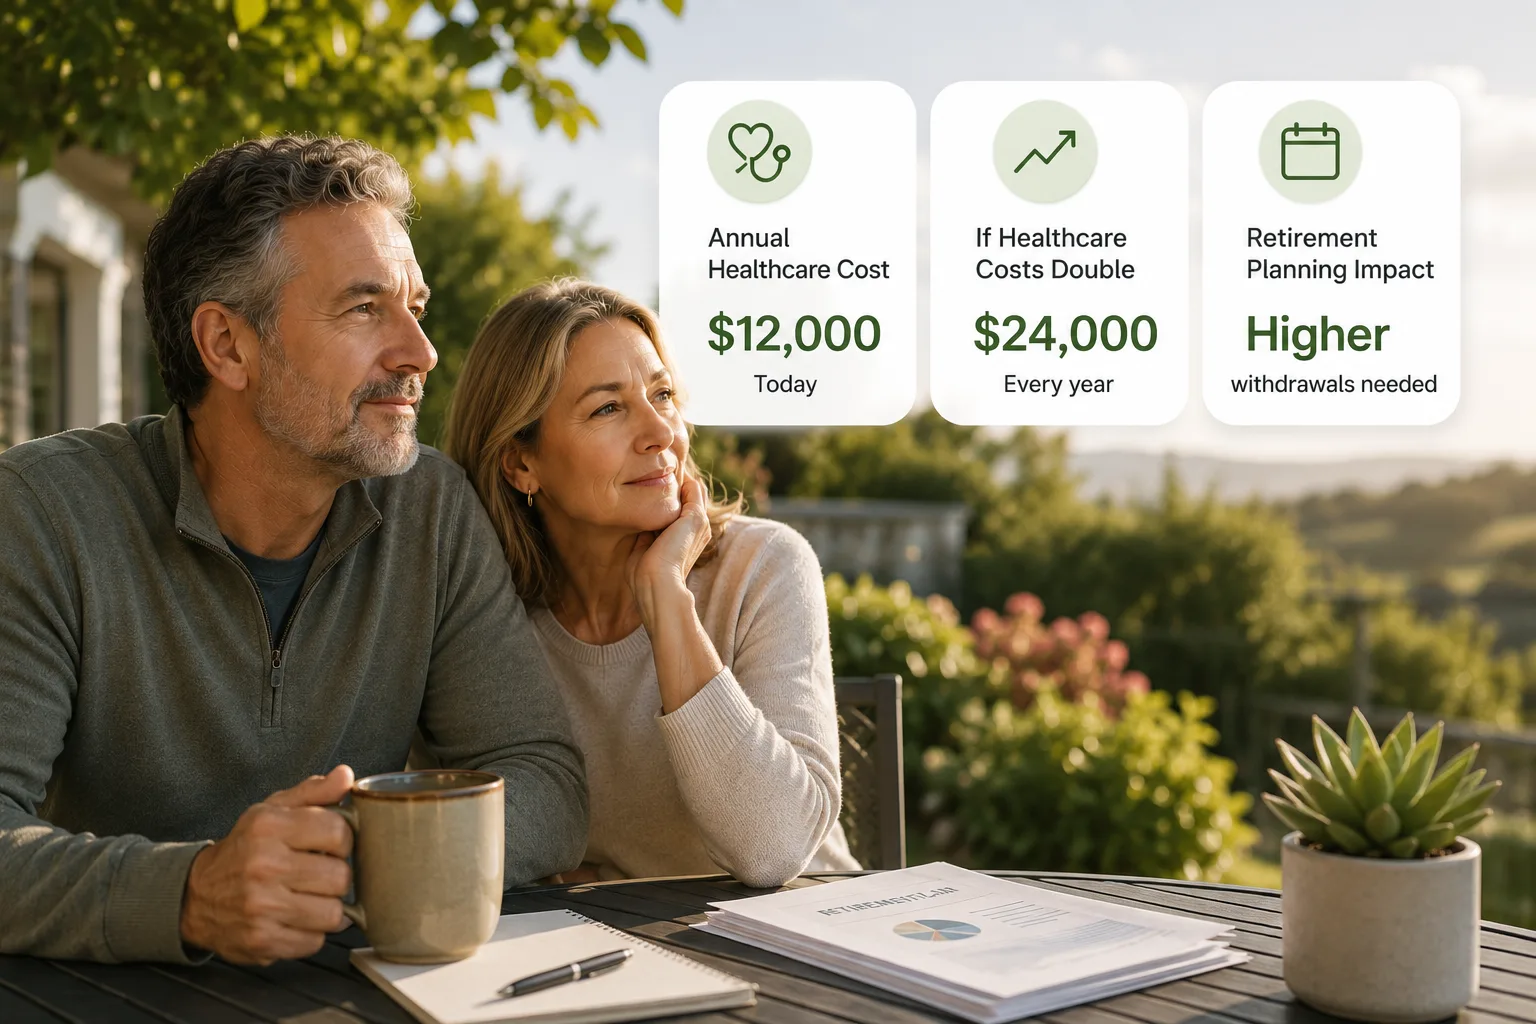
Your retirement plan may work with today's healthcare
