4 min read • Published 2 months ago
You retire at 62 with $1.5 million.
You plan to spend about $75,000 a year.
The numbers look good. Your portfolio supports your lifestyle, you have room for normal ups and downs, and retirement finally feels less like something you're preparing for and more like something you're living.
Then you turn 72.
And a $150,000 expense shows up.
Not gradually. Not neatly spread across 20 years.
All at once.
Maybe it's healthcare. Maybe your house needs major work. Maybe someone in your family needs help. Maybe your care needs change. Or maybe it's something you never thought to include in a retirement calculator.
The specific reason matters less than the question it creates:
Your retirement works today. How much room does it have for one really expensive surprise?
A retirement projection usually includes thousands of smaller assumptions: spending, inflation, investment returns, Social Security, healthcare and longevity.
But real life doesn't always arrive as a smooth annual percentage.
Sometimes it arrives as a bill.
Consider four versions of the same retirement.
Retirement continues roughly as originally planned.
This is the version most projections naturally encourage us to focus on: the expected path.
It's useful.
But it isn't the only path worth seeing.
This is significant — roughly one full year of planned retirement spending in this example.
A resilient plan may absorb it without fundamentally changing retirement.
But the important part isn't simply whether the portfolio survives.
It's whether the expense forces other changes:
Now the surprise equals roughly two years of planned spending.
This is where the difference between having a retirement plan and having margin inside the plan becomes easier to see.
The question becomes less:
"Do I have enough?"
and more:
"How much can go wrong before I need to adjust?"
A plan could still work after a large expense while leaving noticeably less flexibility for future surprises.
That distinction matters.
A quarter-million-dollar shock sounds extreme.
That's exactly why it can be useful to test.
You're not predicting that it will happen.
You're asking what would happen if it did.
If the plan remains reasonably resilient, that can reveal how much unused capacity exists.
If the plan becomes fragile, you've identified a risk that may be worth planning around before the expense ever appears.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
No projection can tell you exactly what your life will cost at 72.
And trying to predict every possible emergency isn't realistic.
A more useful approach is to test the plan itself.
Instead of asking whether you can predict the surprise, ask whether your retirement has enough flexibility to absorb one.
You could always save more.
You could always spend less.
You could always leave a larger ending balance.
But eventually, the purpose of retirement planning isn't to eliminate every possible risk.
It's to understand which risks your plan can already handle — and which ones would actually require you to change course.
Imagine two retirement plans that both work under normal assumptions.
One can absorb a $150,000 surprise with relatively little change.
The other works only if almost everything stays close to plan.
They may look similar on the surface.
They aren't equally flexible.
That's why a useful retirement plan shouldn't answer only:
Can I retire?
It should also help answer:
How much can life change before my retirement has to change with it?
That may be a better definition of retirement security.
Start from your current plan, change one assumption from the article, and save the version only if it is worth comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
See how a spouse's retirement savings and income can dramatically improve retirement success, with clear calculations comparing a base plan, pension, rental income, and combined household finances.
See how a smaller Social Security benefit could change your retirement withdrawals—and three ways to respond.
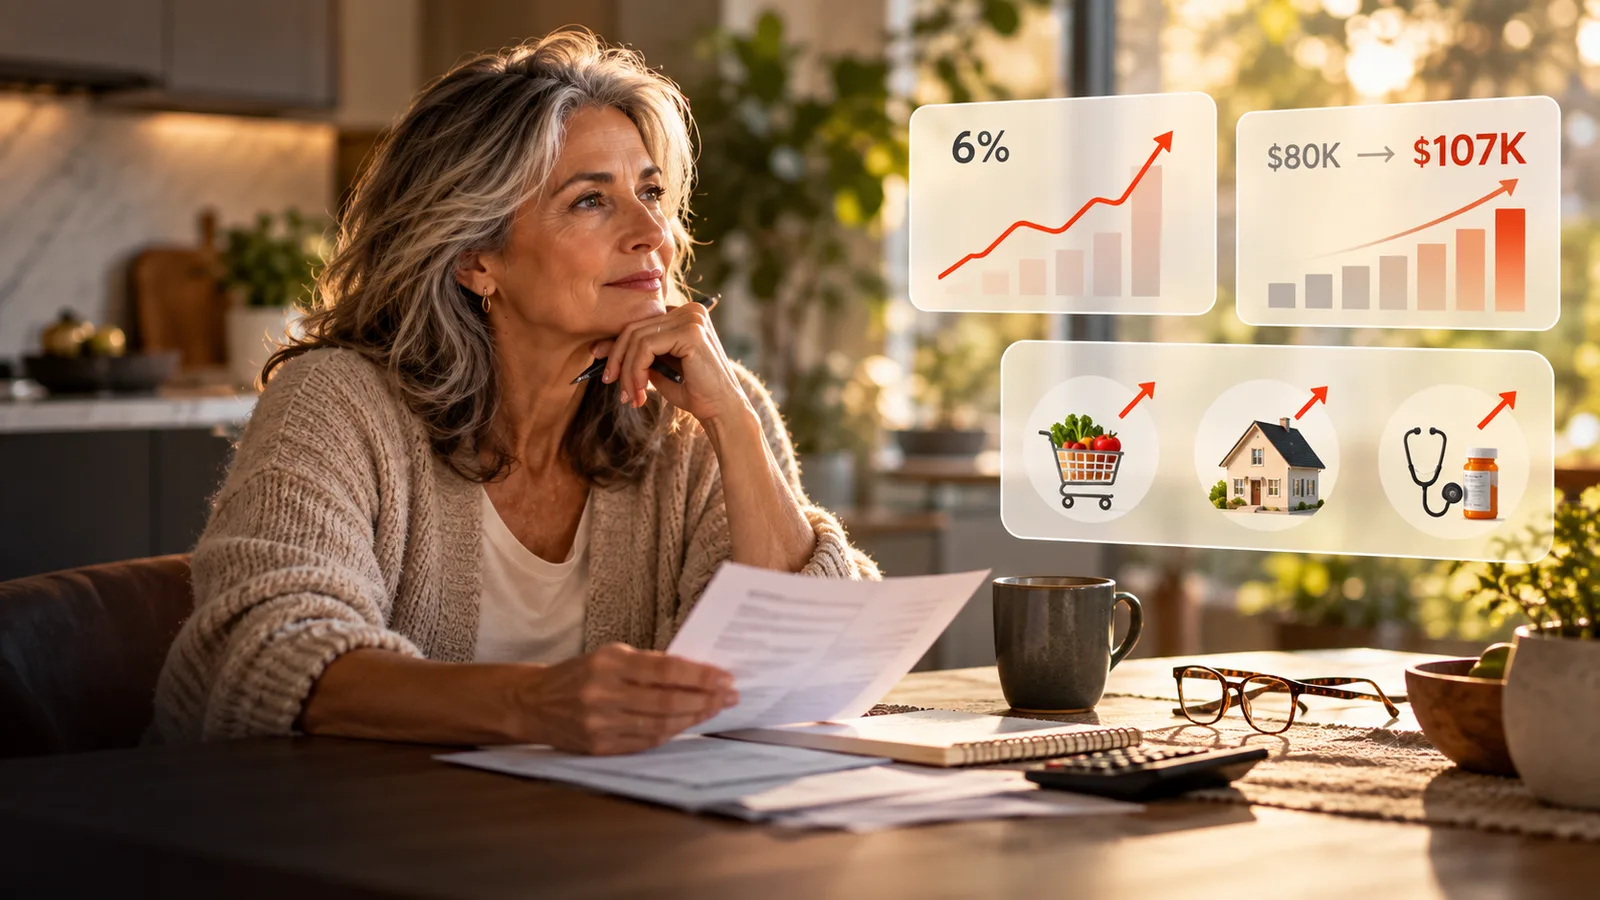
A few years of high inflation right after retirement can raise withdrawals quickly. See how maintaining your lifestyle—or temporarily adjusting it—can change the pressure on your plan.
