4 min read • Published 3 months ago • Updated Aug 15, 2026
Load this article strategy with your numbers before you decide.
Your retirement plan works.
Your savings look sufficient. Social Security helps cover expenses. Your projected spending fits comfortably inside the plan.
But there's one assumption that can change the picture:
Healthcare.
What if the amount you've budgeted isn't just a little low?
What if it's twice as high?
That's a scenario worth testing before you retire.
Many retirement expenses are flexible.
You can travel less, postpone a new car, or reduce entertainment spending.
Healthcare isn't always that flexible.
And Medicare doesn't make healthcare free. Retirees can still face premiums, deductibles, prescriptions, supplemental coverage, and other out-of-pocket expenses.
So underestimating healthcare doesn't just affect one line of your budget.
It can increase the amount you need to withdraw from your portfolio every year.
Consider a retiree spending $7,500 per month, including $1,000 for healthcare.
| Expense | Monthly |
|---|---|
| Housing | $2,500 |
| Food & household | $1,500 |
| Travel & entertainment | $1,000 |
| Transportation | $500 |
| Healthcare | $1,000 |
| Other spending | $1,000 |
| Total | $7,500 |
Now double healthcare from $1,000 to $2,000 per month.
Total spending rises to:
$8,500 per month --- or $102,000 per year.
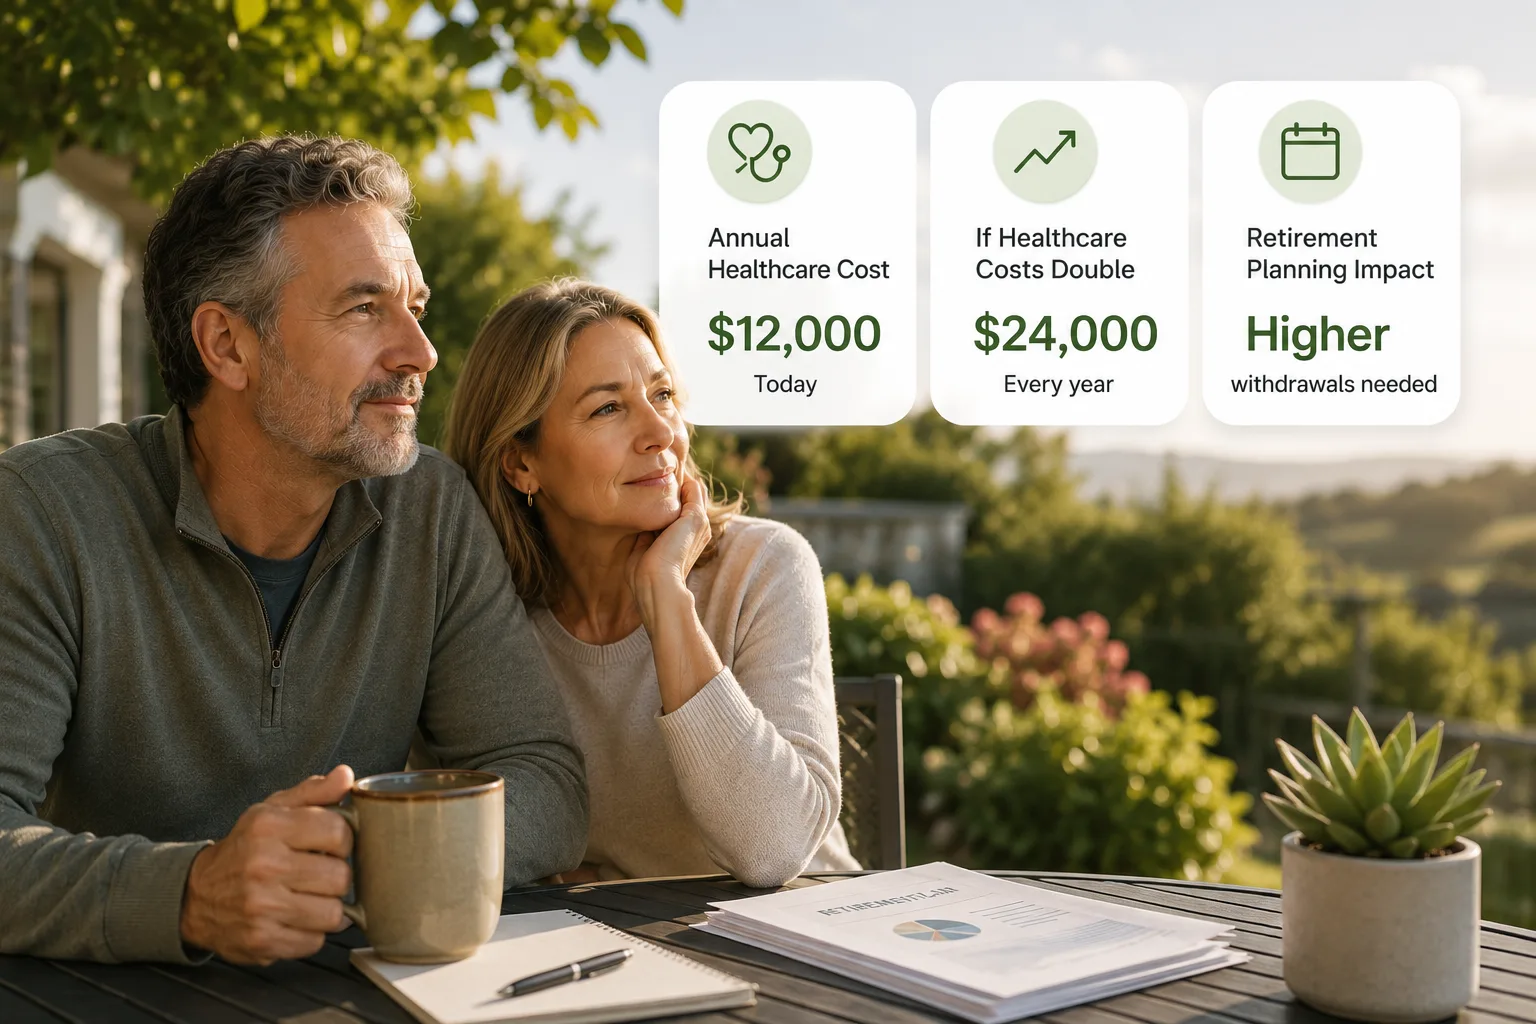
That's an additional $12,000 every year without changing anything else about retirement.
An extra $12,000 may not seem catastrophic in one year.
But retirement can last decades.
If higher costs last... Extra spending
5 years $60,000 10 years $120,000 20 years $240,000 30 years $360,000
These are simple cumulative amounts. They don't account for investment returns, inflation, taxes, or changing healthcare expenses.
But they show why a relatively small monthly difference can become a major retirement variable.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Higher healthcare costs can create a chain reaction:
That's why the important question isn't simply:
How much will healthcare cost?
It's:
What happens to my retirement if I'm wrong about healthcare?
Instead of guessing, stress-test it.
What happens if the healthcare expenses already configured in your retirement plan become twice as high?
See how your retirement outlook changes when your configured annual healthcare costs are twice as high.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Look at what changes.
Does your portfolio run down substantially faster?
Does your retirement margin shrink?
Do you still have room for travel and discretionary spending?
Does the plan still work if you live into your 90s?
A plan that works only when healthcare follows your original estimate may have less flexibility than it appears.
Medicare changes healthcare costs after 65, but it doesn't make them disappear.
Retirees may still have premiums and significant out-of-pocket expenses.
Healthcare also tends to become more important later in retirement, when medical needs may increase.
And there's another risk to consider:
Healthcare costing more today and healthcare costs growing faster over time are two different scenarios.
A strong retirement plan should be able to withstand both.
You don't need to predict exactly what you'll spend on healthcare at age 82.
Instead, build flexibility.
Stress-test higher costs. Don't plan only around your expected number.
Keep some spending flexible. Discretionary spending can provide room to adjust if essential expenses rise.
Include healthcare from the beginning. Don't calculate your retirement number first and add medical expenses later.
Separate healthcare from long-term care. They're related, but long-term care can create an entirely different financial risk.
Nobody knows whether your healthcare expenses will actually double.
That's not the point of the scenario.
The point is to find out what happens if they do.
If healthcare costs are much higher than I expect, does my retirement still work?
If the answer is yes, your plan has absorbed a difficult scenario.
If the answer is no, you've identified a weakness while you may still have time to do something about it.
Retirement planning isn't about predicting one perfect future.
It's about preparing for more than one version of it.
Load "Double Your Healthcare Costs" against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
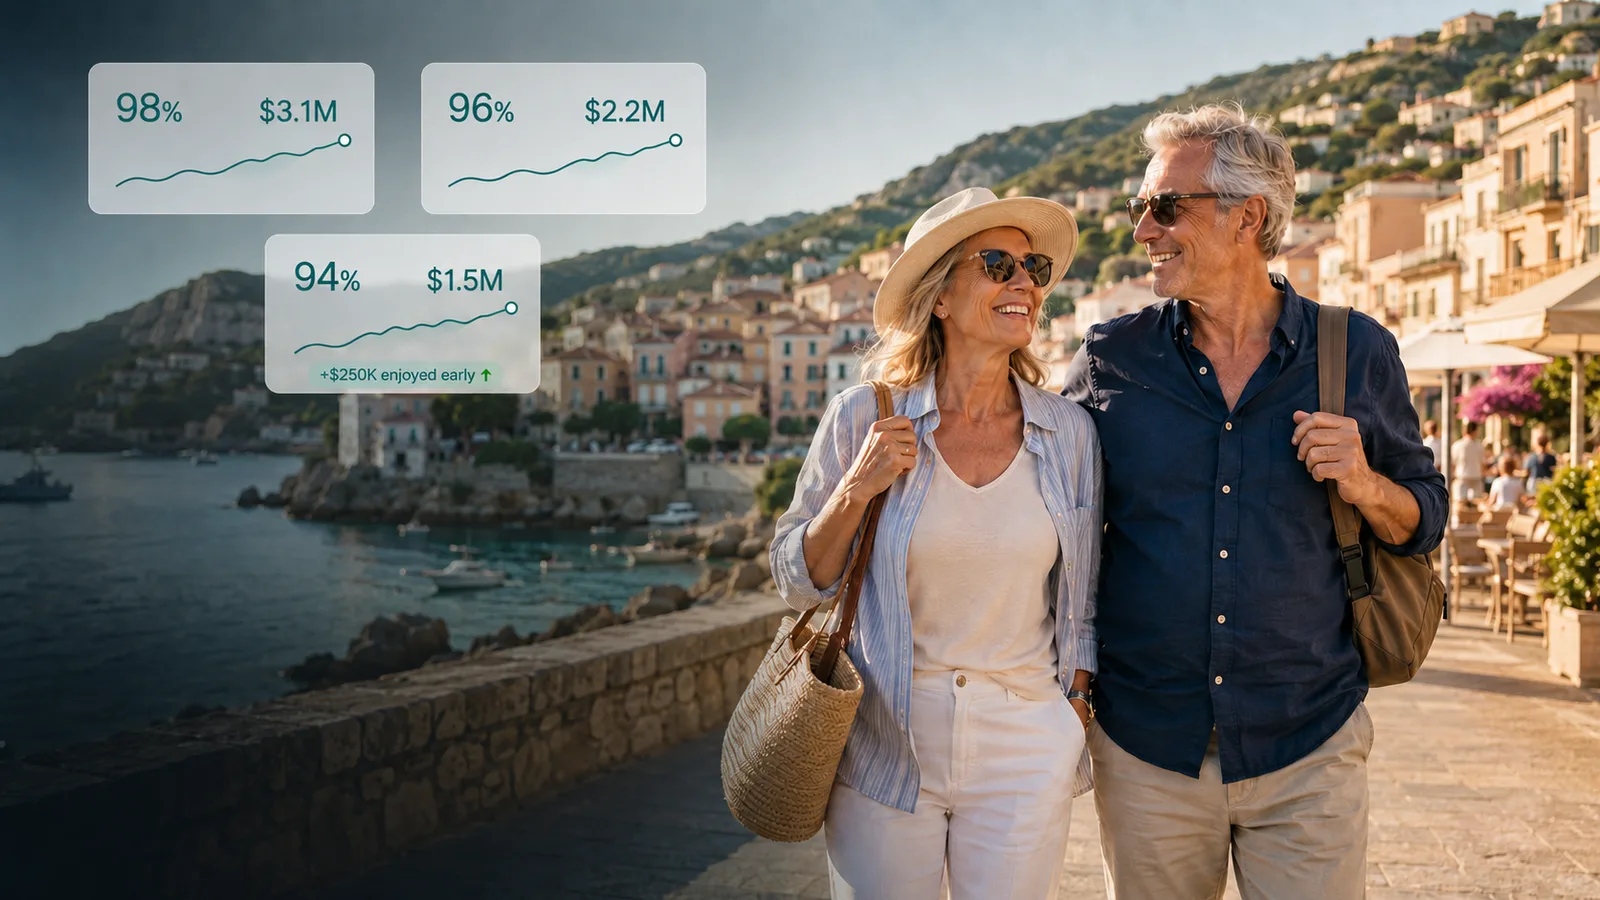
A higher retirement success rate is not automatically a better retirement. Compare preserving more with enjoying more while you are younger.
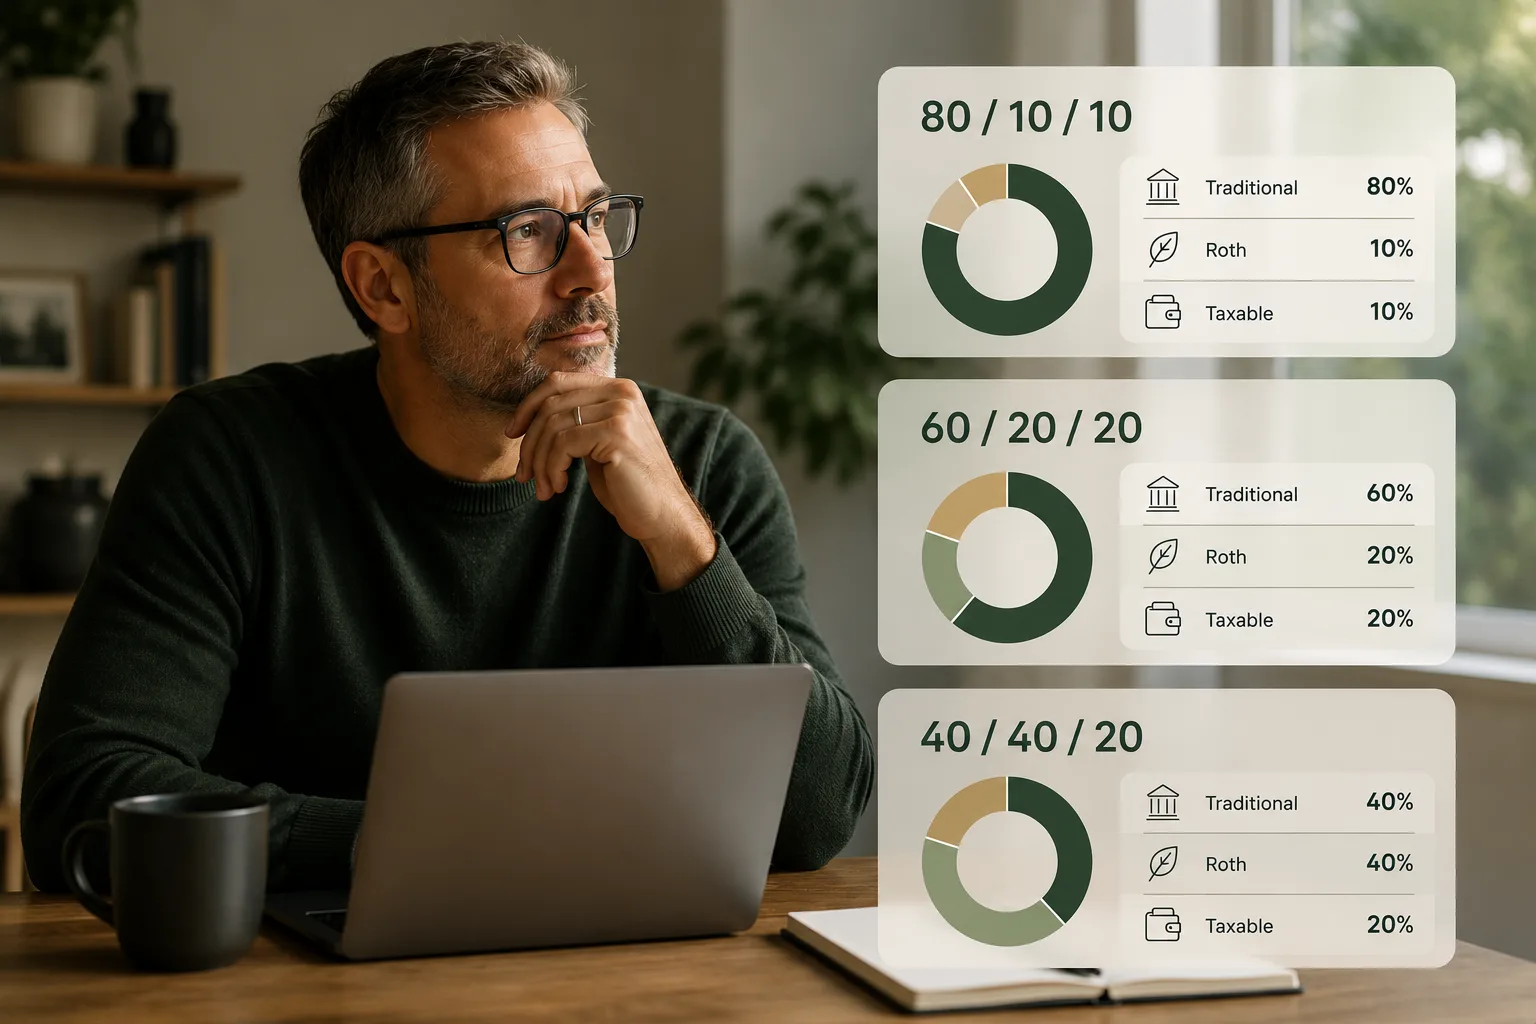
A balanced retirement account mix is not about equal percentages. Compare 80/10/10, 60/20/20, and 40/40/20 across Traditional, Roth, and taxable accounts to see how account location can change retirement flexibility.
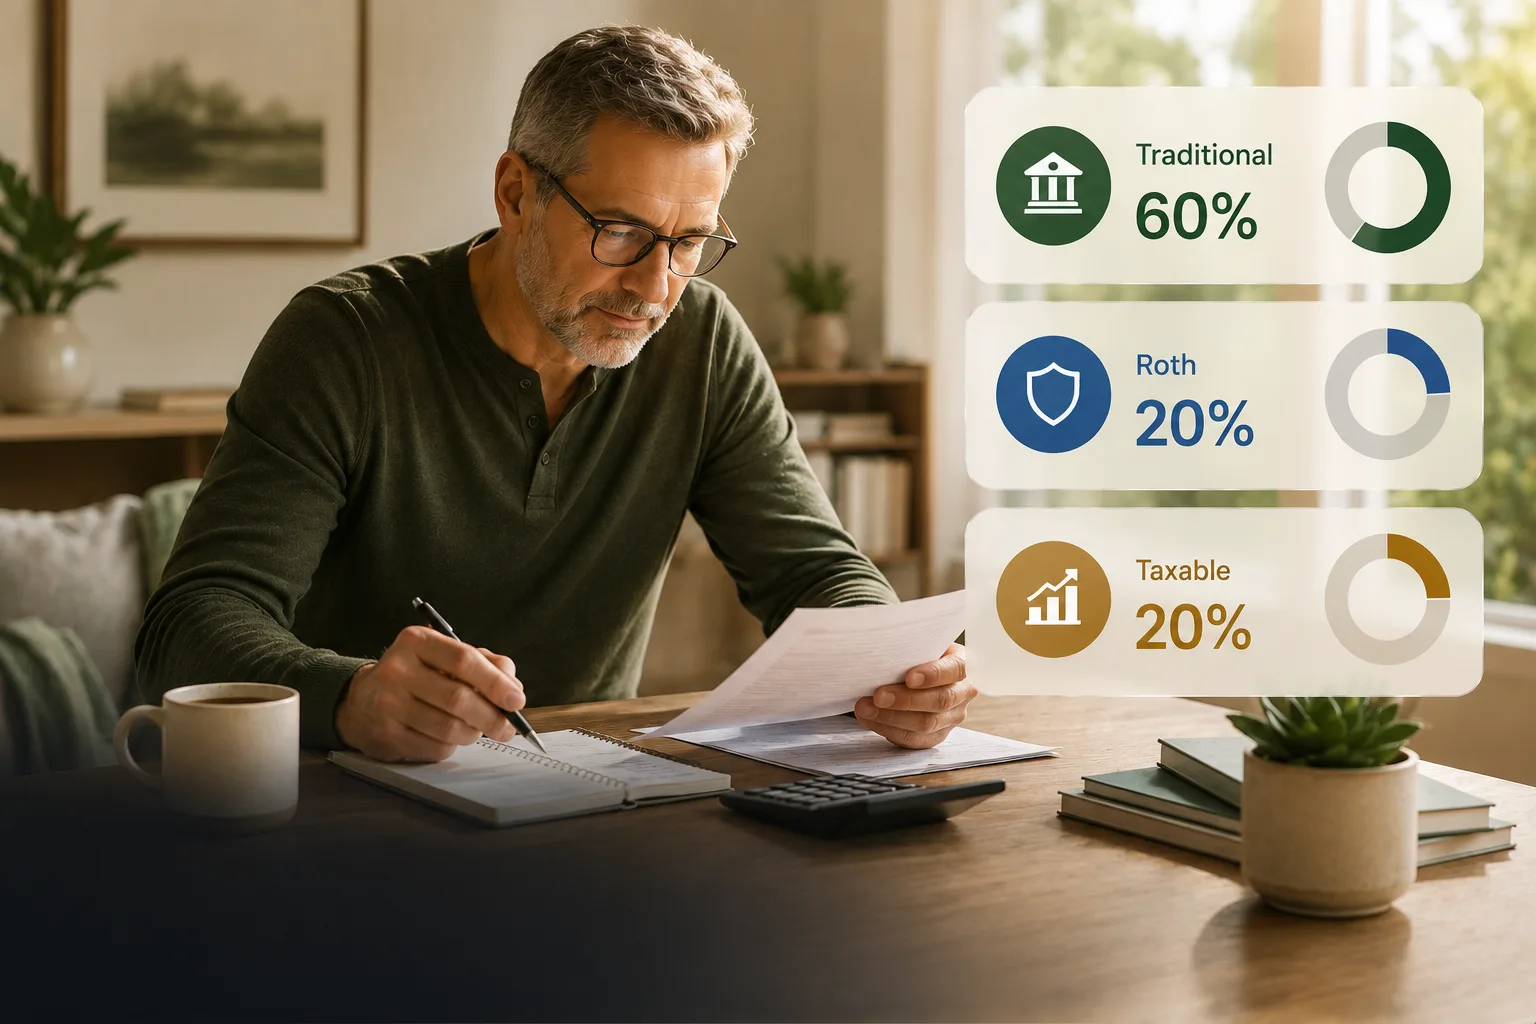
The same retirement savings can create very different tax
