6 min read • Published about 1 month ago
Load all 2 article strategies with your numbers before you decide.
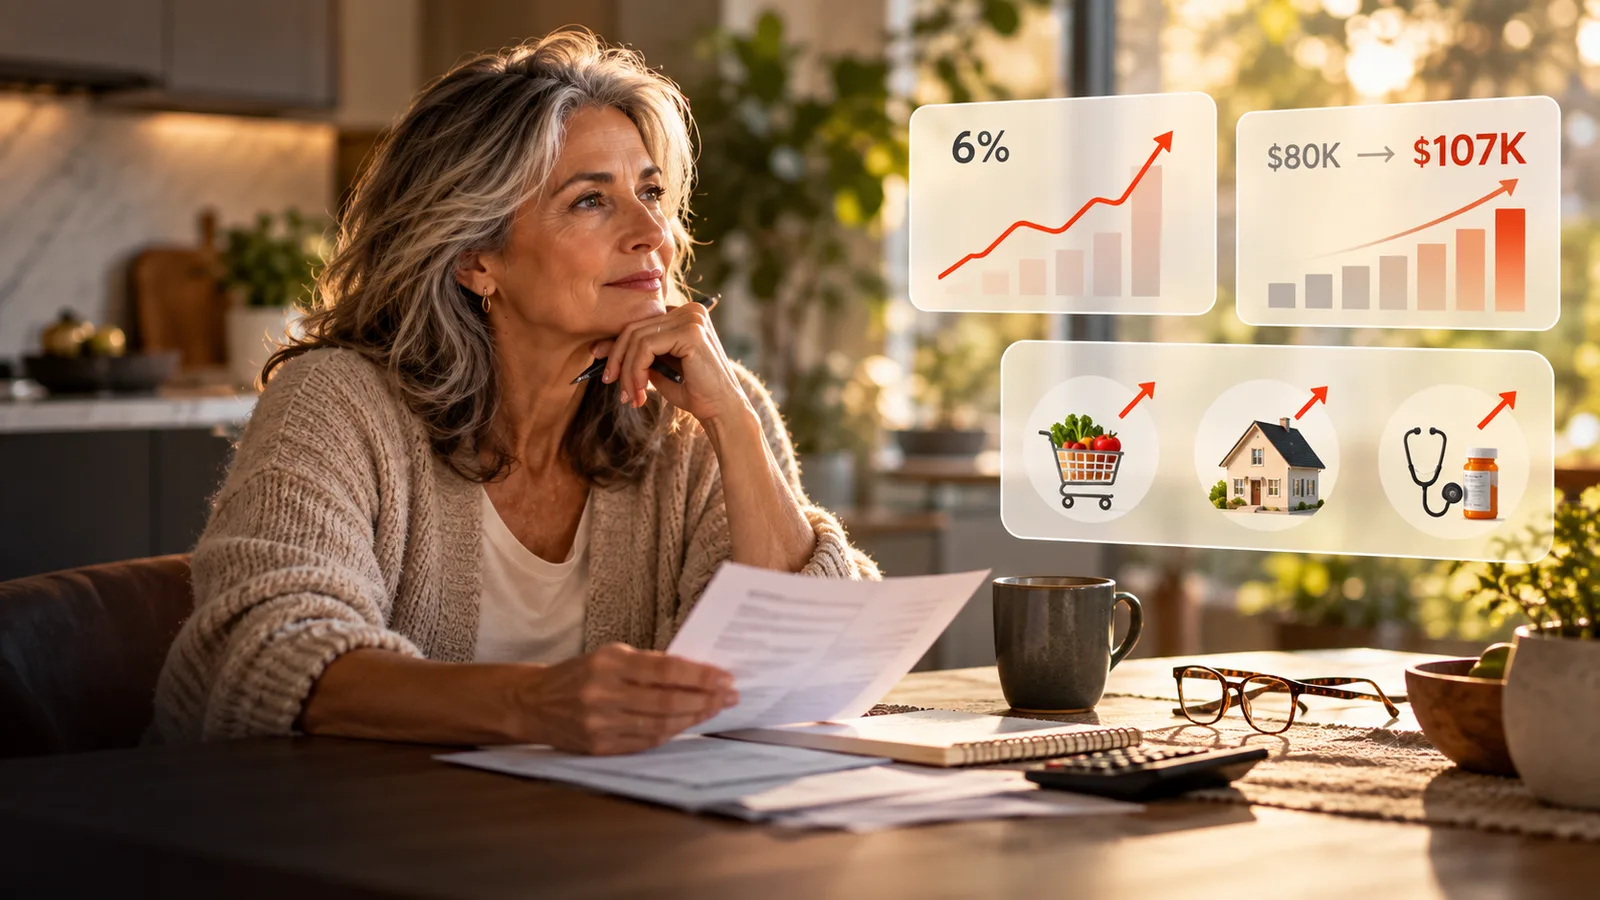
You retire at 65 with $1.6 million invested.
Your plan assumes you need about $80,000 a year to maintain your lifestyle.
Everything looks comfortable.
Then inflation refuses to cooperate.
Instead of settling back toward normal levels, it stays around 6% for five years.
Groceries cost more. Insurance costs more. Travel costs more. Home repairs cost more.
Almost everything in your budget gets more expensive at the same time.
The question is no longer just:
Can your retirement plan handle inflation?
It becomes:
If everything gets more expensive right after you retire, how much flexibility does your plan actually have?
Inflation does not necessarily mean your lifestyle changes.
It means maintaining the same lifestyle costs more.
Consider an $80,000 retirement budget.
At 2.5% annual inflation, that lifestyle would cost roughly $90,500 after five annual increases.
At 6% inflation, it would cost roughly $107,100.
By Year 5, the difference is roughly $16,500 a year.
That is where inflation becomes a retirement-planning problem rather than simply a budgeting problem.
While you are working, higher prices may be partly offset by future raises.
Retirement is different.
If spending rises faster than your retirement income, the difference may need to come from your portfolio.
That can mean larger withdrawals early in retirement—when you hoped more of your money would remain invested for later years.
But higher inflation does not force everyone into the same response.
That is where the paths start to separate.
Suppose inflation behaves roughly as expected.
Your $80,000 lifestyle still gets more expensive over time, but gradually.
Portfolio withdrawals rise more slowly.
This is the baseline your original retirement plan may have been built around.
Nothing dramatic happens.
But that baseline becomes useful because it shows how much additional pressure unusually high inflation creates.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Now assume inflation stays around 6% for five years.
You decide not to materially change your lifestyle.
If restaurants, travel, utilities, insurance, and everyday purchases become more expensive, you increase spending enough to maintain roughly the same purchasing power.
Your retirement may not feel very different.
Your withdrawals can.
An $80,000 lifestyle that would cost roughly $90,500 after five years at 2.5% inflation could cost about $107,100 at 6%.
That extra spending has to come from somewhere.
For households relying heavily on portfolio withdrawals, it can mean more money leaving the portfolio earlier than expected.
The question becomes:
How much does maintaining your lifestyle during five expensive years reduce the cushion available later?
There is another response.
Inflation still rises.
Your essential costs still become more expensive.
But instead of allowing every part of spending to rise at the same rate, you temporarily slow discretionary spending.
Maybe that means:
You are not trying to permanently shrink retirement.
You are creating temporary flexibility while prices are rising unusually fast.
Once inflation moderates, spending can be reconsidered.
The tradeoff matters.
You may preserve more portfolio flexibility.
But you gave up some lifestyle today to get it.
So the useful comparison is not simply:
Which path leaves the biggest portfolio?
It is:
How much lifestyle did you give up, and how much additional retirement resilience did that sacrifice actually buy?
| Normal Inflation | High Inflation, Keep Spending | High Inflation, Adjust Temporarily | |
|---|---|---|---|
| Inflation shock | No | Yes | Yes |
| Purchasing power maintained | Generally | Yes | Partially |
| Early withdrawals | Baseline | Highest | Potentially lower |
| Lifestyle adjustment | Minimal | Minimal | Temporary |
| Portfolio pressure | Baseline | Higher | Potentially reduced |
| Main tradeoff | Normal inflation | More money leaves the portfolio | Some spending is delayed or reduced |
The third path is not automatically better.
Someone with substantial portfolio flexibility may decide maintaining their lifestyle is exactly what their retirement savings are for.
Someone with a tighter plan may decide temporarily reducing discretionary spending is a small price for preserving more flexibility later.
The useful answer depends on the plan.
Instead of guessing how damaging five years of inflation might be, compare it against your existing retirement plan.
Compare moderate inflation with five years of much higher inflation using your own retirement plan.
Inflation runs at 2.5% for the first five years
Use a moderate inflation period as the reference point for your retirement plan.
Both paths apply the inflation assumptions to your existing retirement plan rather than the example used in this article.
Test with my planThe temporary-spending-adjustment path is worth thinking about too.
But the first question is simpler:
How much inflation can your existing retirement plan absorb before you would actually need to change your lifestyle?
That is the flexibility a retirement projection should help you understand.
Load all 2 tests from this article against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
Should you use $300,000 to buy lifetime income or keep it invested? Compare what happens at ages 75, 85, and 95.
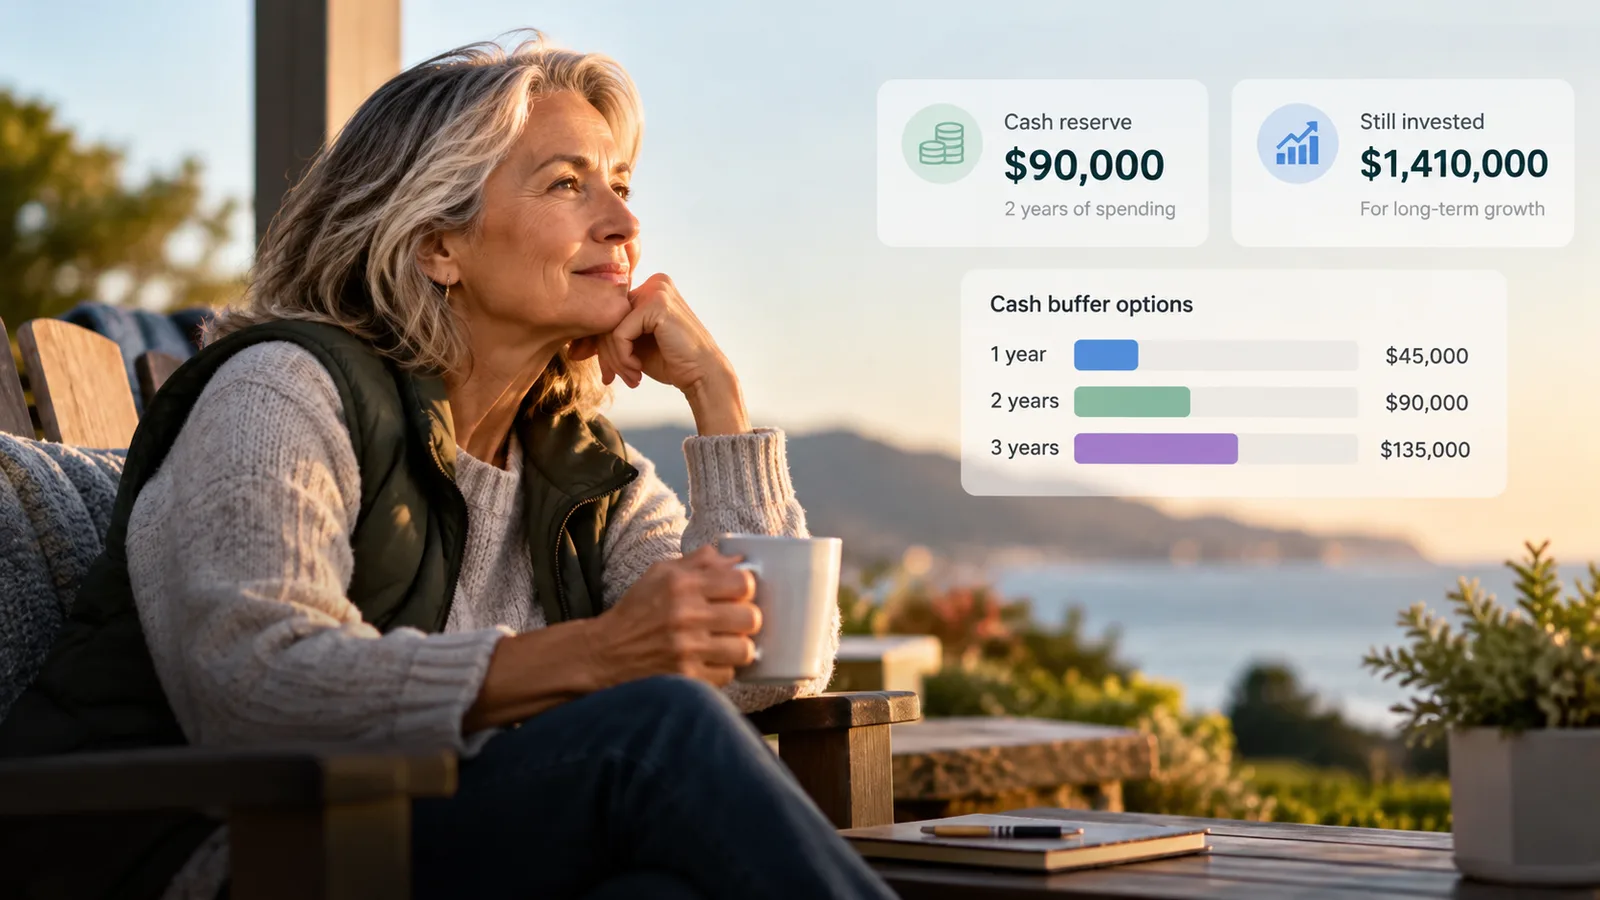
One year, two years, or three? See how keeping cash available can protect retirement spending—and what you give up by investing less.
Compare paying cash, putting 50% down, and putting 20% down on a retirement home. See how each choice changes your investments and monthly bills.
