5 min read • Published about 1 month ago
Load all 3 article strategies with your numbers before you decide.
Your retirement plan expects $4,000 a month from Social Security.
But what if you receive $3,200 instead?
That missing $800 every month doesn't automatically derail retirement. It raises a question:
Where will the difference come from?
The 2026 Social Security Trustees report projects that the retirement and survivors trust fund's reserves could run out in late 2032.
Without changes in law, ongoing income would cover about 78% of scheduled benefits.
No 20% across-the-board cut has been enacted. Congress could change the rules. We're testing a possible income shock, not predicting your future check.
Imagine you're planning for $80,000 a year in retirement cash needs, before tax effects.
You expect:
Now reduce Social Security by 20%.
Your Social Security income drops by $9,600 a year.
To maintain your lifestyle, investment withdrawals increase from $32,000 to $41,600.
That's a 30% increase in withdrawals.
Over 20 years, the missing Social Security adds up to $192,000 before inflation adjustments.
The real impact could be larger or smaller depending on investment performance, taxes, and future benefit changes.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
The question isn't simply whether Social Security gets reduced.
It's what you would do if it did.
You continue spending $80,000 annually.
Your retirement stays the same today, but your savings have to work harder.
You reduce annual spending by 10%.
Your portfolio withdrawals are now much closer to the original $32,000.
A smaller spending adjustment can absorb much of the missing income.
If you haven't retired, you could delay retirement by one year.
That may mean:
The extra year could help offset the income reduction, depending on your savings and expenses.
What happens if your Social Security benefits are 20% lower than your current estimate?
Choose a path and test it against your own retirement plan.
Compare lower benefits with different responses using your own retirement plan.
Cover the missing income from savings
Test 20% lower Social Security while keeping your retirement spending unchanged.
Tests use Social Security benefits already configured in your plan. Working longer is intended for readers who have not retired.
Try with my planWhen comparing your Future Paths, focus on three numbers:
You may discover that a 20% benefit reduction barely changes your retirement.
Or you may find that a modest adjustment today makes a meaningful difference later.
Social Security doesn't have to disappear to affect your retirement.
Even receiving a little less than expected can change how much you withdraw from savings.
A strong retirement plan isn't one that assumes everything goes right. It's one that shows you what happens when something doesn't.
Load all 3 tests from this article against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
See how a spouse's retirement savings and income can dramatically improve retirement success, with clear calculations comparing a base plan, pension, rental income, and combined household finances.
Should you use $300,000 to buy lifetime income or keep it invested? Compare what happens at ages 75, 85, and 95.
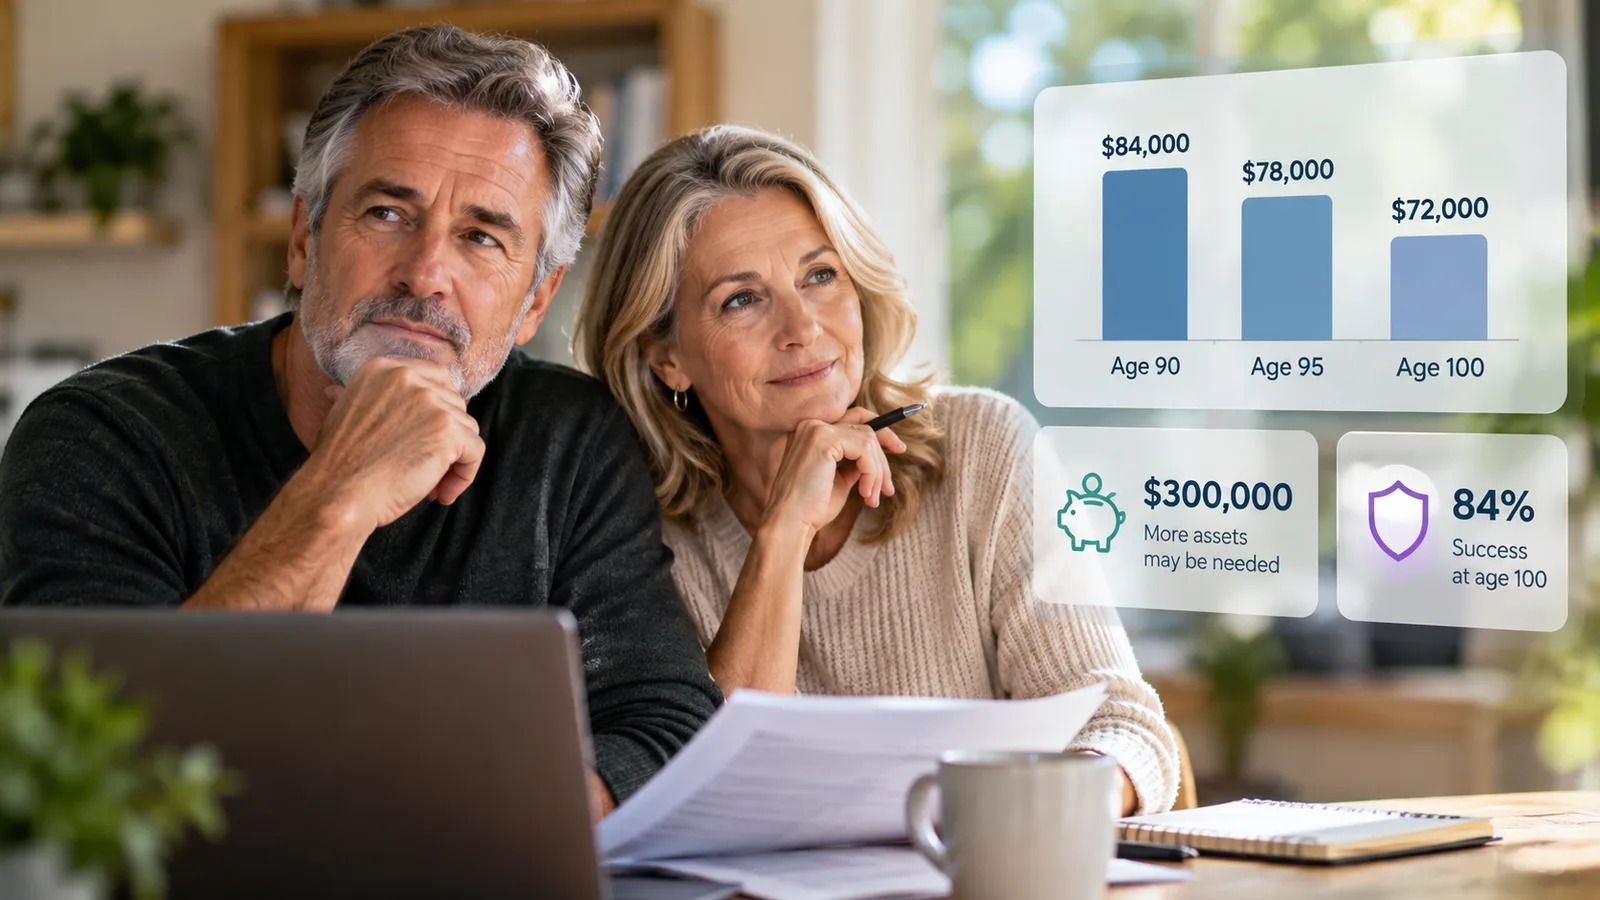
See how planning through age 90, 95, or 100 can change sustainable spending, required savings, retirement success, and the cushion left in your plan.
