5 min read • Published about 2 months ago
Load all 2 article strategies with your numbers before you decide.
Most retirement plans make one assumption that can quietly change everything:
How long does your money need to last?
Maybe your plan runs through age 90.
That can already feel conservative when you're planning retirement in your 50s or early 60s.
But what if you live to 95?
Or 100?
The important question isn't simply whether your retirement plan still “works.”
It's:
What does another 5 or 10 years of retirement actually cost?
Consider someone retiring at 62 with:
Now change only one thing:
How long the portfolio needs to last.
We can compare three Future Paths:
The longer the horizon, the more years the portfolio may need to fund spending, healthcare, inflation, and market volatility.
That doesn't automatically mean someone needs dramatically more money.
But it can change how much they can sustainably spend — and how much cushion remains.
If the plan runs through age 90, the portfolio needs to support about 28 years of retirement.
In this illustrative example:
| Metric | Plan Through 90 |
|---|---|
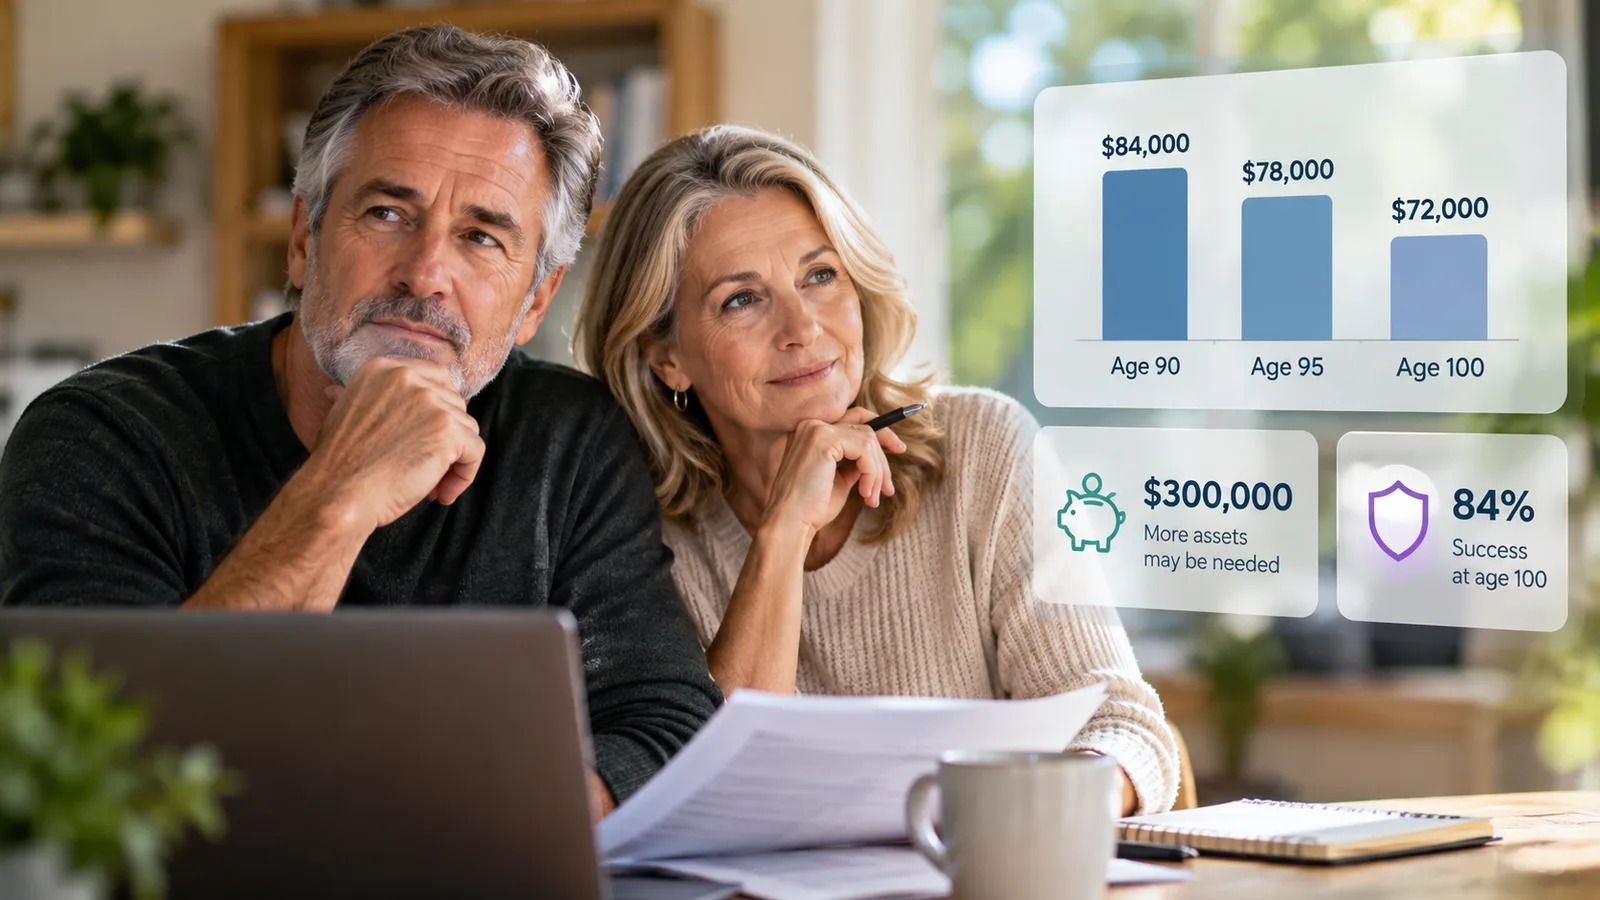
| Sustainable annual spending | ~$84,000 |
| Additional assets needed to support $80K | $0 |
| Success | 94% |
| Remaining cushion | ~$620,000 |
At this horizon, the planned $80,000 lifestyle fits comfortably inside the projection.
There is still room for weaker markets, unexpected expenses, or leaving money behind.
But age 90 is still an assumption.
Now extend the same retirement by another five years.
There are no extra contributions.
No extra starting assets.
No change to the spending goal.
The portfolio simply has to support five more years of:
The picture changes:
| Metric | Plan Through 95 |
|---|---|
| Sustainable annual spending | ~$78,000 |
| Additional assets needed to support $80K | ~$140,000 |
| Success | 90% |
| Remaining cushion | ~$420,000 |
The original plan does not suddenly collapse.
Instead, the margin gets thinner.
Planning five years longer can mean slightly lower sustainable spending today, or a need for additional savings if you want to preserve the same lifestyle and cushion.
See how your retirement plan changes when your savings need to last five additional years.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Now stretch the plan another five years.
The portfolio may need to support nearly four decades of retirement.
| Metric | Plan Through 100 |
|---|---|
| Sustainable annual spending | ~$72,000 |
| Additional assets needed to support $80K | ~$300,000 |
| Success | 84% |
| Remaining cushion | ~$220,000 |
The biggest takeaway isn't just the lower Success number.
It is the change in what the portfolio can comfortably support.
See how your retirement plan changes when your savings need to last ten additional years.
All article tests · No account neededOpens every article test in Lab. No account required until you save.In this example, adding 10 years to the retirement horizon reduces sustainable annual spending from about $84,000 to $72,000.
That's roughly $12,000 less per year.
Or look at it another way:
To maintain the original $80,000 annual lifestyle with a similar level of protection, the age-100 plan could require roughly $300,000 more at retirement.
That is the part of longevity risk that a Success percentage alone can hide.
The question isn't simply:
Does the plan still succeed?
It's also:
What do I have to give up today to make the money last longer?
A longer retirement horizon does not automatically mean you need to keep working or dramatically increase your savings.
There are several ways a plan can absorb more years.
You might:
Different households may choose completely different combinations.
That is why the question “Will I run out of money?” can be too narrow.
A better question is:
How much lifestyle and cushion am I willing to trade for protection against living longer?
Planning through age 100 does not mean you are predicting that you will live to 100.
It is simply a way to test how flexible the retirement plan really is.
If the plan still looks strong after adding another 10 years, that tells you the portfolio has meaningful room.
If the numbers change sharply, that is useful too.
It may show that:
The goal is not to perfectly guess your lifespan.
It is to understand what happens if your original assumption is wrong.
Because living longer should be good news.
Your retirement plan should be prepared for it.
Load all 2 tests from this article against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
See how a spouse's retirement savings and income can dramatically improve retirement success, with clear calculations comparing a base plan, pension, rental income, and combined household finances.
See how a smaller Social Security benefit could change your retirement withdrawals—and three ways to respond.
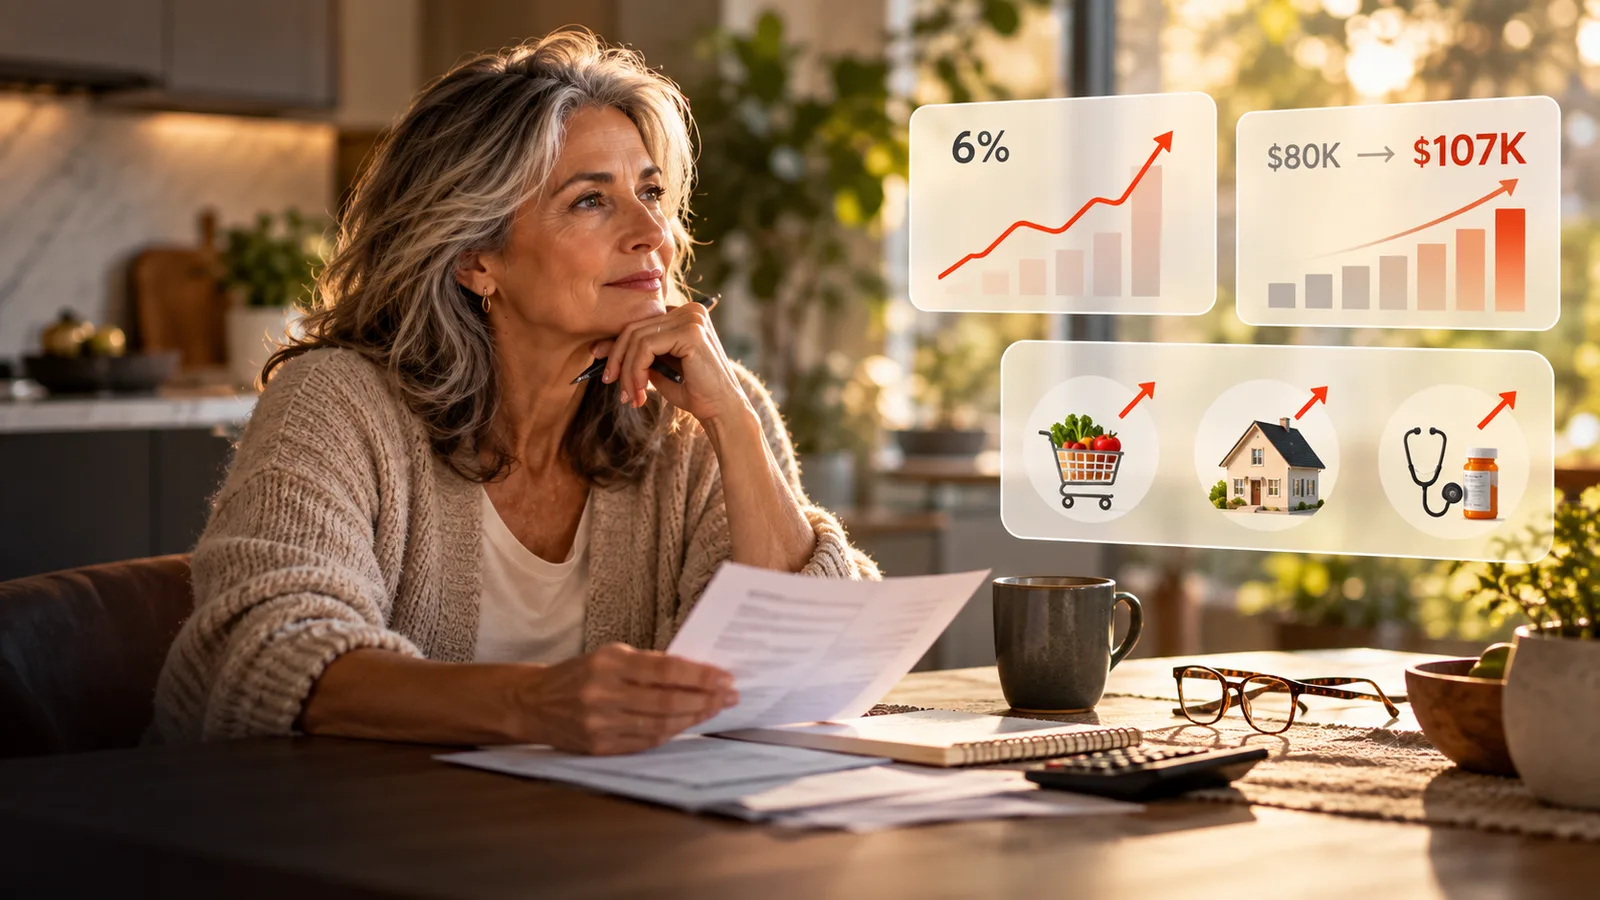
A few years of high inflation right after retirement can raise withdrawals quickly. See how maintaining your lifestyle—or temporarily adjusting it—can change the pressure on your plan.
