8 min read • Published 3 months ago • Updated Aug 20, 2026
Load all 2 article strategies with your numbers before you decide.
For some couples, money disagreements are about spending. One person wants the nicer vacation while the other wants to save. But there's another disagreement that can be much harder to resolve: you both want to save, you just don't agree on what “saving” means.
One spouse may look at $50,000 sitting safely in a bank account and feel relieved. The other may look at that same $50,000 and wonder why more of it isn't being invested for retirement. Neither person necessarily thinks they're being reckless—they're protecting against two different risks.
One fears not having enough money available today. The other fears not having enough money decades from now. If a couple never resolves that difference, time can quietly make the decision for them.
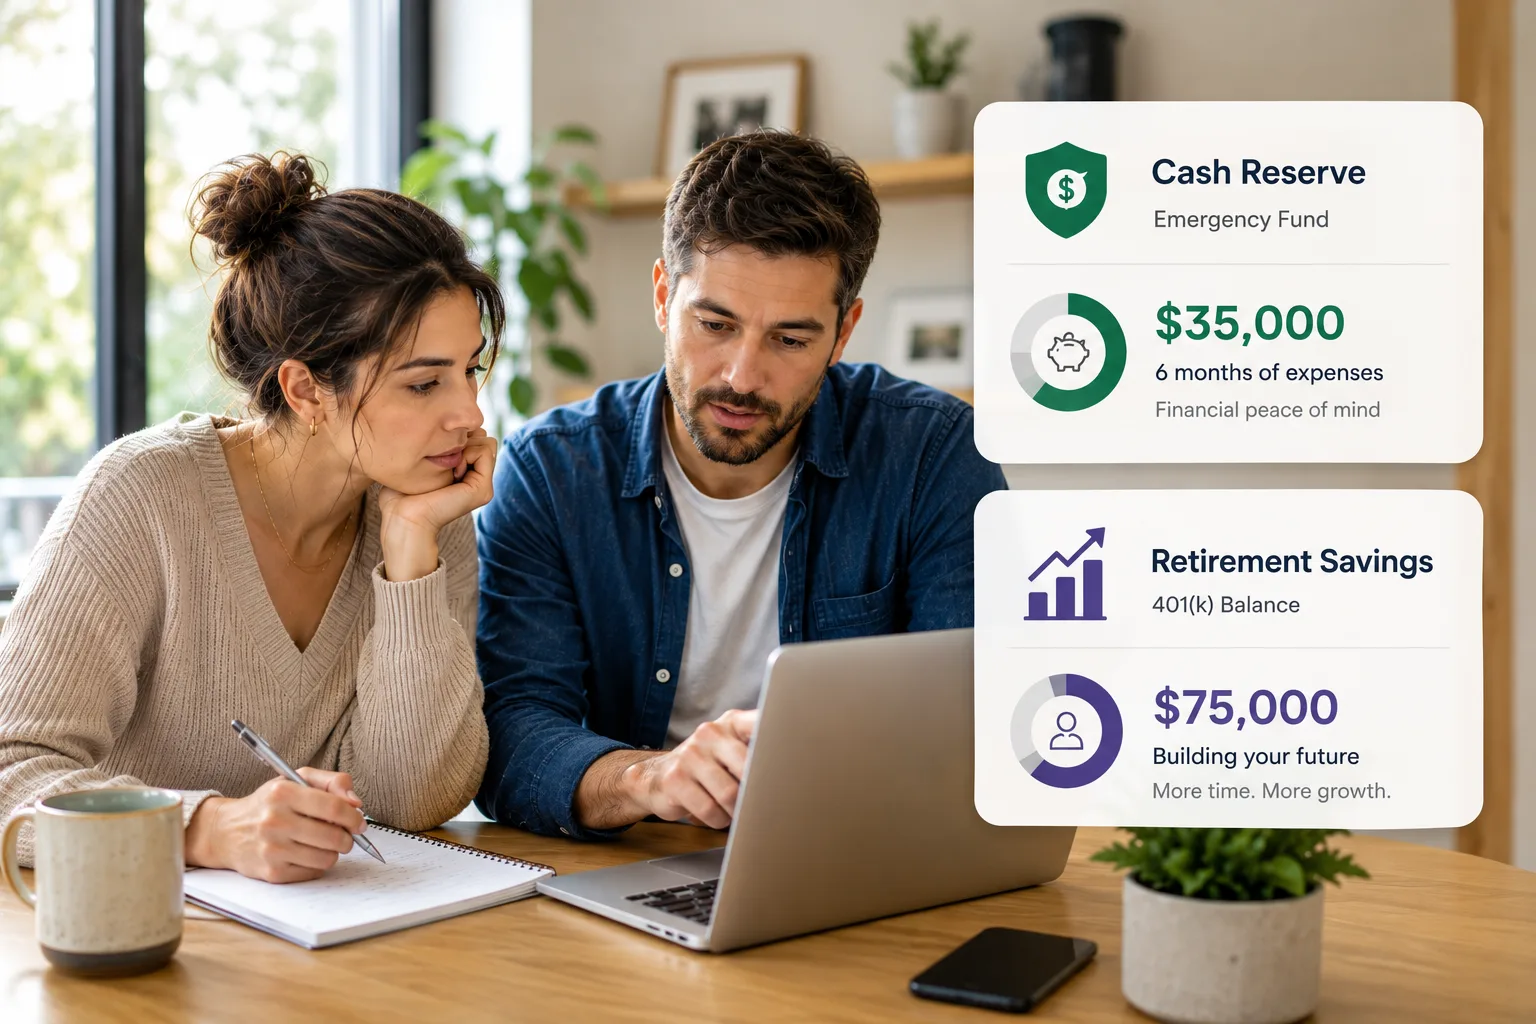
An emergency fund isn't a failed investment. It has a specific job: providing money when you lose income, need a major home repair, face an unexpected medical expense, or simply need cash quickly. That financial buffer can keep you from having to sell long-term investments at an inconvenient time.
Retirement savings have a different job. They need to help finance years—or potentially decades—when employment income is no longer supporting the household. That's why asking whether cash or a 401(k) is “better” can be the wrong question.
A more useful question is:
How much accessible cash does our household need before the next dollar should start working toward retirement?
Once that emergency reserve is established, continuing to accumulate cash indefinitely creates a different tradeoff. Inflation can reduce purchasing power over time, while investing introduces market risk but gives long-term savings an opportunity to grow.
The goal isn't to eliminate cash in favor of investing. It's to give each dollar a job.
Consider a household that has already built a reasonable cash reserve and still has money available to save each month. They could continue putting everything in the bank, split the additional savings between cash and retirement, or direct more of the long-term portion toward retirement.
| Approach | What it prioritizes | Main tradeoff |
|---|---|---|
| Cash First | Accessibility and stability | Less money exposed to long-term investment growth |
| Split the Difference | Liquidity plus retirement investing | Neither goal receives the full monthly surplus |
| Retirement First | Long-term investing after reserves are established | Greater exposure to market fluctuations and less immediate access |
There isn't one approach that automatically works for every household. A family with unstable employment, a major purchase coming soon, or very little emergency savings may reasonably need more cash. A household with substantial reserves but very little retirement savings may have a different problem.
The bigger risk is allowing “we'll figure it out later” to become the permanent strategy. A few months of waiting may not change much, but years of postponing retirement contributions can leave fewer years for those contributions to potentially grow.
A 401(k) is an employer-sponsored retirement account that can hold investments. Traditional and Roth 401(k) contributions receive different tax treatment, and some employers also offer matching contributions.
That employer match can be an important part of the decision. Depending on the plan, choosing not to participate may mean leaving employer-provided retirement dollars unused.
But the biggest advantage a younger saver has isn't necessarily a particular account or investment. It's time.
Money contributed in your 30s or 40s has years to potentially earn returns. Waiting until your 50s doesn't make retirement impossible, but there are fewer years remaining for contributions and investment growth to do the work.
A household that waits may eventually have to compensate in other ways: contribute more, spend less in retirement, retire later, or use some combination of all three.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Suppose you and your spouse agree that the household may be behind but disagree about putting more money toward retirement. There isn't only one way to improve the plan.
You could increase retirement contributions now. Or you could keep contributions closer to their current level and give the portfolio more time by retiring later.
Rather than debating which sounds better, compare both choices against the retirement plan you already have.
Compare two ways to give your retirement plan more room.
Put more toward retirement now
Increase your annual retirement contributions by 4% and see how your outlook changes.
Each option starts from your existing Nestly plan so you can compare the change against your current path.
Try with my planThis turns an emotional disagreement into something more concrete. Instead of “you don't understand retirement accounts” versus “I don't trust investing,” the conversation can become: “Here is where we're currently headed. What change are we comfortable making?”
The answer may still involve compromise. But now the couple can see what that compromise could mean for their retirement rather than arguing only about which financial philosophy feels safer.
Imagine one spouse is eight years older. It can be tempting to assume the younger spouse's paycheck creates an eight-year cushion when the older spouse retires, but retirement isn't only about the first person leaving work.
Eventually the household may need to support two people without two employment paychecks. A useful plan should therefore look at what happens when the older spouse retires, what happens when the younger spouse eventually retires, and how the household's income sources change between those dates.
There's another question couples sometimes overlook: Would either spouse still have enough financial resources if they eventually had to manage retirement alone?
Retirement isn't just a joint finish line. A resilient plan should consider the financial security of each spouse as well as the household together.
Someone who grew up watching a parent struggle to pay bills may see cash in the bank as security. Someone who grew up hearing about retirement accounts and investing may see not investing enough as the bigger risk.
Those experiences don't disappear because a spreadsheet says one approach may produce a stronger long-term outcome. Dismissing one person's definition of safety probably won't produce a better household plan—but avoiding the conversation isn't a strategy either.
A couple can recognize the emotional value of cash and calculate what their long-term retirement plan requires. That might mean agreeing on a specific emergency-fund target first, then deciding where additional savings should go once that target is reached.
If an employer offers a retirement match, include that in the discussion. If increasing contributions isn't realistic, test what retiring later or changing future spending would mean instead.
The goal is to turn an unlimited disagreement into a set of measurable choices.
A household doesn't have to put every available dollar into the market, and it doesn't have to keep every dollar in cash to feel secure. There is a large middle ground between those extremes.
But retirement has one characteristic that makes prolonged indecision especially important: you can't go back and recover the years that have already passed.
You can contribute more later. You can work longer. You can change your retirement target. What you can't do is give today's money another ten years after those ten years are gone.
So if you and your spouse disagree about retirement savings, the goal doesn't have to be proving who understands money better. Start with two questions:
How much cash would make us feel secure today?
Once we have it, what does our future require from the money that's left?
That may be a much more productive retirement conversation than trying to decide who is right.
Load all 2 tests from this article against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
