6 min read • Published 3 months ago
RMD stands for Required Minimum Distribution.
It is the minimum amount you generally must withdraw each year from certain tax-deferred retirement accounts once the RMD rules apply to you.
Think of it this way:
You may have spent decades putting money into accounts like a traditional IRA or 401(k).
You often received tax advantages while saving.
The money then grew tax-deferred.
Eventually, the IRS requires some of that money to come out.
That required withdrawal is your RMD.
Traditional retirement accounts can allow you to postpone income taxes for many years.
For example:
RMD rules prevent tax-deferred retirement money from remaining untouched forever.
Once the rules apply, you generally must begin withdrawing at least a minimum amount each year.
The money is still yours.
The important difference is that taxable distributions from traditional retirement accounts generally become part of your taxable income.
RMD rules generally apply to tax-deferred retirement accounts such as:
Roth IRAs generally do not require lifetime RMDs for the original account owner.
That difference becomes important later in retirement and tax planning.
Under current federal law, the applicable RMD age depends on your date of birth.
For many people reaching RMD age now, the applicable age is 73.
SECURE 2.0 also increases the applicable age to 75 for certain younger birth-year groups. oai_citation:0‡IRS
For traditional IRAs, your first RMD is generally due by April 1 of the year after the year in which you reach your applicable RMD age.
After that, annual RMDs are generally due by December 31. oai_citation:1‡IRS
One important wrinkle:
If you delay your first RMD until the following April, you may end up taking your first and second RMDs in the same calendar year.
That can increase taxable income for that year.
For some workplace retirement plans, RMD timing may be based on the later of:
if the plan allows the delay.
Traditional IRAs generally do not receive that same still-working exception. oai_citation:2‡IRS
The exact rules depend on the account and plan.
The basic calculation is simple:
Prior December 31 account balance
divided by
IRS life-expectancy factor
equals
Required Minimum Distribution
The IRS publishes the life-expectancy factors used in the calculation. For many account owners, the Uniform Lifetime Table is used. oai_citation:3‡IRS
Suppose you are 75 years old.
Your traditional IRA was worth:
$1,000,000
on December 31 of the previous year.
At age 75, the current Uniform Lifetime Table factor is 24.6. oai_citation:4‡IRS
The calculation is:
$1,000,000 ÷ 24.6
which equals approximately:
$40,650
So your RMD for that year would be about:
$40,650
You can withdraw more if you want.
But generally, you cannot withdraw less than the required amount without potentially creating an RMD shortfall.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Using the same age-75 factor of 24.6, here is what different traditional retirement balances could produce.
| Prior Year-End Balance | Approximate RMD at Age 75 |
|---|---|
| $250,000 | $10,163 |
| $500,000 | $20,325 |
| $750,000 | $30,488 |
| $1,000,000 | $40,650 |
| $1,500,000 | $60,976 |
| $2,000,000 | $81,301 |
These examples are simplified.
Your actual RMD depends on:
But the table makes one thing clear:
The larger the tax-deferred balance, the larger the required withdrawal may become.
No.
An RMD means you must generally withdraw the required amount from the retirement account.
It does not mean you have to spend all of it.
For example, if your RMD is:
$40,650
but you only need:
$25,000
for living expenses, you could potentially use the remaining money for other purposes after the distribution, such as saving or investing it in a taxable account.
The key point is that the required amount must leave the tax-deferred account.
Yes.
The RMD is a minimum.
You may withdraw more.
But withdrawing extra this year generally does not reduce the RMD you must take in a future year.
The IRS calculates each year's RMD separately. oai_citation:5‡IRS
For example:
If your RMD is:
$40,000
and you withdraw:
$60,000
the extra $20,000 generally does not count toward next year's RMD.
Robert is 65.
He recently retired.
| Item | Amount |
|---|---|
| Traditional 401(k) and IRA | $1.2M |
| Roth accounts | $150,000 |
| Taxable savings | $250,000 |
| Retirement spending | $70,000/year |
| Social Security plan | Delay until 70 |
| RMDs | Not started |
Robert looks at his traditional retirement accounts and thinks:
"I don't need that money yet. Why not just leave it invested?"
Before RMDs begin, that may be possible.
But the balance may continue growing.
If Robert eventually reaches his RMD years with a much larger traditional account, his required withdrawals could also be larger.
That is where RMDs begin to affect retirement planning.
Imagine Robert's $1.2 million traditional balance grows substantially before his RMDs begin.
His future RMD is not calculated from today's $1.2 million.
It is calculated from the relevant prior year-end balance at that time.
So if his traditional balance eventually reaches:
$2 million
his required withdrawal could be much larger than if the account remained closer to $1 million.
That does not necessarily mean growth is bad.
It means a growing tax-deferred account can eventually create larger taxable distributions.
RMDs themselves are not a problem.
The issue is how they fit with everything else in retirement.
A retiree may eventually receive income from:
Once those sources begin stacking together, taxable income can look very different from the early years of retirement.
That is the subject of the next article in this series.
Important: This article is for educational purposes only and is not individualized tax, legal, investment, or retirement advice. RMD rules vary by account type and personal circumstances and can change over time. Verify current IRS rules and consider qualified tax or financial professionals before making retirement-account decisions.
Start from your current plan, change one assumption from the article, and save the version only if it is worth comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
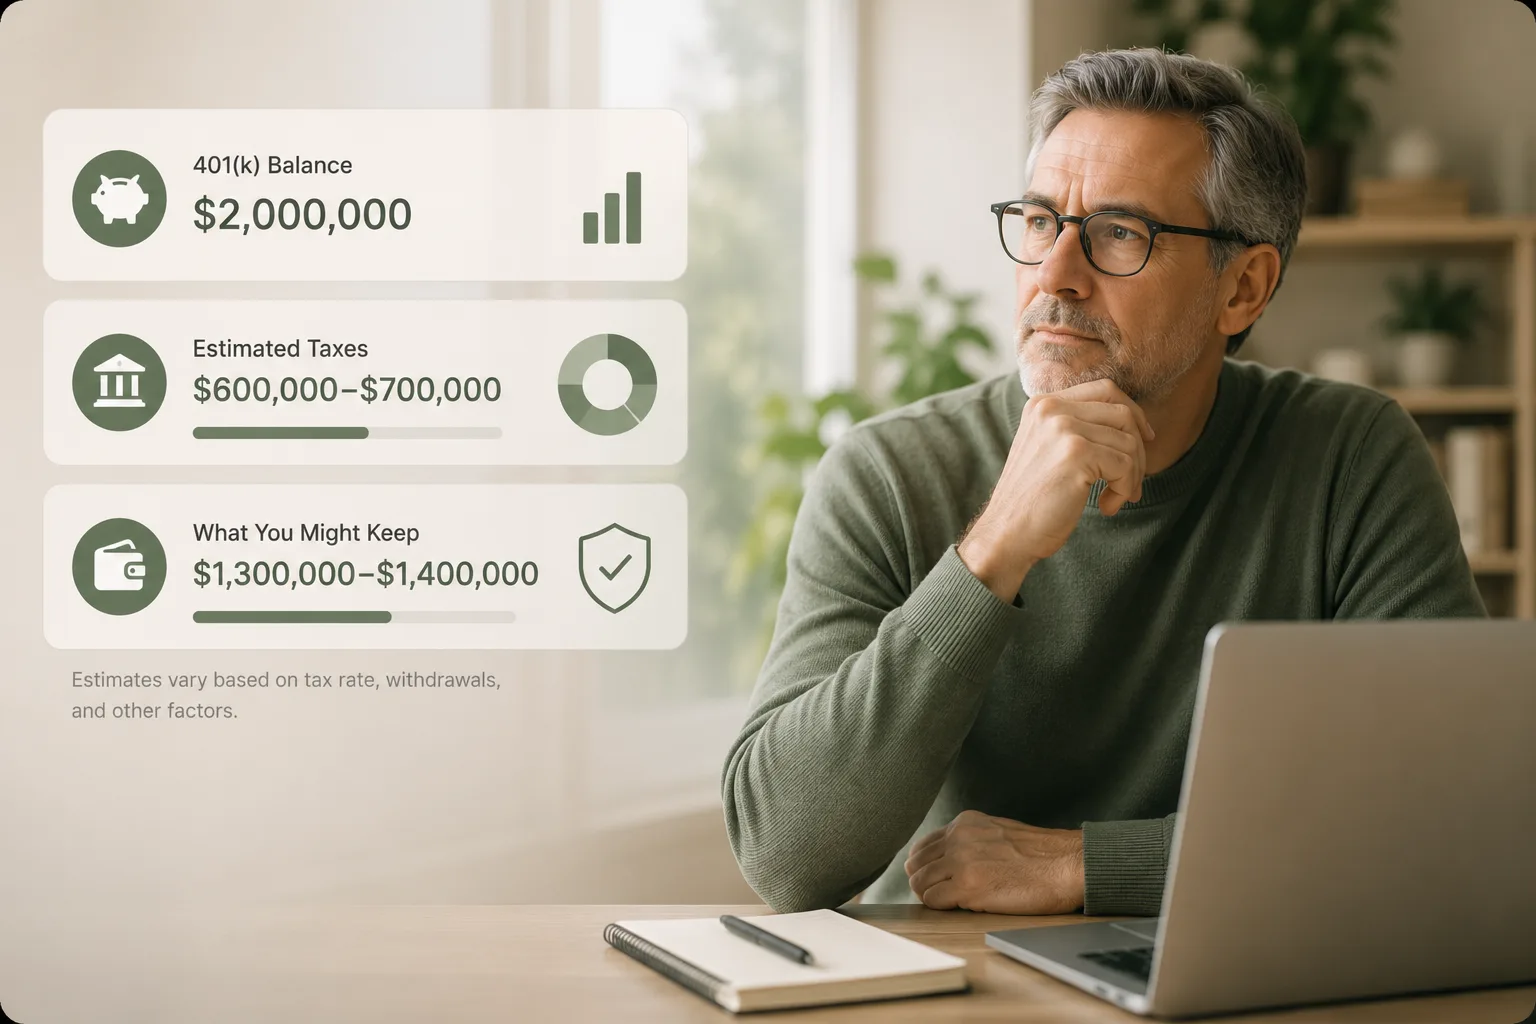
Two retirees can both have $2 million and still have very different amounts available to spend. See why Traditional, Roth, and taxable account balances matter in retirement.
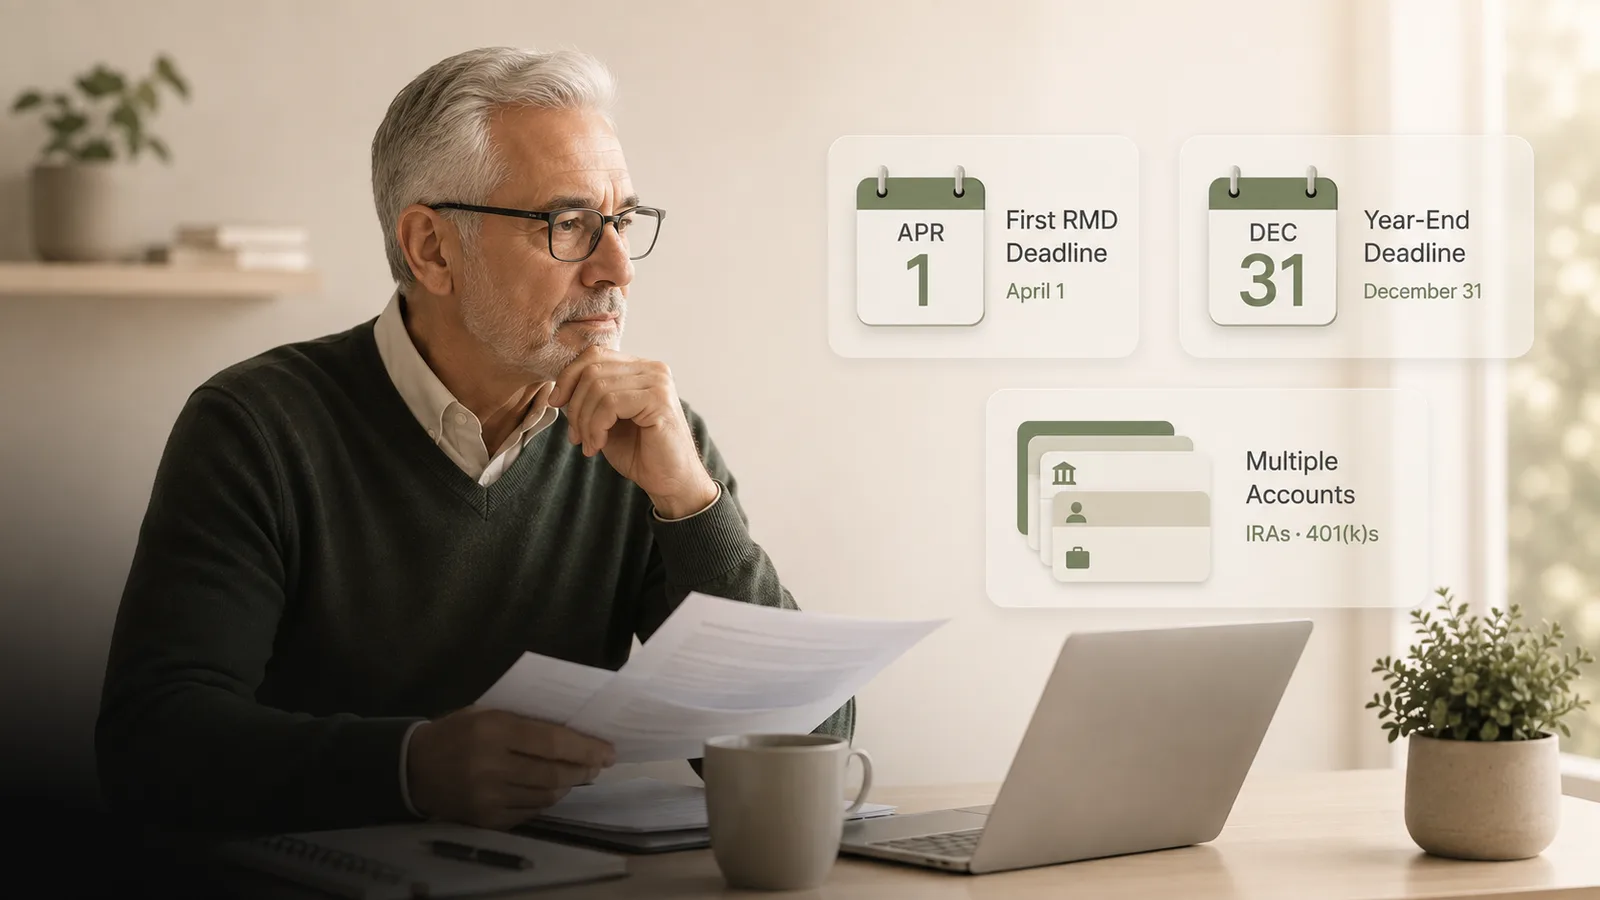
Learn what happens when Required Minimum Distributions begin, how the first-year deadline works, how multiple IRAs and 401(k)s are handled, and what to avoid before your first RMD.
Compare investing more for retirement with paying off your mortgage early. See how interest rates, employer matches, taxes, retirement timing, and risk can change the answer.
