5 min read • Published 2 months ago
Load this article strategy with your numbers before you decide.
For years, the goal is simple:
Save more. Invest more. Don’t fall behind.
But eventually, the question can change.
Do I still need to sacrifice this much today to make retirement work?
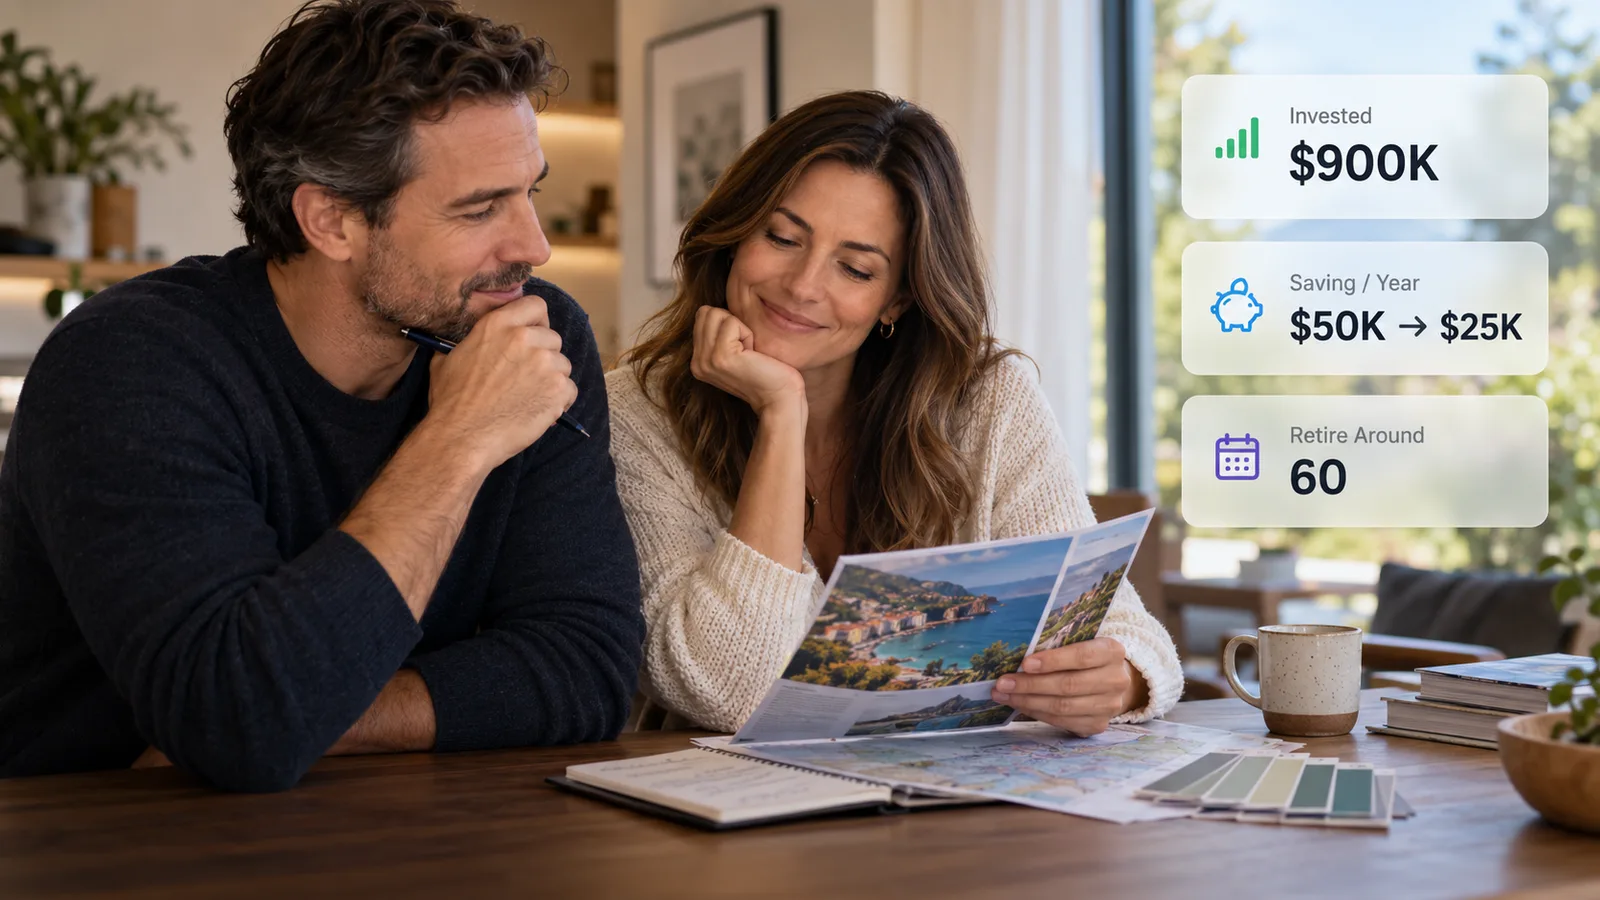
Consider someone who is 40:
They have 20 years until retirement and already have a substantial portfolio.
Now there are three possible paths.
Continue investing $50,000 a year.
This should create the largest retirement portfolio and strongest cushion.
But it also means continuing to direct $50,000 toward the future every year.
Reduce investing to $25,000 a year.
The existing $900K keeps compounding, and retirement contributions continue.
But now $25,000 a year becomes available for life today.
Contribute mainly enough to capture the employer match.
The existing portfolio does much more of the work.
That creates the most flexibility now, but leaves less protection if markets disappoint, spending rises, or retirement comes earlier.
| Keep Pushing | Ease Off | Coast More | |
|---|---|---|---|
| Annual investing | $50,000 | $25,000 | Employer match |
| Money freed today | $0 | $25,000/year | Highest |
| Retirement cushion | Highest | Strong | Lower |
| Lifestyle flexibility | Lowest | Higher | Highest |
Saving less does not have to mean spending carelessly.
An extra $25,000 could be used intentionally.
For example:
Over 20 years, reducing contributions by $25,000 creates $500,000 of additional pre-retirement cash flow before considering investment returns.
That is a meaningful amount of life between age 40 and 60.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Imagine Nestly compares the paths and shows:
Keep Pushing → 98% Success
Ease Off → 95% Success
Keep Pushing is technically stronger.
But now the real question becomes:
Is another $1 million at age 90 worth giving up $25,000 every year in your 40s and 50s?
Maybe it is.
Perhaps you want to retire earlier.
Maybe you want to leave a large inheritance.
Maybe having a very large safety margin helps you sleep better.
Those are all valid reasons.
But the biggest ending portfolio should not automatically be considered the winner.
Early in your investing life, contributions may be necessary to make retirement possible.
Later, additional contributions may mostly buy more protection around a retirement that already works.
That is an important difference.
When deciding whether to save less, compare more than one number.
Success
Does the retirement plan still work?
Retirement age
Would saving less force you to work longer?
P10 outcome
What happens if markets are disappointing?
Median portfolio
How much might still remain in a more typical outcome?
Money available before retirement
What do you gain by using some of the money now?
If cutting contributions makes the plan noticeably weaker, continuing to save aggressively may be worth it.
But if very little changes, the decision becomes more interesting.
What happens if you cut your current retirement contributions in half?
Instead of automatically assuming less saving is bad, compare what actually changes in your plan:
Money today → Success → retirement age → P10 → median portfolio
See what happens to your retirement plan if you cut your current annual contributions in half.
All article tests · No account neededOpens every article test in Lab. No account required until you save.If Success remains strong, retirement age barely moves, and the downside outcome is still comfortable, you may already have enough momentum.
At that point, the goal does not have to be:
How big can I make my retirement portfolio?
It can become:
How much future security do I actually need — and how much of my money should I enjoy before retirement?
Load "Save 50% Less" against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
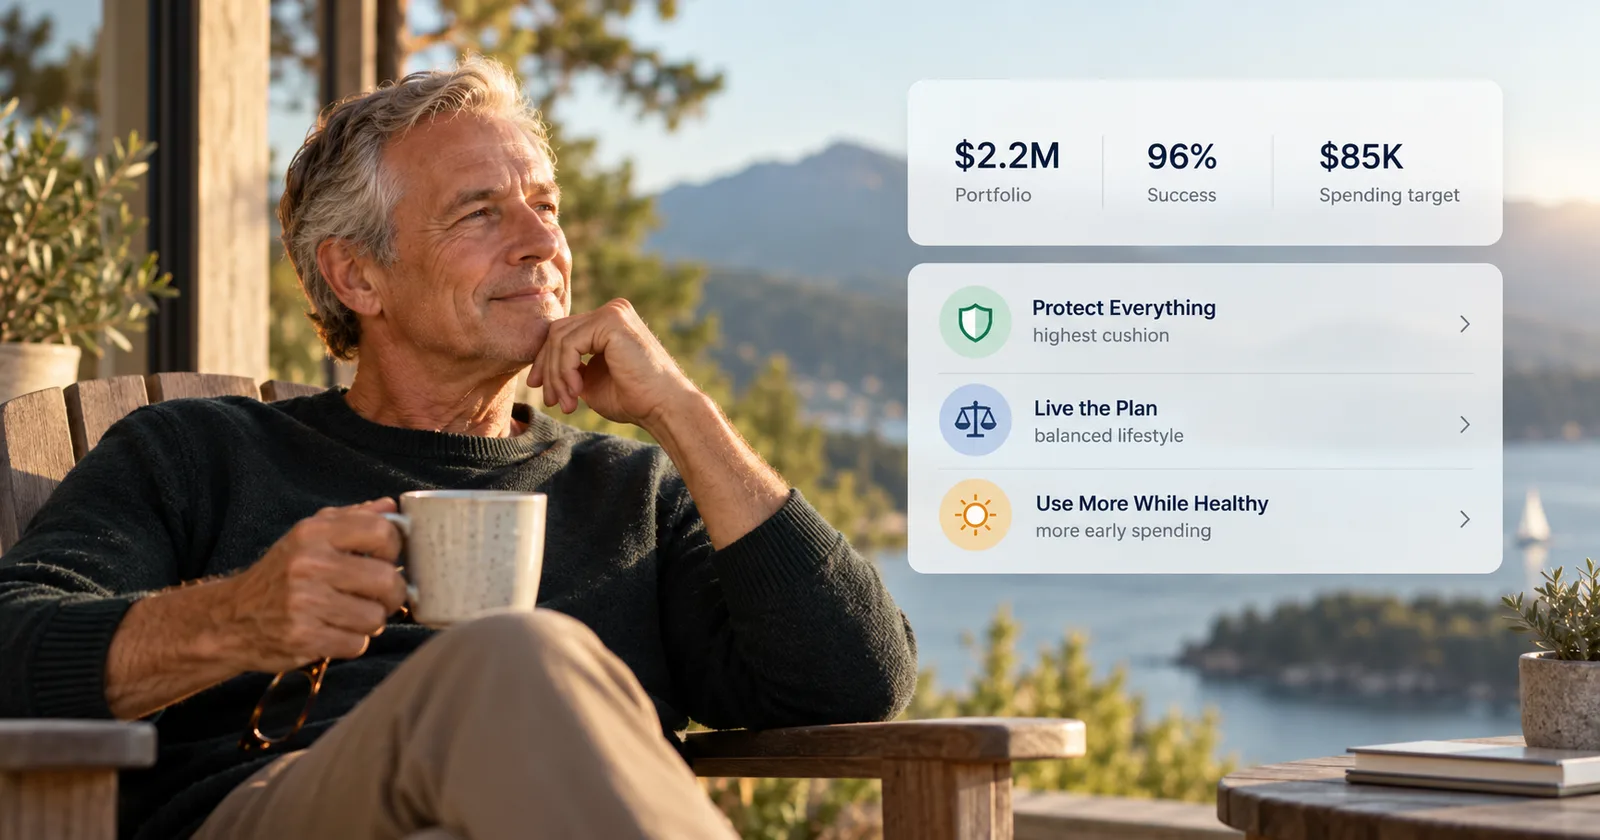
Your retirement plan already works. At some point, the question may stop being whether you have enough and become what the extra money is actually for.
Should you use $300,000 to buy lifetime income or keep it invested? Compare what happens at ages 75, 85, and 95.
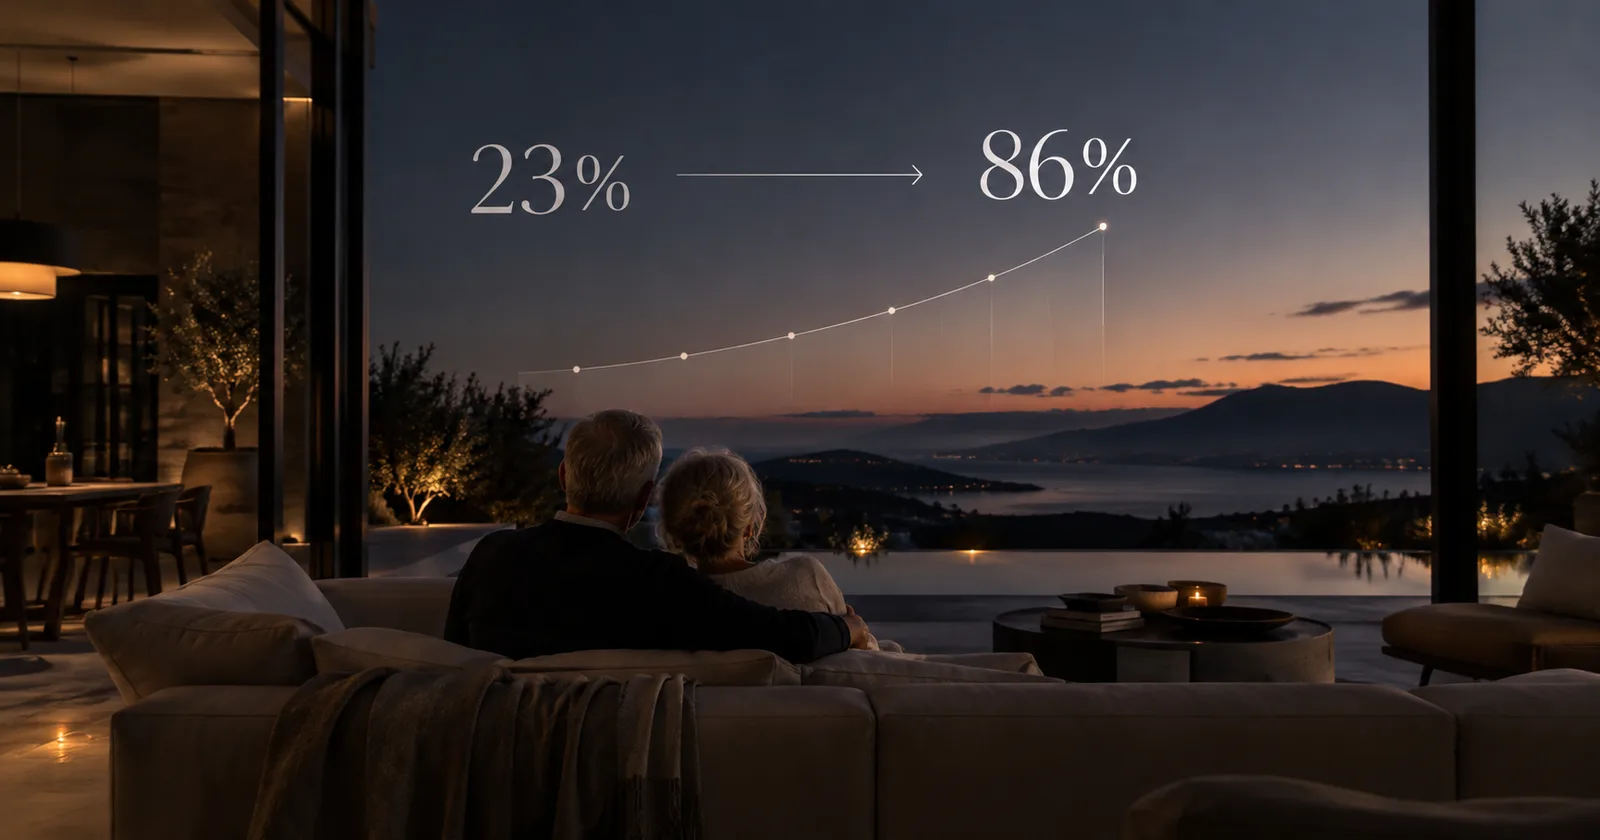
See how a spouse's retirement savings and income can dramatically improve retirement success, with clear calculations comparing a base plan, pension, rental income, and combined household finances.
