4 min read • Published about 2 months ago
You spent years putting money into your Roth.
Now you're retired.
So when are you actually supposed to spend it?
A lot of people assume the answer is:
Save the Roth until last.
That can make sense.
But Roth money can also be useful much earlier.
The reason is simple:
Qualified Roth withdrawals are generally tax-free.
That makes your Roth more than just an account to leave untouched.
It can also be a tax-flexibility tool.
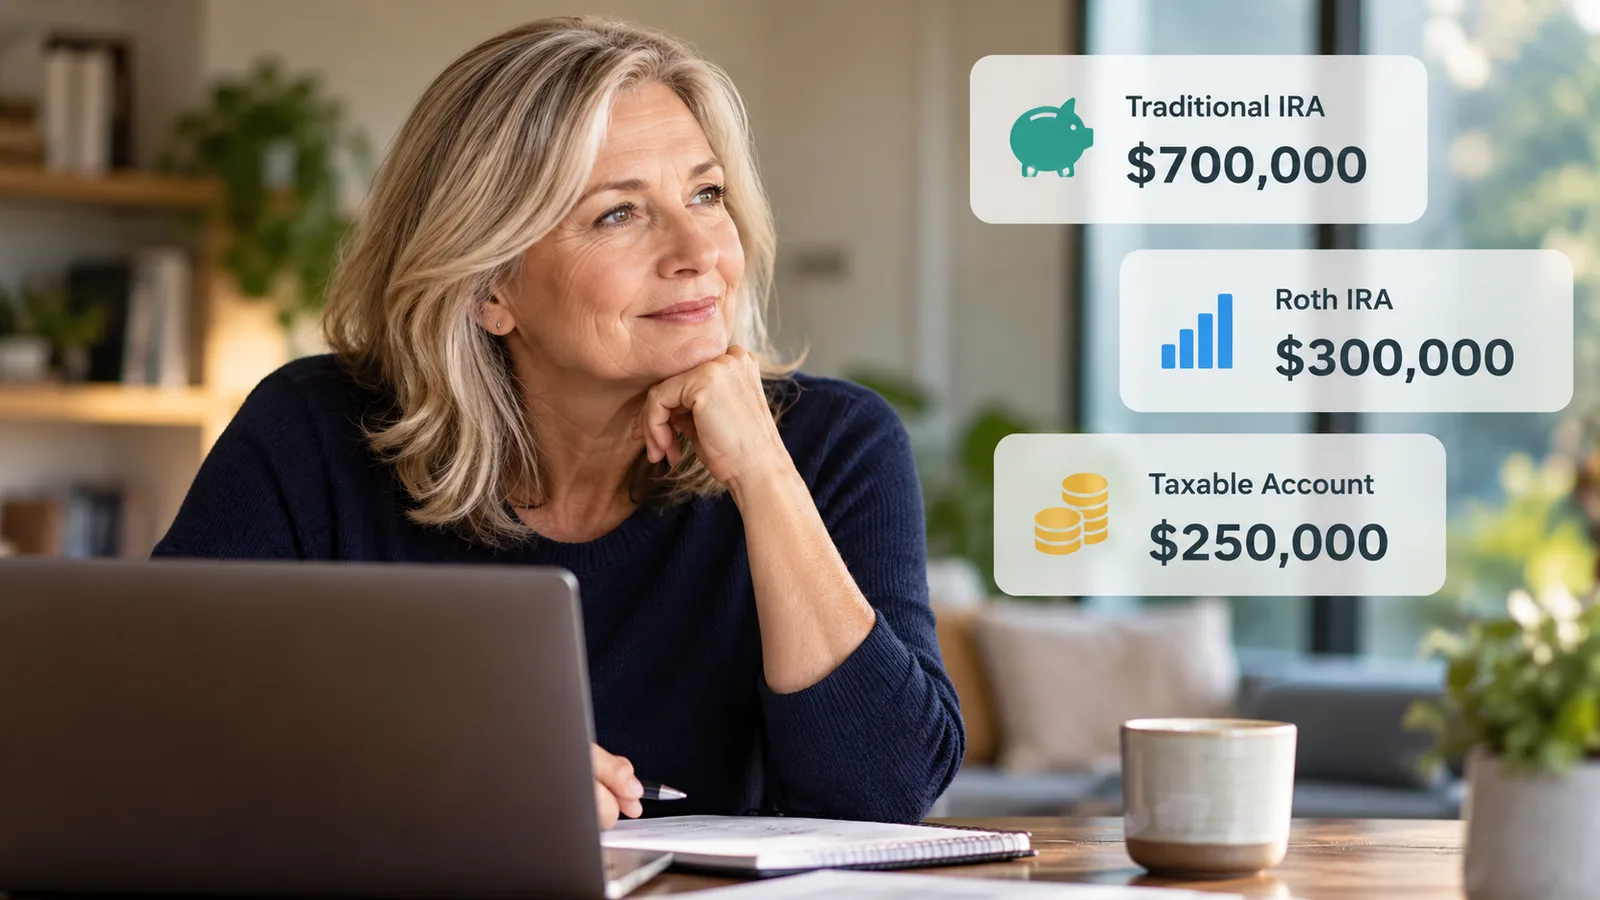
Say you're 68 and retired.
You have:
You need $90,000 total to support your lifestyle.
After Social Security, you still need another $55,000.
You could take the entire $55,000 from your Traditional IRA.
But Traditional IRA withdrawals are generally taxable.
Or you could mix where the money comes from.
In this example:
The important part isn't the exact numbers.
It's that you don't have to fund every extra dollar from the same account.
Retirement spending isn't perfectly smooth.
One year you might spend $80,000.
Then you need an extra:
Taking all of that extra money from a Traditional IRA could increase your taxable income.
A qualified Roth withdrawal may let you cover part of the expense without adding the Roth withdrawal to taxable income.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Imagine your Social Security, pension and Traditional IRA withdrawals already cover most of your normal spending.
Then you suddenly need another $15,000.
Instead of automatically taking another $15,000 from your Traditional IRA, you can ask:
Where should the next $15,000 come from?
That's where having multiple account types becomes valuable.
Because the Roth has another important advantage:
You generally don't have to take lifetime required minimum distributions from your own Roth accounts under current rules.
That gives you flexibility.
You can leave that money invested when you don't need it.
Traditional retirement accounts may eventually require distributions.
So there can be real value in preserving some Roth money for later.
| Account | Simple role |
|---|---|
| Taxable | Flexible spending source |
| Traditional | Retirement income, but withdrawals are generally taxable |
| Roth | Potentially tax-free spending flexibility |
You don't necessarily have to empty one bucket before touching the next.
Sometimes using money from more than one account can give you more control.
There are also plenty of years when spending Roth money may not be necessary.
For example:
In those years, leaving the Roth invested may make sense.
Instead of asking:
When should I finally spend my Roth?
Ask:
When is my Roth the most useful place to get my next dollar?
Sometimes the answer may be not this year.
But during a major spending year, or when another Traditional withdrawal would create more taxable income, Roth money can become especially useful.
That's why retirement withdrawal planning isn't only about deciding:
Taxable first. Traditional second. Roth last.
It's about deciding:
Which account should fund the next dollar you need?
Start from your current plan, change one assumption from the article, and save the version only if it is worth comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
You need $75,000 this year. See how pulling it from taxable, Traditional, or a mix of accounts can change taxes, future RMDs, Roth savings, and the years ahead.
Should you use $300,000 to buy lifetime income or keep it invested? Compare what happens at ages 75, 85, and 95.
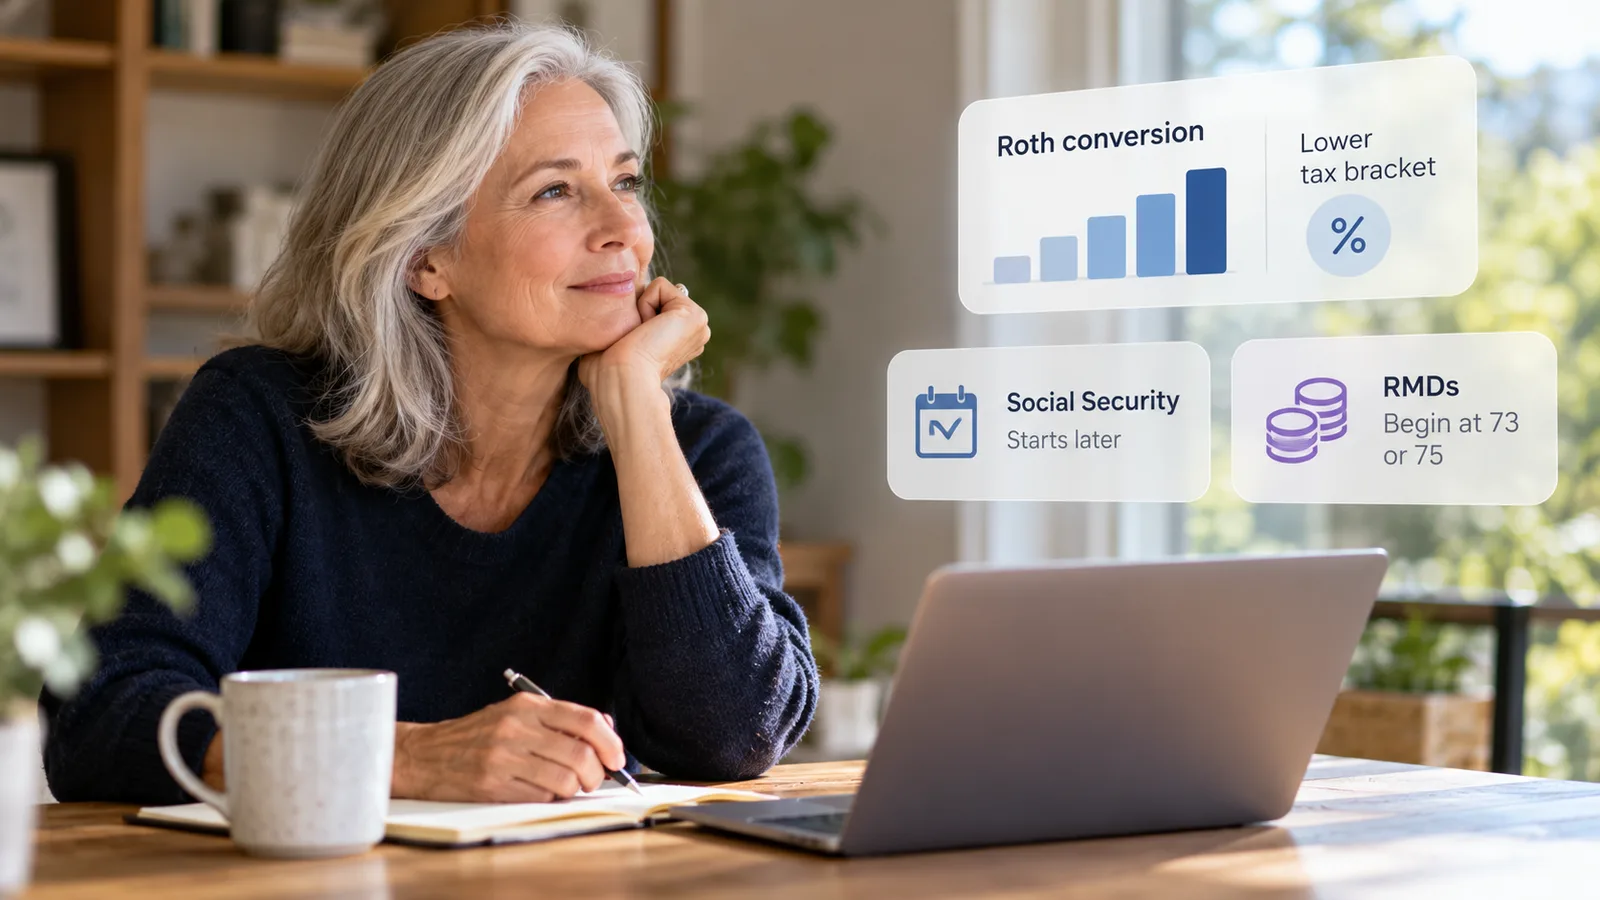
The years after your paycheck stops—but before Social Security and RMDs fully kick in—can create a valuable window for Roth conversions.
