9 min read • Published about 2 months ago
You spent decades figuring out where to put your money.
Your 401(k). Your Roth. Your brokerage account.
Then retirement arrives, and the question flips:
Which account should you actually spend from first?
Imagine you’re 65 and recently retired.
You have $1.8 million invested:
You haven’t started Social Security yet.
And this year, you need $75,000 from your portfolio to cover your lifestyle.
The obvious assumption is that $75,000 is $75,000.
But where that money comes from can matter.
A taxable withdrawal may create capital gains.
A Traditional withdrawal may create ordinary taxable income.
A qualified Roth withdrawal may generally be tax-free.
And every dollar you remove from one account is a dollar that is no longer sitting there for later.
That means the choice you make this year can affect more than this year’s tax bill.
It can change:
So instead of asking:
“How do I withdraw $75,000?”
A better question is:
“Which account should fund the $75,000?”
And there isn’t one answer that works for everyone.
The spending target does not change.
You still need $75,000 this year.
What changes is the account you use to fund it.
Use your brokerage account for most or all of the $75,000.
The appeal is straightforward: you preserve your retirement accounts and avoid taking a large Traditional withdrawal right away.
Depending on what you sell, part of the withdrawal may be your original cost basis and part may be capital gains.
That can make this path relatively tax-efficient in some years.
But there is a tradeoff.
If you leave a large Traditional balance untouched for many years, that account may continue growing — which can mean larger taxable withdrawals later and potentially larger required minimum distributions once they apply.
Take more of the $75,000 from your 401(k) or Traditional IRA.
That creates more taxable income today.
At first, that may seem less attractive.
But early retirement can sometimes create a lower-income window before Social Security, pensions, or required distributions begin.
Using part of the Traditional balance during those years may reduce how much remains in the account later.
That could mean smaller future required distributions and more flexibility over taxable income in later retirement.
Instead of relying on one account, combine withdrawals.
For example:
The goal is not simply to minimize taxes this year.
It is to balance taxes across many years while preserving flexibility.
A blended strategy may help prevent one account from becoming disproportionately large while keeping Roth assets available for future years when tax-free withdrawals could be especially useful.
| What changes? | Taxable First | Traditional First | Blended Strategy |
|---|---|---|---|
| Current taxable income | May be lower | May be higher | More controlled |
| Traditional balance later | Usually stays larger | Can shrink sooner | Reduced gradually |
| Future RMD exposure | May be higher | May be lower | Can be managed over time |
| Roth balance | Often preserved | Often preserved | Usually preserved strategically |
| Flexibility later | Depends on remaining taxable assets | Depends on future tax brackets | Often spread across account types |
| Main focus | Lower near-term tax impact | Reduce future Traditional balance | Balance taxes across years |
None of these paths automatically wins.
The lowest tax bill this year is not necessarily the lowest tax bill over retirement.
And the path that leaves the largest account balance is not always the path that leaves the most money available to spend after taxes.
A retirement withdrawal does more than pay this year’s bills.
It also changes what stays invested for later.
If you spend from your taxable brokerage account first, more of your Traditional and Roth money may remain invested.
If you withdraw from Traditional accounts earlier, you may pay more income tax today — but you also reduce the balance that could eventually create larger required minimum distributions.
If you preserve Roth assets, you keep a pool of money that can potentially be withdrawn tax-free later.
So the decision is not simply:
Where can I get $75,000 today?
It is:
What happens to the rest of my retirement after I choose where that $75,000 comes from?
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Imagine the Taxable First path creates the smallest tax bill at age 65.
That sounds good.
But if your $900,000 Traditional balance stays mostly untouched for years, it may continue growing.
Later, required distributions could begin pulling money out whether you need that much for spending or not.
Now compare that with taking some Traditional money earlier.
You may voluntarily recognize more taxable income during the first years of retirement.
But you may also enter later retirement with a smaller Traditional balance.
Neither result is automatically better.
The important point is that optimizing one year can be very different from optimizing an entire retirement.
Looking only at this year’s taxes misses most of the story.
For each withdrawal path, you would want to compare:
Taxes paid
How much tax is paid across retirement, not just during the first year.
Future RMDs
How much may eventually have to come out of Traditional retirement accounts under applicable distribution rules.
Roth balance
How much tax-free flexibility remains available for later years.
Lifetime spendable income
How much money is actually available to use after taxes.
Ending portfolio
How much remains at the end of the projection.
Success
Whether the portfolio continues supporting the retirement spending goal across the modeled outcomes.
The three paths can start with the exact same portfolio.
They can fund the exact same $75,000 lifestyle.
Yet years later, their account balances and tax profiles may look very different.
That is what makes withdrawal order a retirement-planning decision rather than simply a withdrawal decision.
There is no single withdrawal order that works for every retirement.
The better question is:
Which account should fund this year without creating unnecessary problems later?
You want to keep taxable income relatively low in the early years of retirement.
You also may prefer to leave your Traditional and Roth accounts invested longer.
But this approach can allow a large Traditional balance to keep growing, which may matter later when required distributions begin.
You retire before other major income sources begin.
Those years may create an opportunity to take controlled withdrawals from Traditional accounts while taxable income is relatively lower.
That can reduce the amount left in Traditional accounts later.
The tradeoff is simple: you may choose to pay more tax today in exchange for potentially reducing taxable withdrawals later.
You want more control over how much taxable income you recognize each year.
Instead of draining one account completely before touching another, you can combine sources.
For example, part of your spending might come from taxable assets while another portion comes from a Traditional account.
Roth assets could remain available for years when additional taxable income would be especially costly.
The goal is not necessarily to minimize withdrawals from any one account.
It is to preserve options.
The right source at 65 may not be the right source at 75.
Early retirement might favor one combination.
Social Security starting could change it.
Required distributions could change it again.
A large expense could make Roth money more useful in a particular year.
That is why a retirement withdrawal strategy does not have to be:
Taxable until empty → Traditional until empty → Roth last.
It can be adjusted year by year as the rest of the plan changes.
Most retirement advice focuses on getting money into accounts.
Save more.
Use a 401(k).
Build a Roth balance.
Invest consistently.
But retirement eventually creates the opposite problem:
How do you turn those accounts back into spendable income?
That is decumulation.
And withdrawal order is one of its most important decisions.
The same portfolio can support different tax patterns, different future account balances, and different levels of flexibility depending on how the money comes out.
So when retirement begins, do not stop planning just because the saving phase is over.
Your next question is no longer simply:
“Do I have enough?”
It becomes:
“How should I use what I built?”
Start from your current plan, change one assumption from the article, and save the version only if it is worth comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
Waiting to touch your traditional retirement accounts can feel logical. But the years before RMDs begin may be an opportunity to choose when you pay taxes.
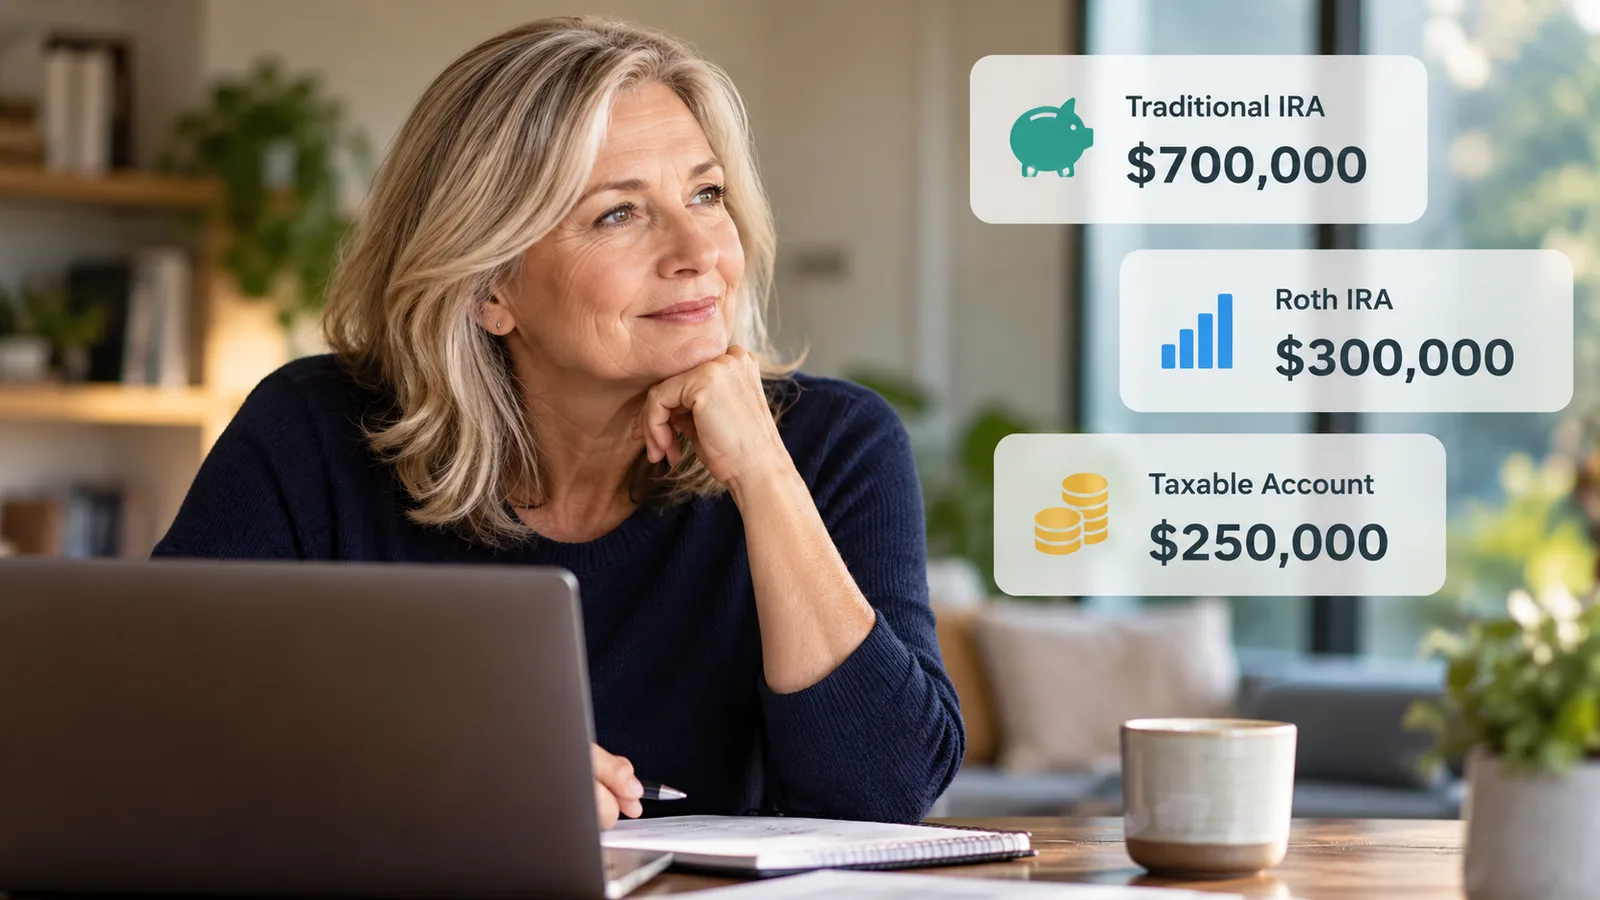
Roth money can be one of your most flexible retirement accounts. The question is not just whether you can spend it, but when using it may actually help.
Should you use $300,000 to buy lifetime income or keep it invested? Compare what happens at ages 75, 85, and 95.
