8 min read • Published 9 days ago
You retire at 65 with $1.5 million. You want to spend $5,000 a month, adjusted for inflation, for 30 years.
That sounds like one goal. It is actually two: keep the portfolio alive and keep your lifestyle intact. A strategy can do one without doing the other.
We tested four withdrawal policies across 8,000 identical simulated market paths. The result was not a universal winner. It was a map of what each strategy protects—and what it asks you to give up.
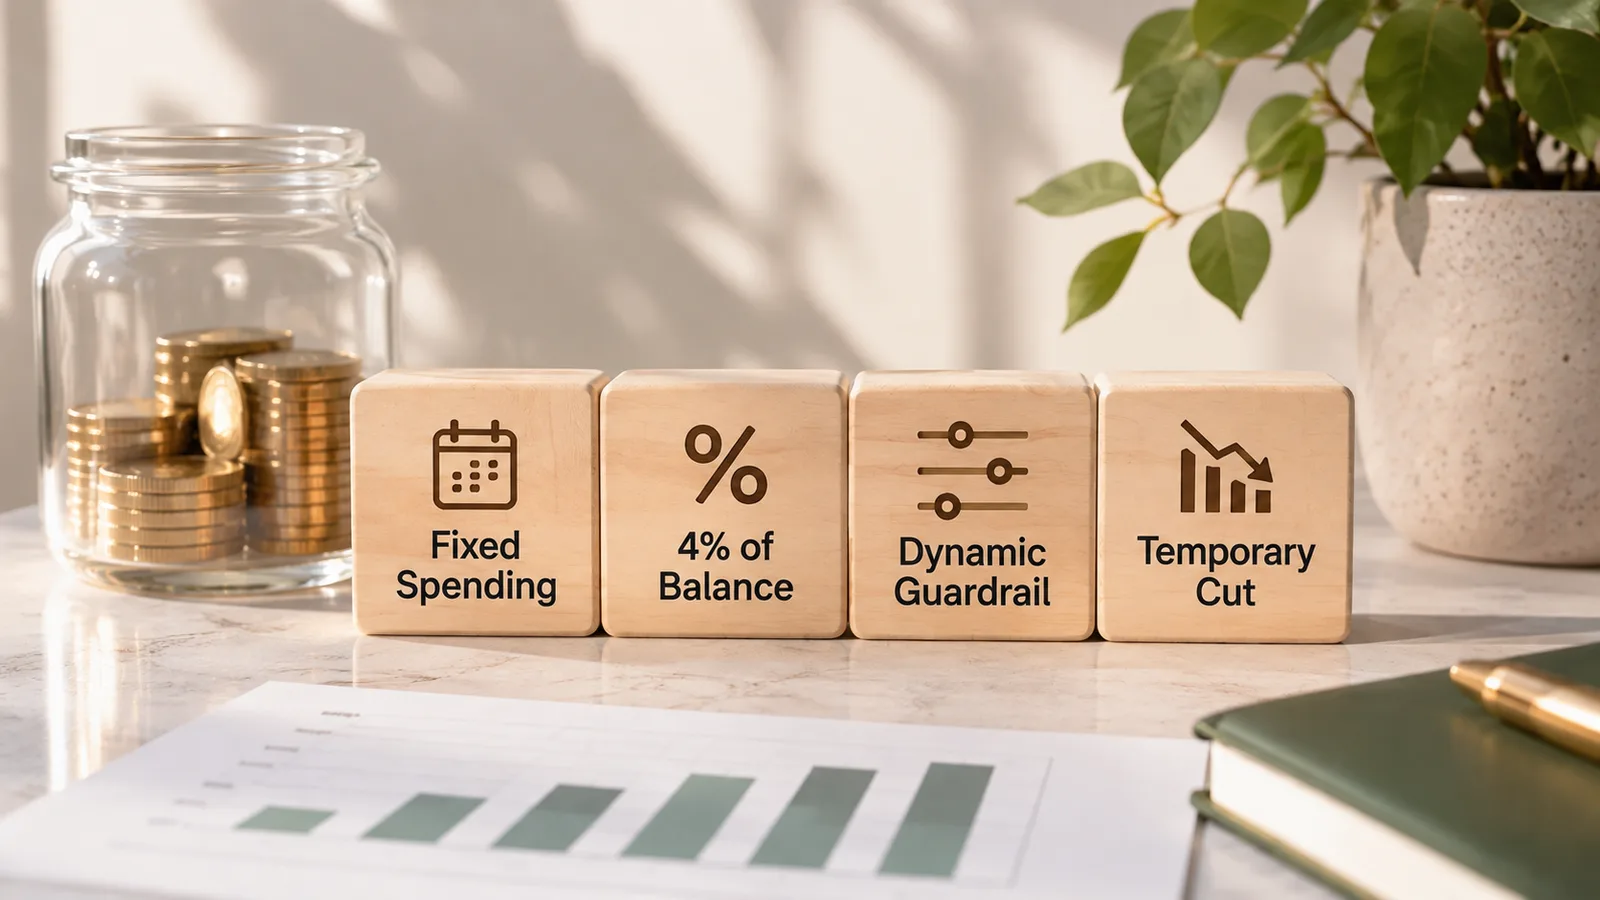
Fixed spending starts at $60,000 a year and raises that amount with inflation. It tries hardest to preserve the original lifestyle.
Four percent of current balance withdraws 4% of whatever remains each year. Spending rises and falls with the portfolio.
Dynamic guardrails start at 5% of the portfolio—$75,000, or $6,250 a month here. Spending is adjusted by 10% when the withdrawal rate moves outside 4%–6% guardrails.
Temporary cuts normally target $60,000, but cut spending 10% for two following years after the stock market loses at least 15%. Another qualifying loss restarts the two-year period.
Fixed spending protected the original target in 95.7% of paths. Its portfolio also survived in 95.7%. When this policy failed, the problem was depletion—not a voluntary cut.
The 4%-of-balance policy produced 100% portfolio survival, yet maintained the original target every year in only 20.6% of paths. Its own policy-specific success rate was 60.5%, using a 15% tolerance around its balance-derived target.
The guardrail policy also produced 100% portfolio survival and 100% success under its own rule, which treats its planned adjustments as part of the policy. But it preserved the original $5,000 target every year in 55.5% of paths.
Temporary cuts lifted portfolio survival from 95.7% to 96.6%. But because a planned cut counts as missing the uncut lifestyle target, original-target success fell to 12.4%.
The headline “100% survival” sounds decisive. It is not.
The 4%-of-balance strategy never depleted the portfolio because withdrawals automatically shrank with it. The median household received about $2.06 million in lifetime real spending—more than the $1.8 million target—but income was highly variable. In weaker paths, lifetime spending fell to about $1.49 million at the 10th percentile.
The default guardrail began 25% above the article’s target. That explains why its median lifetime spending reached $2.15 million even though 44.5% of paths dipped below the original target at least once. It is a flexible, higher-start policy—not an equal-start replacement for fixed spending.
| Strategy | Lifetime spending, P10 / median / P90 | Median years below target | Median ending wealth |
|---|---|---|---|
| Fixed spending | $1.80M / $1.80M / $1.80M | 0 | $2.22M |
| 4% of balance | $1.49M / $2.06M / $2.85M | Not reported as a cut metric; P90 was 26 years below target | $1.83M |
| Dynamic guardrail | $1.59M / $2.15M / $2.94M | 0; P90 was 21 years | $1.32M |
| Temporary cut | $1.75M / $1.78M / $1.80M | 4 | $2.28M |
Temporary cuts occurred in 87.7% of paths. The median path spent four years under a cut and gave up $24,000 in lifetime real spending. In return, median ending wealth rose by about $52,000 versus fixed spending on the same market paths.
The 4%-of-balance and guardrail policies made balance-driven adjustments, but the research contract does not label those as “downturn cuts.” Their reductions are reported separately as voluntary spending reductions.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
If the priority is preserving a stable $5,000 monthly lifestyle, fixed inflation-adjusted spending performed best in this experiment.
If the priority is avoiding depletion, balance-based and guardrail policies did that—but by allowing spending to move. The temporary-cut policy occupied the middle: a modest improvement in portfolio survival and ending wealth in exchange for predictable, temporary reductions.
None is best for everyone. The useful question is not simply, “Did the money last?” It is, “What happened to spending while it lasted?”
Good retirement planning is not only about whether money survives. It is about whether your lifestyle survives with it.
Research ID research-8xG3dJkvIf5DJdELfYeu0. Nestly ran 8,000 aligned historical-resampling paths with seed 20261104 and 30 start-of-year withdrawals from age 65. The engine used 1970–2025 annual S&P 500, 10-year Treasury, and 3-month Treasury bill returns; a simulated 46.02% stock, 48.98% bond, 5% cash allocation; annual rebalancing; 2.5% inflation; and a 0.5% annual fee. All $1.5 million was modeled as pretax savings under 2026 tax assumptions. Results are hypothetical estimates, not forecasts or personalized financial, tax, or legal advice.
Load all 2 tests from this article against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
How much cash should you keep in retirement? Explore nine cash-reserve strategies across 8,000 simulations and the tradeoffs between liquidity and long-term growth.
Compare staying in your current home, downsizing, or relocating before retirement. See how housing costs, home equity, moving expenses, and lifestyle can change your retirement plan.
A market crash right after retirement can be more damaging than the same decline years later. Learn how sequence-of-returns risk works and how flexible spending, cash reserves, and retirement timing can help.
