10 min read • Published 2 months ago
Load all 3 article strategies with your numbers before you decide.
For decades, retirement planning has one dominant goal:
Save more.
Build the portfolio. Avoid lifestyle inflation. Max the retirement accounts. Prepare for bad markets. Make sure the money lasts.
Then one day, the numbers say you made it.
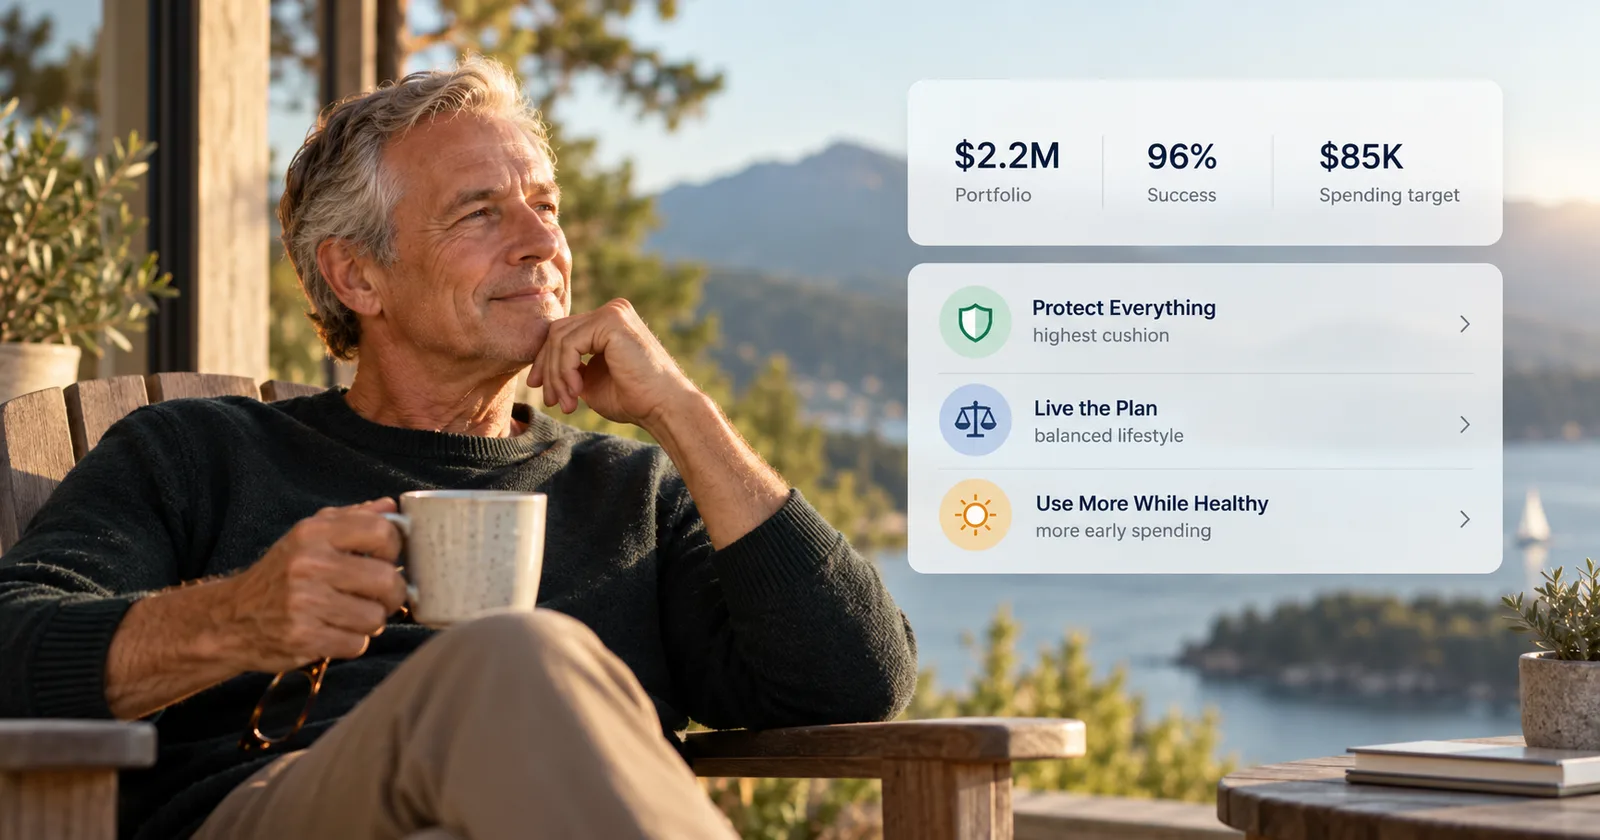
Consider someone retiring at 64 with:
The plan works.
But retirement begins, and something strange happens.
Instead of spending the $85,000 they planned for, they continue living on roughly $65,000 a year.
Not because the plan requires it.
Because spending the money suddenly feels dangerous.
After spending 30 or 40 years learning how to accumulate wealth, switching from “save” to “use” can be surprisingly difficult.
If your plan already works, what exactly are you protecting the extra money for?
While you're working, being conservative often has an obvious payoff.
Saving another $10,000 increases your retirement balance.
Working another year gives the portfolio more time.
Spending less creates a larger margin for uncertainty.
Those behaviors helped build the retirement plan.
But they do not automatically remain optimal forever.
Once retirement is adequately funded, another dollar preserved still has value.
The question is what you're giving up to preserve it.
That could mean:
The financially safest retirement is not automatically the retirement you would choose.
Sometimes the extra safety has a lifestyle price.
Now imagine that same 64-year-old comparing three different ways to use the same $2.2 million portfolio.
The starting point is identical.
What changes is the purpose of the money.
| Protect Everything | Live the Plan | Use More While Healthy | |
|---|---|---|---|
| Spending | $65,000/year | $85,000/year | $105,000/year from 64–74, then lower |
| Financial resilience | Highest | Still strong | Lower |
| Early-retirement lifestyle | Most restrained | Matches the plan | Highest |
| Likely legacy | Largest | Smaller | Smallest |
| Main goal | Preserve wealth | Balance today and tomorrow | Use more while healthy |
None of these paths is automatically better.
They simply protect different things.
The first retiree keeps spending around $65,000 a year.
That is $20,000 below the lifestyle the retirement plan was originally designed to support.
The benefit is easy to understand.
More money stays invested.
The portfolio has more room to absorb bad markets, unexpected expenses, or a longer-than-expected retirement.
The retiree may also leave a substantially larger legacy.
But there is another side to the decision.
If the retiree spends $20,000 less every year simply because spending feels uncomfortable, they may be purchasing protection they never consciously decided they needed.
What is the extra safety actually for?
If the answer is a larger inheritance, future healthcare costs, or another clearly defined goal, protecting the money may be exactly right.
If the answer is simply “I don't want to see my balance go down,” the decision deserves another look.
The second retiree spends the $85,000 a year the retirement plan was designed around.
This can feel surprisingly aggressive after decades of saving.
Withdrawals are now visible.
The portfolio may not climb every year.
A market decline can feel more serious when there is no paycheck replenishing the account.
But this retiree is not abandoning the plan.
They are actually following it.
The money was accumulated to support a certain retirement lifestyle.
Using it for that lifestyle is not necessarily a failure of discipline.
It may be the entire reason the portfolio exists.
The third retiree goes one step further.
They intentionally spend more during the first decade of retirement — perhaps $105,000 a year from age 64 through 74 — and then reduce spending later.
This path gives up some financial resilience.
It may also produce a smaller ending portfolio and a smaller legacy.
But it recognizes something that a portfolio balance alone cannot capture:
A dollar may have different lifestyle value at different ages.
At 66, additional money might fund a long international trip, family travel, golf, hiking, a second-home rental, or another experience that requires energy and mobility.
At 86, the same money can still be valuable.
But the opportunity to use it in exactly the same way may no longer exist.
That does not mean retirees should automatically front-load spending.
It means when you use the money matters alongside how much you preserve.
Suppose a retirement plan shows 96% Success.
It is tempting to think:
Could I make it 97%?
Then 98%.
Then 99%.
But Success is not necessarily a score where the goal is simply to make the number as large as possible.
Higher Success usually requires something.
You may need to:
Those tradeoffs may be worthwhile.
But they should be visible.
The better question is not simply:
How can I make my Success percentage higher?
It is:
What am I giving up to make it higher?
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Imagine Nestly starts with this retirement plan:
Current plan
Now compare higher retirement spending.
| Spending change | Illustrative Success | Additional lifetime spending |
|---|---|---|
| Current plan | 96% | — |
| +$500/month | 95% | ~$120,000 |
| +$1,000/month | 94% | ~$240,000 |
| +$2,000/month | 89% | ~$480,000 |
Illustrative only. Actual values should come from the individual retirement scenario.
Now the decision becomes more useful.
Instead of seeing only:
96% → 94%
you also see what those two percentage points may be buying:
roughly $240,000 more lifetime spending.
That does not mean spending the extra $1,000 per month is automatically the right choice.
It means you can finally see both sides of the tradeoff.
This is where Future Paths becomes more than a retirement-risk tool.
It can help price the lifestyle being exchanged for additional financial safety.
Try a higher spending level against your own plan:
Choose a higher spending level and compare the effect against your current retirement target.
A modest retirement raise
Increase your current retirement spending target by 10% and see how the added lifestyle affects your plan.
Each option is applied independently to your existing retirement spending target. Nestly Lab calculates the actual impact using your plan.
Test with my planThe goal is not to encourage more spending.
The goal is to make the tradeoff visible.
Traditional retirement planning measures things like:
Those all matter.
But there is another quantity that does not appear neatly on a balance sheet:
the lifestyle your portfolio could have supported but didn't.
Imagine someone reaches age 92 with $3 million.
Was that a fantastic retirement outcome?
Maybe.
If leaving $3 million to children, charities, or other people was intentional, the plan may have worked exactly as designed.
But suppose that person repeatedly skipped trips, worried about ordinary purchases, and lived far below the lifestyle their plan could reasonably support because they were afraid of seeing the portfolio decline.
The same $3 million ending balance now tells a different story.
The issue is not that they saved too much.
The issue is that they may never have decided what the money was ultimately supposed to accomplish.
Many retirees genuinely want to leave substantial wealth behind.
That is a perfectly valid use of money.
But there is a meaningful difference between:
“I want to leave my children $2 million.”
and:
“I was too nervous to spend the portfolio, so my children happened to inherit $2 million.”
The first is a financial goal.
The second may simply be the result of fear.
If legacy matters deeply to you, protect it deliberately.
If it does not, a very large projected estate may be telling you something else:
You may have more capacity to use your money during your own lifetime than you realized.
Most retirement planning emphasizes the risk of running out of money.
That risk matters.
But once a plan becomes financially strong, another risk deserves attention:
reaching the end with money you would have happily traded for experiences earlier.
Reducing one risk can increase exposure to the other.
Spend less:
Spend more:
Neither answer should come automatically from a Success percentage.
The purpose of the projection is to help you understand the trade.
If you're financially independent and still reluctant to spend, do not start with the vague question:
Could something go wrong?
Something always could.
Ask more specific questions instead:
The answer may still be:
Keep spending $65,000.
But now it is a decision.
Not a reflex.
Most retirement tools are designed around one question:
Can I afford to retire?
That is the right question while you're trying to get there.
But eventually, successful retirees need a different question:
Now that the plan works, how much additional safety are you willing to buy — and what lifestyle are you giving up to buy it?
You spent decades accumulating money so that eventually money could give you choices.
Once you have enough, the goal does not always have to be more.
It can finally become:
What do I want this money to do?
Load all 3 tests from this article against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
At some point, saving more stops being about making retirement possible and starts being about buying extra safety. Here’s how to know when easing off may make sense.
Should you use $300,000 to buy lifetime income or keep it invested? Compare what happens at ages 75, 85, and 95.
See how a spouse's retirement savings and income can dramatically improve retirement success, with clear calculations comparing a base plan, pension, rental income, and combined household finances.
