4 min read • Published 2 months ago
Load all 3 article strategies with your numbers before you decide.
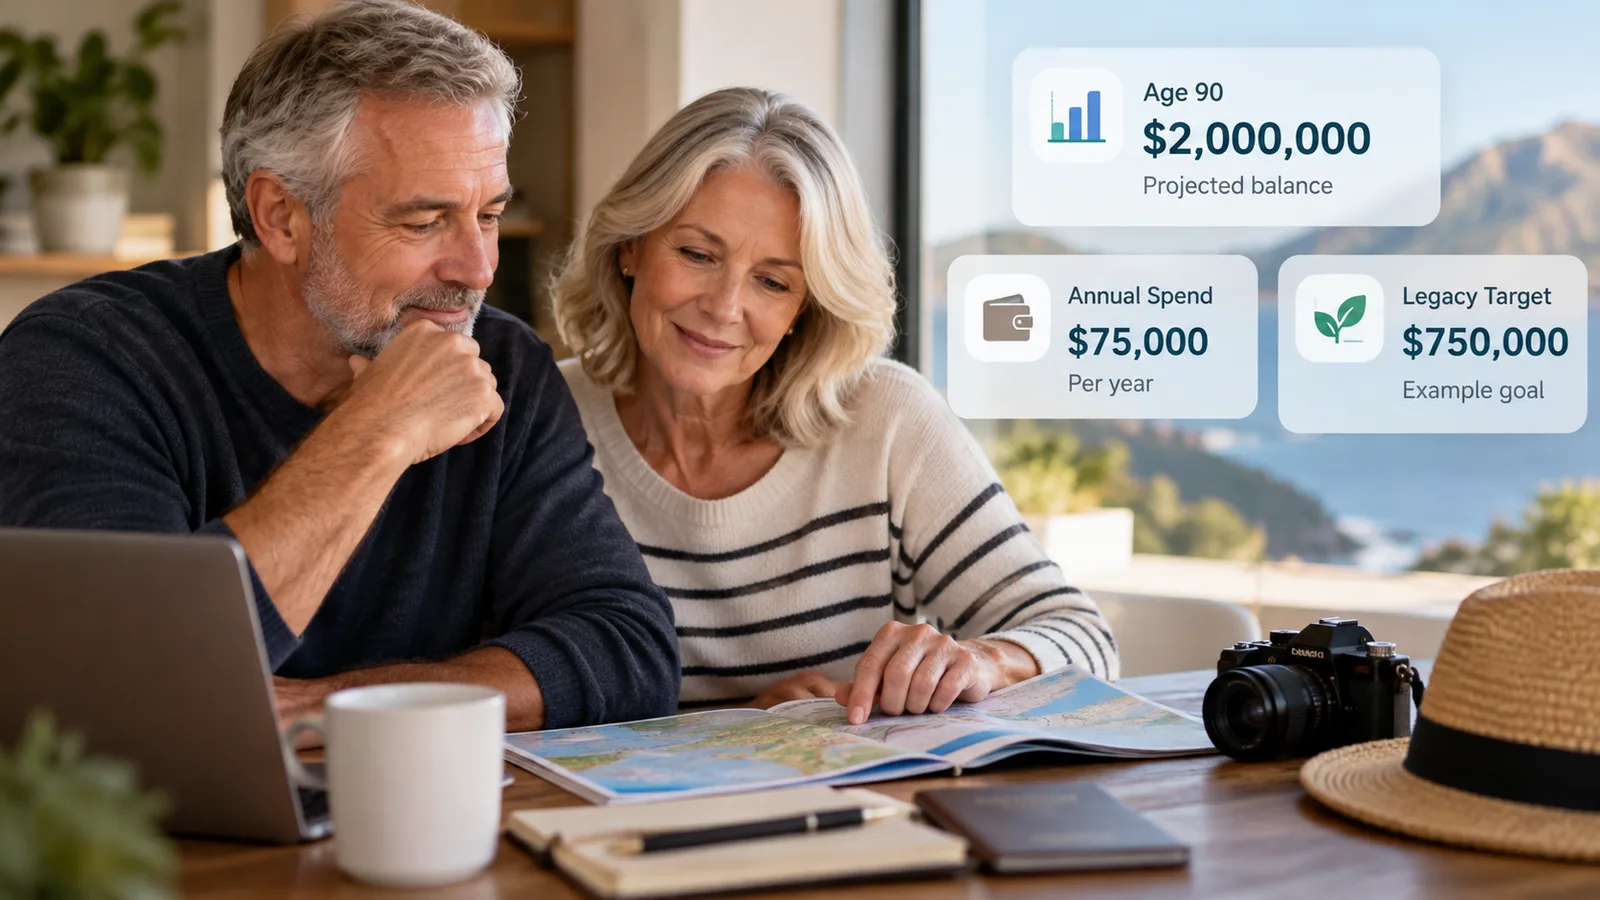
You’re 65 with $2.2 million invested.
Your retirement plan looks strong. You spend about $75,000 a year, and the projection still shows roughly $2 million remaining at age 90.
That’s good news.
But it creates a different question:
What did you want the money to do?
Most retirement planning focuses on avoiding one outcome: running out of money.
But once your plan looks strong, the question changes.
A large ending balance can mean more security, more flexibility, and a larger inheritance.
It can also mean you spent decades protecting money you never intended to use.
There isn’t one correct answer.
The better question is what you want your retirement savings to accomplish.
| Path | What you do | What it prioritizes |
|---|---|---|
| Preserve More | Keep spending around $75K | Larger cushion and legacy |
| Enjoy More | Increase retirement spending | More experiences and lifestyle spending |
| Choose a Target | Decide how much you intentionally want left | Balance today and tomorrow |
You keep spending about $75,000 a year.
Your current lifestyle already works, so you don’t feel much reason to change it.
That could leave you with a large portfolio later in retirement.
And that may be exactly what you want.
Maybe you want a substantial inheritance for your children. Maybe you want extra protection for healthcare, long-term care, or living well beyond 90.
There is nothing wrong with preserving more.
The important part is knowing why you are doing it.
See how spending 10% less than your current retirement target could affect your plan and projected ending wealth.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Now imagine increasing your retirement spending.
That might mean better vacations, more frequent travel, helping family, improving your home, spending more on hobbies, or simply being less cautious with everyday purchases.
Your ending portfolio may become smaller.
But that doesn’t automatically mean the plan became worse.
You may simply be converting some future wealth into experiences and comfort today.
See how spending 20% more than your current retirement target changes your plan and projected ending wealth.
All article tests · No account neededOpens every article test in Lab. No account required until you save.How much ending wealth are you willing to trade for more life along the way?
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
This is where retirement planning gets more interesting.
Instead of trying to maximize whatever is left at age 90, choose an amount you actually want to preserve.
Maybe that number is $750,000.
Not because $750,000 is the right answer.
But because you decide it gives you enough legacy, flexibility, and cushion for the future.
Now your plan has a different goal.
Instead of asking:
How much money can I avoid spending?
You can ask:
How much could I comfortably use while still preserving what matters to me?
That turns your ending balance from an accidental result into an intentional decision.
See how spending 40% more than your current retirement target changes your plan and projected ending wealth.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Seeing $2 million remaining at age 90 can feel reassuring.
But retirement planning is not a contest to finish with the highest balance.
For one person, leaving $2 million may be exactly the goal.
For another, leaving $750,000 while spending more during their healthy years may feel more meaningful.
Someone else may want something completely different.
What matters is that the ending balance reflects your priorities rather than simply being whatever happens to remain.
Your ending portfolio doesn’t have to be an accident. It can be part of the plan.
The next time your retirement projection shows a large amount remaining late in life, don’t only ask whether the plan is safe.
Ask one more question:
Is that how much I actually want to leave?
Load all 3 tests from this article against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
Should you use $300,000 to buy lifetime income or keep it invested? Compare what happens at ages 75, 85, and 95.
See how a spouse's retirement savings and income can dramatically improve retirement success, with clear calculations comparing a base plan, pension, rental income, and combined household finances.
See how a smaller Social Security benefit could change your retirement withdrawals—and three ways to respond.
