4 min read • Published 9 months ago • Updated Jun 11, 2026
Load this article strategy with your numbers before you decide.
Retirement is often pictured as a time of fewer financial obligations.
But in reality, many retirees face large one-time purchases right around retirement—especially cars.
Whether it’s replacing an aging vehicle, downsizing, relocating, or simply wanting something reliable for the next decade, buying a car at retirement is extremely common.
The challenge?
It often happens at the exact moment when income shifts and financial flexibility tightens.
A car purchase near retirement creates a unique financial tension:
Unlike earlier in life, there’s no future salary to “smooth out” the impact.
This makes timing and funding strategy far more important than the sticker price alone.
Many people approach a retirement-era car purchase the same way they did at 40.
That’s risky.
At retirement, a $40,000–$50,000 car isn’t just a purchase—it’s:
The cost isn’t just what you pay today—it’s what that money could have supported over the next 20–30 years.
If possible, buying a car 1–2 years before retirement can:
Planning beats reacting.
Pulling a large amount from a 401(k) to buy a car can:
If withdrawals are necessary, plan them intentionally and understand the long-term impact.
In retirement, the question isn’t “Can I get a loan?”—it’s “What’s least disruptive?”
Consider:
There’s no universal right answer—only tradeoffs.
This isn’t about deprivation—it’s about alignment.
Ask:
Choosing a reliable, lower-cost vehicle can protect flexibility later.
Cars aren’t one-time events.
Most retirees will replace vehicles at least once more.
Ignoring future replacements creates hidden risk.
Planning ahead avoids unpleasant surprises in your 70s or 80s.
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
A car purchase affects:
This is why static retirement rules often fall short.
What matters isn’t just how much you’ve saved—it’s how you deploy it.
Nestly helps retirees see the full picture.
With Nestly, you can:
Instead of guessing, you can see the ripple effects before committing.
Retirement isn’t a pause button—it’s a new financial phase.
Big purchases will still happen:
The goal isn’t to avoid spending—it’s to spend intentionally without regret.
Buying a car at retirement isn’t a mistake.
Buying one without planning can be.
The key is understanding:
A thoughtful plan lets you enjoy retirement without sacrificing security.
Related Reading
Want to see how a major purchase affects your retirement income?
Use Nestly to model real-life scenarios and make confident decisions—before the money is spent.
See how a lump-sum car purchase around retirement affects your long-term plan.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Load "Model the Lump-Sum Draw" against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
Retiring while still paying for a child’s college is more common than you think. Learn how to balance 401(k) planning, tuition costs, and long-term financial security.
Retirement planning is entering a critical window. Learn why decisions made in 2025–2026—from contribution limits to AI-powered planning—can shape your financial future for decades.
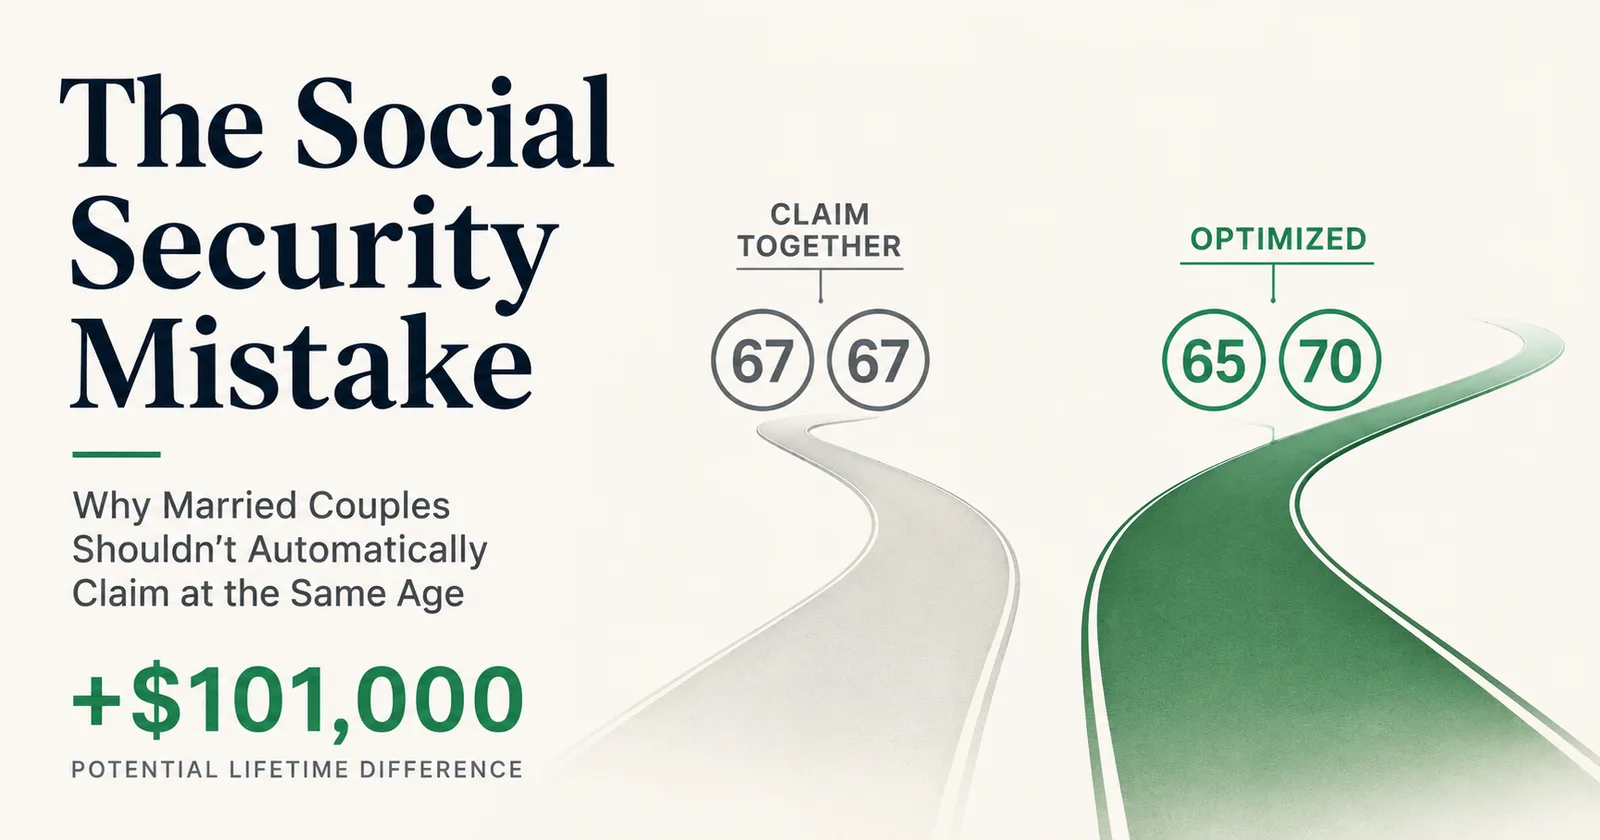
Many couples claim Social Security at the same age without realizing it may reduce lifetime benefits. Learn how coordinated claiming strategies can improve retirement income and long-term financial outcomes.
