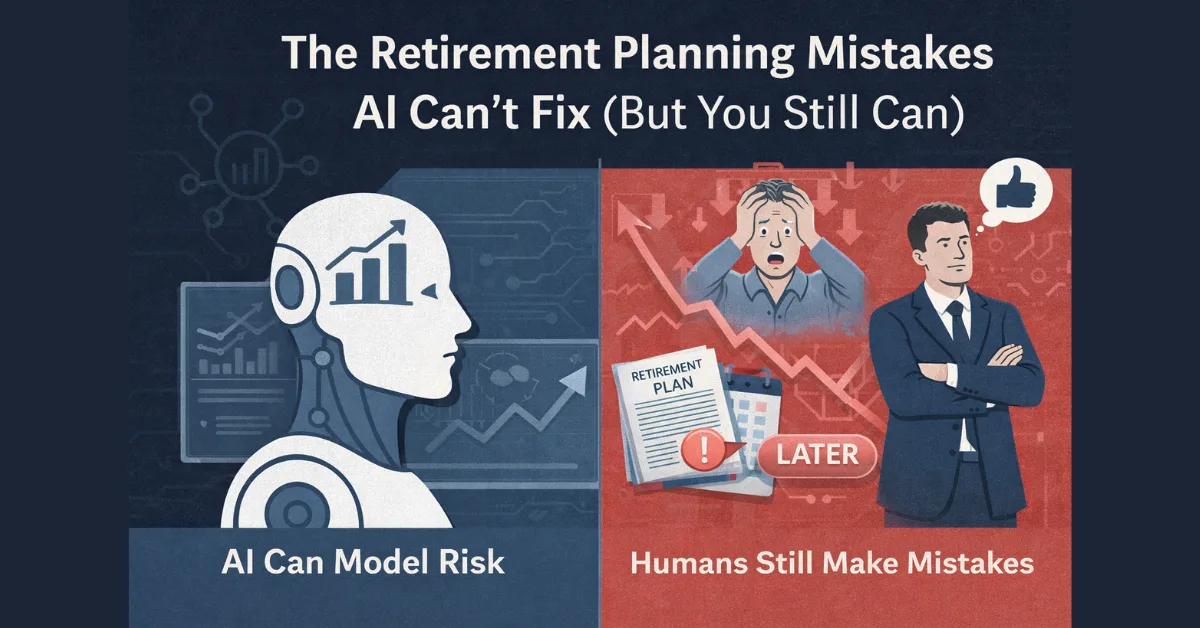
5 min read • Published 10 months ago • Updated Jun 11, 2026
Artificial intelligence has dramatically improved how we plan for retirement. AI can model thousands of market scenarios, optimize portfolios, and personalize projections in ways that were impossible just a decade ago.
But there’s one thing AI can’t fix:
Human behavior.
Even with the most advanced tools, retirement outcomes are still shaped by decisions—often emotional ones—that happen in moments of fear, overconfidence, or procrastination.
This article breaks down the most common retirement planning mistakes that AI won’t solve for you—and what you can do instead.
AI can simulate downturns. AI can show probabilities. AI can warn you about risk.
But when markets fall sharply, many investors still panic.
Selling during a downturn locks in losses and prevents recovery. History shows that missing even a handful of strong rebound days can permanently reduce long-term returns.
What You Can Do
AI can model longevity scenarios—but many people still underestimate how long their money needs to last.
Retirement is no longer a 10–15 year phase. For many, it can last 25–35 years or more.
What You Can Do
Some people assume that because tools are smarter, they can afford to start later.
This is one of the most expensive assumptions in retirement planning.
AI can optimize how you save—but it cannot replace time.
Compound interest rewards early action far more than perfect optimization later.
What You Can Do
Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
Monte Carlo simulations and AI-driven projections are powerful—but they are not promises.
A 75% success probability still means there’s a meaningful chance things don’t go as planned.
What You Can Do
AI models are only as good as the inputs you give them.
Life changes—jobs, income, health, family needs—and many people fail to update their plans accordingly.
What You Can Do
AI works best when it’s used as a decision-support system, not an autopilot.
The goal isn’t to eliminate uncertainty—it’s to understand it.
The most successful retirement savers use AI to:
Nestly is designed to make retirement planning clearer—not more complicated.
By combining AI-driven modeling with transparent visuals and realistic assumptions, Nestly helps users:
AI doesn’t replace judgment—but it can make better judgment easier.
AI is transforming retirement planning—but it doesn’t remove responsibility.
The biggest retirement mistakes aren’t technical. They’re human:
Technology can guide you—but only you can commit to better decisions.
The future of retirement belongs to those who combine smart tools with disciplined behavior.
Plan thoughtfully. Stay flexible. Start early.
Related Reading
Ready to see how smarter planning can change your future?
Explore your retirement scenarios with Nestly and see the impact of today’s decisions—clearly.
Start from your current plan, change one assumption from the article, and save the version only if it is worth comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
Artificial intelligence is transforming jobs, investing, and financial planning. Learn how AI growth will impact retirement savings, risk management, and how to prepare.
Retirement planning is entering a critical window. Learn why decisions made in 2025–2026—from contribution limits to AI-powered planning—can shape your financial future for decades.
The IRS has officially released 401(k) and IRA contribution limits for 2026. Learn the new limits, catch-up rules, and how Nestly’s Contribution Co-Pilot helps you optimize savings.
