7 min read • Published 3 months ago • Updated Aug 15, 2026
Load all 3 article strategies with your numbers before you decide.
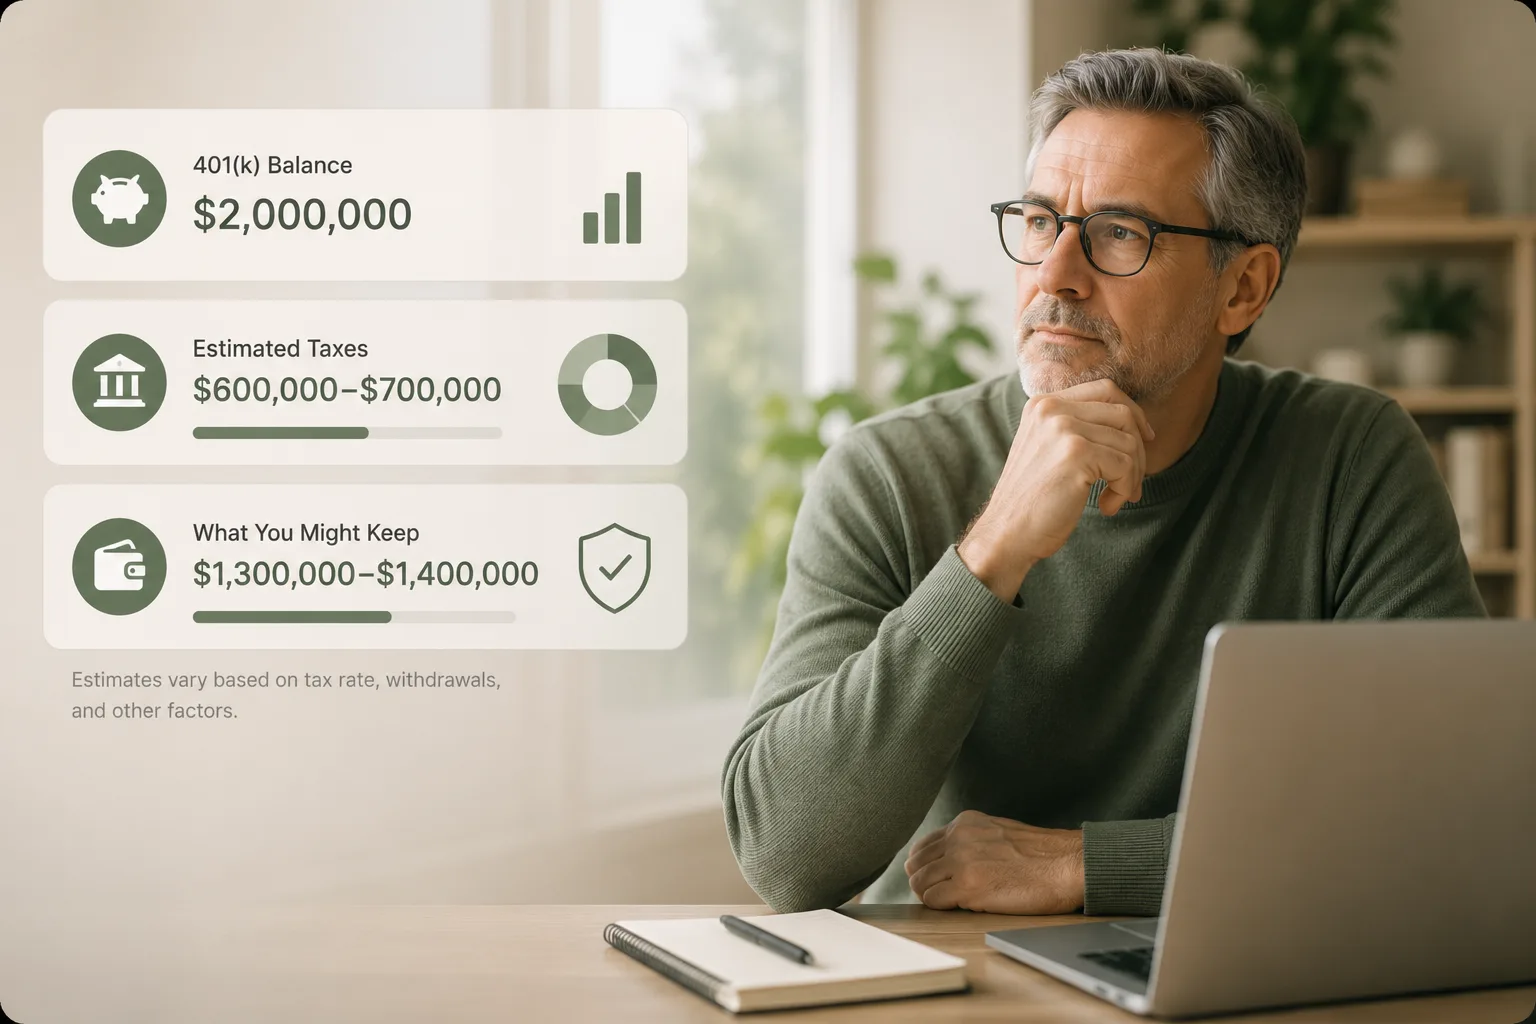
You open your retirement account and see:
401(k) balance: $2,000,000
It feels like you have $2 million available to spend in retirement.
But if most of that money is in a traditional 401(k), income taxes generally haven't been paid on that money yet.
So the more useful question isn't:
How much have I saved?
It's:
How much of my retirement savings can I actually spend?
Two retirees can both have $2 million and still have very different retirement outcomes.
The reason is simple:
Where your money is held matters.
Imagine three 65-year-olds.
Each has exactly:
$2,000,000
But their money is held differently.
| Retiree | Where the $2M Is | General Tax Treatment |
|---|---|---|
| A | Traditional 401(k) | Withdrawals generally taxable as ordinary income |
| B | Roth accounts | Qualified withdrawals generally federal income-tax-free |
| C | Taxable investments | Taxes generally depend on gains, basis, dividends, and other factors |
On a net-worth screen:
$2M = $2M = $2M
But those portfolios are not economically identical in retirement.
Here's why.
Suppose you withdraw:
$100,000
from a traditional 401(k).
Assuming the account consists of pre-tax contributions and earnings, that withdrawal is generally included in taxable income.
So:
$100,000 withdrawn
does not necessarily mean:
$100,000 available to spend
Income taxes may reduce what ultimately stays in your pocket.
That does not make a traditional 401(k) bad.
You may have received valuable tax benefits while contributing during your working years.
The important point is simply:
Your account balance and your after-tax spending power aren't necessarily the same number.
Now imagine the same:
$100,000
comes from a Roth account.
If the withdrawal meets the requirements for a qualified distribution, it is generally federal income-tax-free.
So the experience can look very different.
$100K withdrawal
↓
Potential income tax
↓
Amount available to spend
$100K qualified withdrawal
↓
Generally no federal income tax on the withdrawal
↓
Potentially $100K available to spend
This does not mean:
Roth = good
and
Traditional = bad
It means:
The account your money lives in changes how that money may eventually fund your retirement.
Now suppose you sell:
$100,000
of investments from a taxable brokerage account.
You generally aren't taxed on the entire $100,000 as ordinary income simply because you sold investments.
The tax result can depend on:
So Traditional, Roth, and taxable accounts can all behave differently.
And that creates an important retirement-planning opportunity:
tax diversification.
Now let's keep the total wealth exactly the same.
Only change where the money sits.
90% Traditional
5% Roth
5% Taxable
For someone with $2 million, that would illustrate roughly:
The headline balance looks excellent.
But much of the portfolio may eventually create taxable income as money is withdrawn.
See how your current retirement balance behaves when 90% is held in traditional accounts.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Keep the same total portfolio.
Now use:
60% Traditional
20% Roth
20% Taxable
For the same hypothetical $2 million:
Nothing was added.
The retiree still has exactly:
$2 million
But now there are different places from which retirement income may potentially be drawn.
See how the same retirement balance behaves when it is spread across traditional, Roth, and taxable accounts.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Now compare:
35% Traditional
45% Roth
20% Taxable
For our $2 million example:
Again:
Same $2 million.
But potentially a very different future tax and withdrawal profile.
See how the same retirement balance behaves when a larger share is held in Roth accounts.
All article tests · No account neededOpens every article test in Lab. No account required until you save.Your personalized projection
See what your retirement could look like.
Get an instant estimate of your portfolio at retirement, sustainable monthly income, retirement timeline, and readiness score.
Describe your future.
Tell Nestly about your finances, goals, or future plans in plain English.
The difference isn't limited to the tax bill on one withdrawal.
Large traditional-account balances can eventually create larger taxable withdrawals.
Those withdrawals can interact with other parts of retirement, including:
Traditional withdrawals
↓
Taxable income
↓
Future RMDs
↓
Social Security taxation
↓
Potential Medicare income-related premiums
↓
Spendable retirement income
This is why looking only at your total balance can hide part of the retirement picture.
There is an important catch.
The solution is not automatically:
"Put everything in Roth."
Traditional 401(k) contributions may have provided valuable tax advantages during high-income working years.
Roth contributions generally require paying taxes earlier instead.
Taxable accounts have their own benefits and tax considerations.
The better strategy depends on factors such as:
There is no single perfect mix for everyone.
The goal is to understand the trade-offs.
Imagine two retirees.
Both see:
Retirement savings: $2,000,000
One has almost everything in a traditional 401(k).
The other has money spread across:
Their net worth may be identical.
But their ability to control where retirement income comes from can be very different.
That's something a headline balance doesn't show.
Instead of using the article's $2 million example, Nestly Lab applies these account mixes to your own existing portfolio total.
Compare:
90% / 5% / 5%
60% / 20% / 20%
35% / 45% / 20%
Your total savings stay the same.
Only the account mix changes.
Then compare how each path affects your retirement projection.
The goal isn't to find the account mix with the biggest-looking balance.
It's to understand:
How might the same amount of wealth translate into different retirement outcomes?
A $2 million retirement balance is an impressive milestone.
But the number alone doesn't tell the entire story.
$2 million mostly Traditional
isn't economically identical to
$2 million mostly Roth
or
$2 million spread across multiple account types.
Your balance tells you:
what you own.
Your account mix helps determine:
how that money may fund your retirement.
And that leads to the next Future Paths question:
Should you convert some of your traditional retirement savings to Roth after you retire?
Important Disclaimer: This article is for educational purposes only and is not individualized tax, investment, legal, Medicare, or retirement advice. Tax treatment depends on account type, contribution history, withdrawal qualifications, cost basis, income, current tax law, and individual circumstances. Tax laws and retirement-account rules can change. Consider qualified tax or financial professionals when making retirement tax decisions.
Load all 3 tests from this article against your current assumptions. If a result is useful, save it to keep comparing later.
How we make these. Articles are produced by the Nestly Editorial Team. We use AI for formatting and proofreading, and to create article images. Every Read & Try scenario runs on the Nestly Lab What-If Engine, powered by Nestly Horizon, our proprietary projection and calculator engine, so you can test it with your own numbers.
Learn what happens when Required Minimum Distributions begin, how the first-year deadline works, how multiple IRAs and 401(k)s are handled, and what to avoid before your first RMD.
Learn what required minimum distributions are, when they start, how they are calculated, and what different retirement account balances could mean for your future withdrawals.
Compare investing more for retirement with paying off your mortgage early. See how interest rates, employer matches, taxes, retirement timing, and risk can change the answer.
